
Cloud stocks continue to do well in the market as these companies are growing very fast. This quarter we chose Cloudflare, Datadog, Dropbox, Bill.com, Five9, and RingCentral with some already reporting today and some reporting soon.
To understand valuations across cloud stocks and how the sector is positioned, please refer to our analysis “I/O Fund’s Cloud Q3 2021 Earnings Overview”
Cloudflare Inc – Earnings on November 04
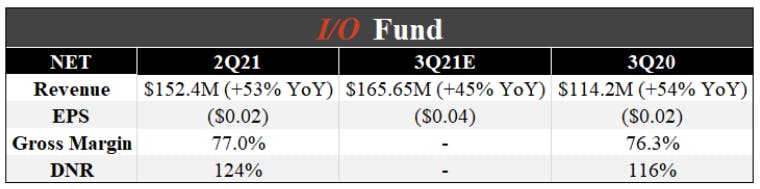
Cloudflare’s Q3 sales grew 51% YoY to $172 million, which beat the consensus estimate of $166 million by 4%. The company also expects Q4 sales to grow 47% YoY to $185 million, which is 5% higher than the Street’s initial forecast of $176 million.
Source: Earnings report and YCharts
Cloudflare’s revenue grew from $85M in 2016 to $431M in the year 2020, a compounded annual growth rate of 50% during the period. In the second quarter revenue grew 53% YoY to $152M, it was primarily helped by the strong growth in paying customers. At the end of the second quarter, it had 126,735 paying customers (+32% YoY) and it also witnessed a significant addition of large customers. This growth continued into Q3 as Cloudflare beat topline estimates by 4% after reporting strong YoY sales growth of 51% during the quarter.
Going into earning, Jefferies analyst Brent Thill had downgraded the company to a hold rating from a buy with a price target of $195. The analyst is concerned of the valuation after the strong share gains. However, he continues to view Cloudflare as the "most disruptive cyber vendor with strong fundamentals," he is of the view that “the company has the richest multiple in his coverage universe at 56 times enterprise value to consensus 2023 revenue estimates” and he "would look to get more constructive at a more reasonable valuation."
Needham analyst Alex Henderson has said that the company’s move into email security as a positive. He says “just one more example of why Cloudflare will become a major company.”
Please note, the I/O Fund is objectively reporting what the Street is saying. We covered Cloudflare previously here: Pinterest and Snap Show V-Shaped Recovery; Cloudflare Guns for Zero-Trust
Datadog Inc reports on November 04th
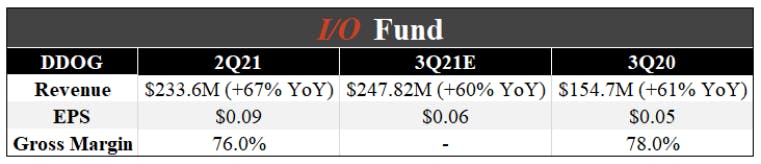
Datadog reported that Q3 sales grew 75% YoY to $270 million, which bested the consensus estimate of $248 million by 9%. The company expects Q4 sales to grow 64% YoY to $291 million, which is 10% higher than initial expectations.
Source: Earnings report and YCharts
In the prior quarter of Q2, Datadog reported strong second quarter results. It beat the analyst’s revenue estimates by $21M and the adjusted earnings by $0.06. The company had also raised the full-year revenue guidance to $938M-$944M, up from the previous guidance of $880M-$890M. Datadog continued this momentum and reported a 9% top line beat during Q3 and guided Q4 sales 10% higher than initially expected.
It also witnessed strong growth of large customers (annual recurring revenue of over $100,000) as they grew to 1,610 from 1,015 from the same period last year in Q2. This quarter, large customers grew to 1,800, up 66% from 1,082 in the prior year quarter.
RBC Capital analyst Matthew Hedberg has raised the company’s price target to $176 from $154 and has kept the Sector Perform rating on the shares. The analyst expects the company to report "strong" Q3 results with upside, building off last quarter's acceleration. The analyst adds that he expects Datadog to continue to benefit from continued traction in multi-module sales, strong new customer adds, and favorable cloud adoption trends.
Our previous analysis on the company:
Podcast with Motley Fool: Big Tech Plus the 1 Stock I’d Buy Right Now
Tech Growth Earnings Review for Q3 2020 - Part 2
Video: Our Stock Picking Strategy
Dropbox Inc reports on November 04th
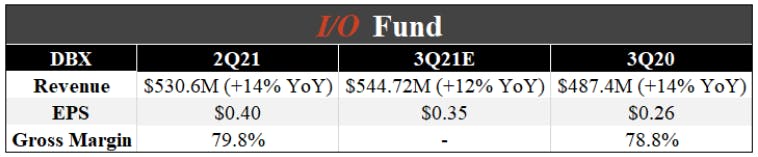
Dropbox reported Q3 sales of $550 million, which grew 13% YoY and came in 1% higher than the consensus estimate of $545 million. The company’s outlook for Q4 forecasted sales to grow 12% YoY to $563 million, 2% higher than the Street’s initial estimate of $553 million.
Source: Earnings report and YCharts
The company’s revenue growth is not very strong when compared to other cloud stocks. However, the company has got good free cash flow and it’s profitable. In the last quarter, the management has raised the full-year revenue guidance to $2.136B-$2.142B from $2.118B-$2.130B. It aims to generate annual free cash flow of $1B by the year 2024. The management revenue guidance for the third quarter is $543M-$546M, which represents a growth of 12% YoY at the mid-point.
Sign up for I/O Fund's free newsletter with gains of up to 1100% - Click hereSign up for I/O Fund's free newsletter with gains of up to 1100% - Click hereClick here
Jefferies analyst Brent Thill has a price target of $40 and a buy rating on the stock. He believes that the company’s increased full year guidance is still conservative.
Bill.com Holdings Inc reports on November 04th
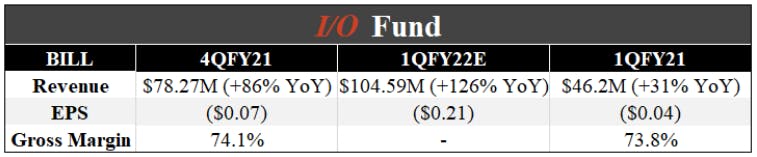
Bill’s Q1 FY22 sales were $116 million, which beat the consensus estimate by 11% and represented a 166% YoY growth rate (organic growth was 78% YoY). Bill.com guided for Q2 sales to grow 141% YoY to $131 million, which was 12% higher than initial estimates.