
The market evolves quickly, and nowhere is that more apparent than in AI stocks, which continue to lead in both innovation and returns.
At the I/O Fund, our deep coverage of AI stocks, combined with active management of crypto positions, gives us a unique vantage point. As we move into the second half of the year, we want to highlight key insights every investor should understand about where AI stocks and crypto could go next.
Back in February, we alerted our newsletter readers that a market pullback could create prime buying opportunities in select AI names. Between April 4th–7th, we issued 12 buy alerts across six AI stocks — some of which have since gained over 100% from those lows.
Now, with the S&P 500 fully rebounding from its April 7th bottom — a 21% drop — and hitting new all-time highs, we are growing more cautious. Despite the strength in broader markets, we’re seeing early signs of another topping pattern, which could bring renewed volatility.
Similar to February of this year, we forsee another excellent buying opportunity in the coming weeks. This is one of the areas where we excel at the I/O Fund – we don’t only provide unparalleled analysis on AI stocks, but we back this research up with buy alerts when the risk is low.
Leading AI Stock Nvidia Will Lose Market Share – but it Won’t Matter
Two weeks ago, in the analysis “AMD vs Nvidia: The AI Stock That Could Win by 2028,” I covered how the AI training market is where Nvidia’s strengths are nearly insurmountable as the leader in combining parallel processing (CUDA) cores with matrix computations (Tensor Cores). Over the past few years, Nvidia has increased compute power by an order of magnitude to the point of defying Moore’s Law with architectural changes such as tensor cores and lower precision floating points.
As a reminder, training is the process of a model learning patterns from labeled data through internal parameters (called weights). There is forward and backward pass or propagation for updating the parameters. This phase is computationally intensive, requiring significant memory and parallel processing power.
You can read more about the history of Nvidia’s GPU architectures including Blackwell in the analysis: “Here’s Why Nvidia Stock Will Reach $10 Trillion Market Cap.
There’s no point in custom silicon or AMD trying to compete with Nvidia’s lead in training. Instead, Nvidia’s monopoly in AI accelerators will see a loosening of its grip as a new market begins to take off — the AI inference market.
As discussed in my recent analysis, inference takes batches of real-world data and quickly comes back with an answer or prediction — therefore, this stage needs low latency (or speed) over raw compute power. For example, inference will take a trained model and produce a probable match for new data in milliseconds. While it can be compute-intensive for large models like GPT-4, inference generally prioritizes low latency, higher efficiency, and lower cost.
In many applications, it makes sense to run inference at the edge (closer to where data is generated). However, cloud inference is still widely used for models that are too large or resource-demanding to deploy on local devices. Compared to training, inference requires only the forward pass through the model, making it more efficient in terms of power and hardware demands.
Nvidia will continue to be the leader, yet the 92% market share the GPU-leader commands today will erode over the next few years as inference is an easier market for a few select, strong competitors to rival Nvidia.
However, this part is important: Nvidia does not need a monopoly at 92% on AI accelerators to extend its stock gains. The company has an outsized opportunity with AI software including autonomous vehicles. Last month, I was in New York and visited Charles Payne live in-studio to discuss why the most shocking moment for Nvidia is still ahead.
Why AI Stocks Could Soar: The $255 Billion Inference Opportunity Starts Now
Token usage is exploding, which is a key metric that helps to illustrate the sudden, rapid growth of the inference market for stock investors.
In the most recent earnings report, Microsoft reported 5X YoY growth to 100 trillion tokens whereas Alphabet reported 9X growth to 480 trillion tokens. OpenAI also announced in June they had crossed $10 billion in ARR, nearly doubling from $5.5 billion at the end of 2024. Anthropic’s ARR rose 200% in five months and 50% in 2 months to $3 billion.
Last week, I spoke with Charles Payne about the $255 billion opportunity in this market and how it’s the sudden burst of activity from $0 to $255 billion that makes it especially attractive to investors.
You can read more on why the inference market is heating up the Nvidia versus AMD stock debate, which I predict will have an ending few stock investors are prepared for.
Big Tech Operating Margins Will Offset Capex; But the Growth Story Will Lag
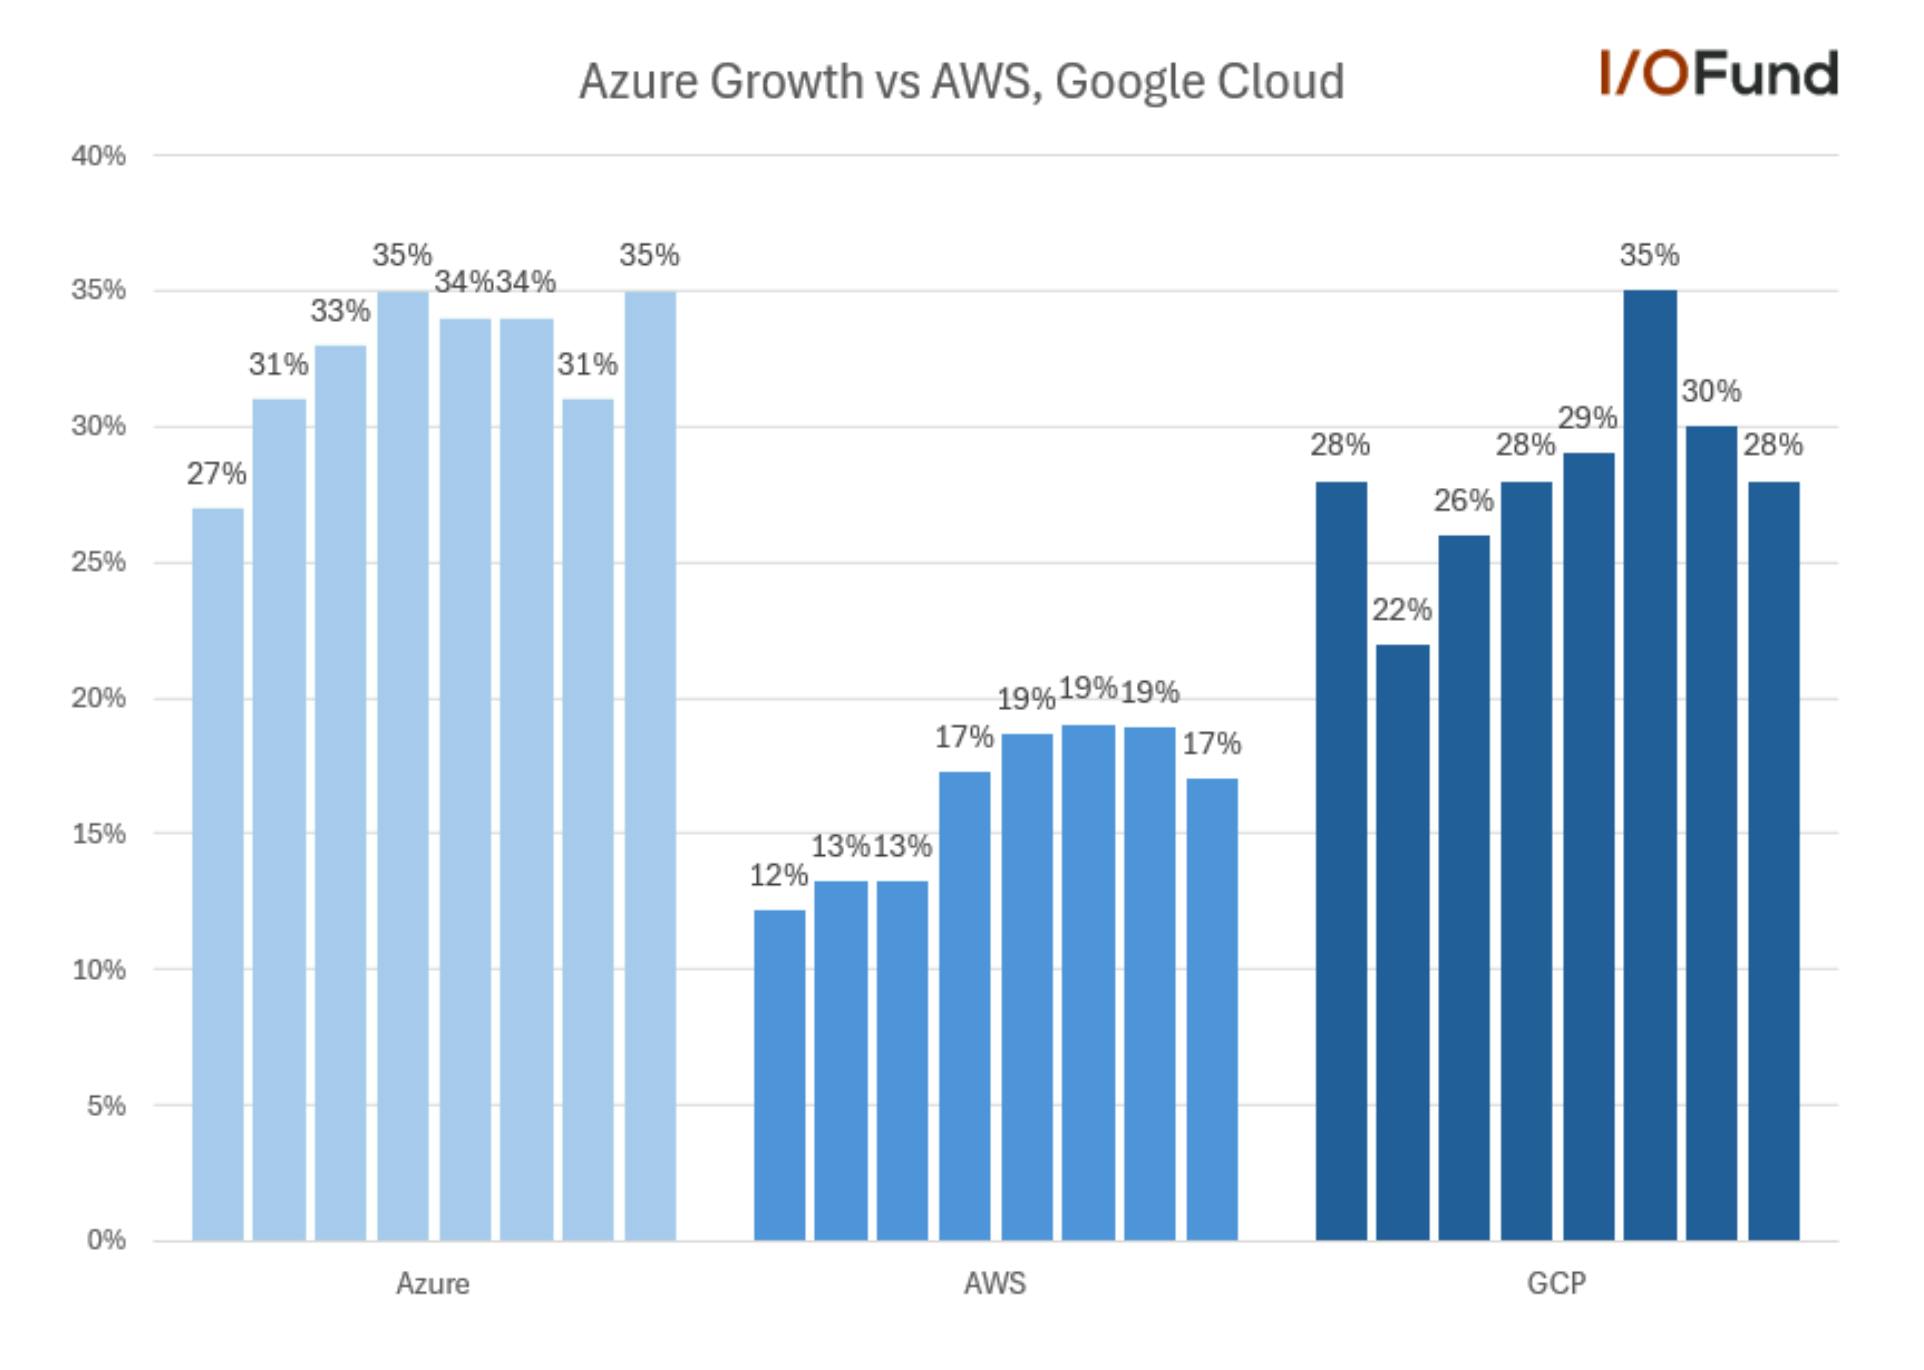
Microsoft stood out this past earnings season due to Azure being the only cloud provider of the three platforms to see growth accelerate last quarter. Not only did Azure separate itself with this 4-point sequential growth acceleration, but it also grew at more than 2x the rate of AWS and 7 points faster than Google Cloud, reaffirming the company’s momentum in the Azure vs AWS vs Google Cloud battle.
Despite lumpy Azure growth, our firm has been quite clear we foresaw Microsoft being the top winner in AI.
Over the longer-term, Azure is expected to outperform both AWS and GCP through 2026, according to estimates from UBS. For 2025, Microsoft Azure growth is projected at 28.6% YoY to $83.3 billion, outpacing both AWS at 16.8% and Google Cloud at 25.3%, according to UBS. UBS also forecasts Azure to maintain a 28% growth rate in 2026 to $106.7 billion in revenue, whereas GCP is forecast to decelerate to 22% and AWS to >16% YoY.
Margins are likely to improve, however, even for those companies that are not seeing growth accelerate from AI just yet. Big Tech companies such as Microsoft announced an additional 9,000 layoffs this week for a total of 16,000 this year. Amazon announced in March plans to lay off 14,000 managerial roles for a total of 18,000 layoffs this year with Alphabet at 12,000 layoffs this year.
Although it’s common for Big Tech to have layoffs given the sheer size of their global workforces, the YTD layoffs amount to the yearly layoff numbers (roughly) with half of the year left to go.
Additionally, Meta’s CEO has openly stated their goal is to replace developers with AI in 2025, stating in the last earnings report: “So I’d say it’s basically still on track for something around a mid-level engineer kind of starting to become possible sometime this year, scaling into next year. So I’d expect that by the middle to end of next year, AI coding agents are going to be doing a substantial part of AI research and development. So we’re focused on that.”
I suspect Big Tech is already seeing massive productivity gains internally, which is why the bottom line continues to expand. For Big Tech, EPS growth is outpacing revenue growth. This can be achieved by using AI to replace engineers, sales and marketing, and HR departments, for example. The first companies to replace humans with AI will naturally be the Mag 7 as they are far ahead in the AI race compared to enterprise companies.
Don’t Snooze; Nvidia’s Blackwell is Coming
Nvidia has struggled to breakout and meaningfully hold all-time highs and the market is now snoozing on the stock. Our firm was early to warn investors that Nvidia was topping stating the I/O Fund was not buying Nvidia in October and offering additional analysis in early January that Nvidia’s stock was topping with a setup that pointed toward getting Nvidia at $101, $90 or $78.


