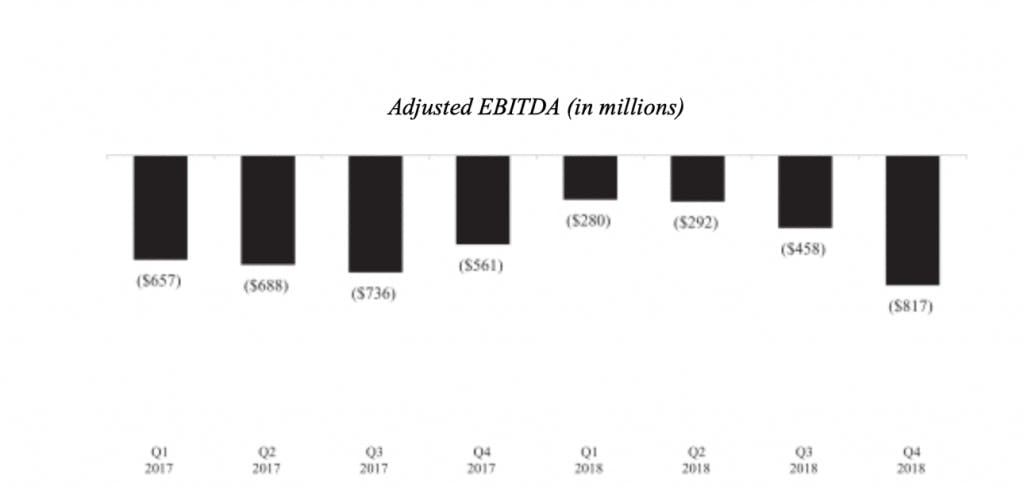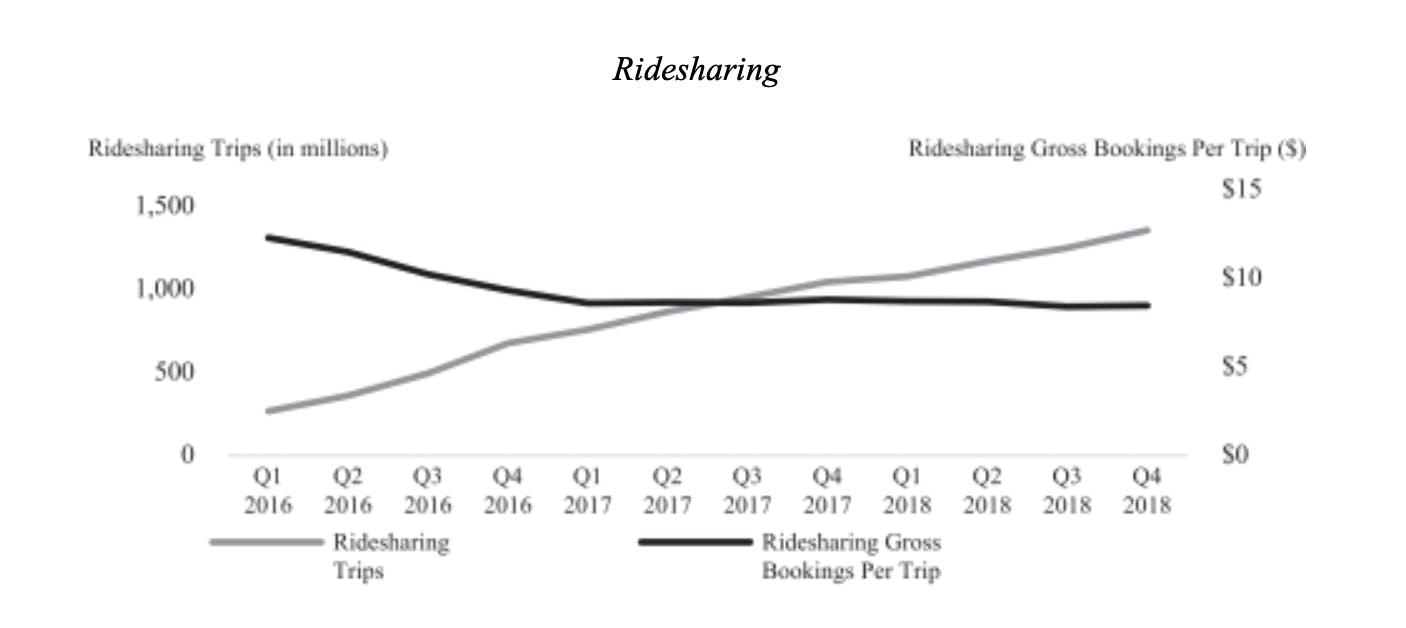

By now, investors know that Lyft’s ride-sharing IPO didn’t reach $100 per share like many of the media talking heads stated it would, and this will likely weigh on Uber’s IPO. Two weeks prior to Lyft’s IPO, I had warned that the risk listed in the prospectus, which warned Lyft may not become profitable, was more than fine print. Ride-sharing companies use investment money to lower the cost of the ride to create demand, which means the ride you take in a Lyft or Uber is not profitable, and will likely never be profitable.
Not one analyst rated Lyft as a sell going into earnings despite earnings estimates that called for accelerating net losses from negative $3.16 EPS to negative $3.97 EPS. Going into earnings this week, twelve analysts had rated Lyft as a buy compared to eight who rated it as a hold (What is wrong with these analysts?!).
With the most recent earnings, we have confirmation that my analysis, which detailed why Lyft can increase revenue yet cannot stop the losses, was accurate with expectations of an estimated $1.1 billion in losses this year.
Reuters published in 2015 that Uber passengers pay only 41 percent of the actual cost of their trips. At the time, Reuters warned that this creates an “artificial signal about the size of the market” when Uber released limited financial data that showed losses of $708 million per quarter. Four years later, little has changed.
How Uber’s IPO Compares to other IPOs:
Uber is an IPO that has been covered extensively. You may have heard comparisons of Uber’s IPO to Facebook or Alibaba. Uber is raising $9 billion in this week’s IPO, Facebook raised $16 billion in 2012 and Alibaba raised $25 billion in 2014. Facebook and Alibaba are both doing great, seems to be the logic OR many tech companies are not profitable at the time of IPO is another costly mistake when comparing Uber to other IPOs.
Of course, these “big tech” comparisons don’t tell the whole story. Facebook had $1.75 billion in operating income, and $1 billion in net income in the year prior to the 2012 IPO. Alibaba had $1.7 billion in operating income, $1.3 billion in net income, and $2.6 billion in adjusted EBITDA in 2013, the year prior to its IPO. To compare, Uber has a $3 billion operating loss, and negative $1.8 billion adjusted EBITDA.
Notably, for anyone glancing over the prospectus, Uber sold some operations in Russia and Asia, which provided one-time income, and caused the company to post $1 billion in net income. This is why net income should be ignored as it does not reflect the operating income or adjusted EBITDA. To summarize, Uber’s prospectus points towards “an accumulated deficit of $7.8 billion” in the years ending December 31, 2017 and 2018. The year prior (2017), Uber posted $4 billion in operating loss and negative $2.6 billion in adjusted EBITDA.
Chicken and the Egg – Both Broken:
Most investors know there have been numerous lawsuits against Uber with many examples listed on page 28 of the prospectus. Here is a sample of what it says:
“We are involved in numerous legal proceedings globally, including putative class and collective class action lawsuits, demands for arbitration, charges and claims before administrative agencies, and investigations or audits by labor, social security, and tax authorities that claim that Drivers should be treated as our employees (or as workers or quasi-employees where those statuses exist), rather than as independent contractors.”
This paragraph is followed by a list of class action lawsuits and state-level Supreme Court rulings that Uber has been involved with and the various legislation or judicial decisions that could have an adverse effect on the business and financial condition of the company.
Although being sued often comes with the territory for disruptive startups, this is unique as the work force is going on strike during the IPO (this is not a competitor suing over intellectual property, etc). The drivers and customers are a chicken-and-egg scenario and Uber struggles to pacify both to successfully operate. On one hand, Uber is subsidizing rides at up to 60% to lure the customers, and on the other hand, the workers are retaliating. This is not a good formula. Most importantly, Uber has no profit to absorb a change in business model, such as being required to pay minimum wages or health care.
Here are some charts:
If you need some charts, to prove what I’m saying, there is an overabundance of charts that show the issues Uber has with subsidizing rides “to create artificial signals about the market” (Reuters words, not mine).
Core platform is the margin Uber generates after direct expenses. As the prospectus states, “Core Platform Contribution Margin is a useful indicator of the economics of our Core Platform, as it does not include unallocated research and development and general and administrative expenses.” Here is what the margins look like:
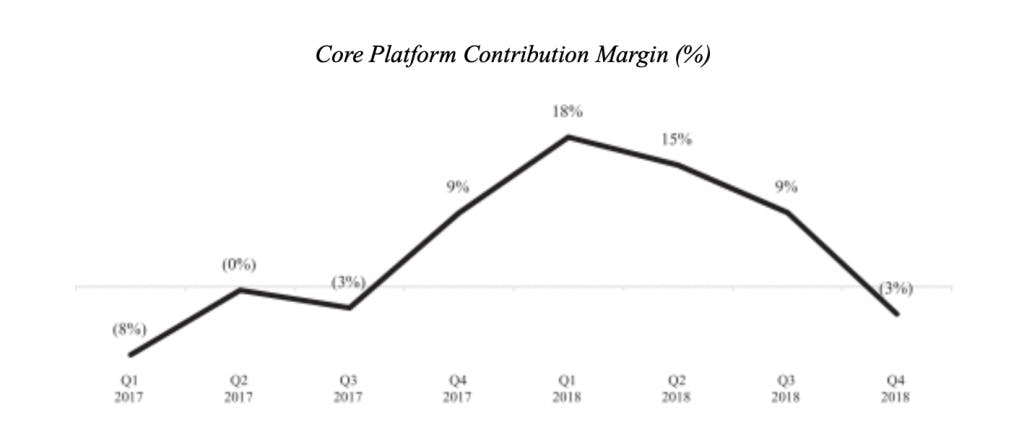
The reasons Uber states the Core Platform Contribution Margin goes through periods of decline is due to competition in ridesharing (translation: Uber has to subsidize rides to remain competitive) and they also state it’s due to planned investments in Uber Eats. The problem is that Uber Eats only contributed $165 million in adjusted net revenue last quarter compared to ride sharing at $2.3 billion in adjusted net revenue, and therefore, the majority of the decline is likely due to the issues I stated above (rides are priced too low for profits but price of rides must remain low for demand).