
This article was originally published on Forbes on Apr 28, 2022,10:45pm EDT
If an investor were to believe market price action this week, it would appear Facebook had strong earnings while Alphabet stumbled. Yet, the opposite is true. Primarily, it was strength in retail ads that led to Alphabet reporting healthy growth of 23%. Meanwhile, Meta Platforms (Facebook) reported revenue growth of 9.7% and is guiding for roughly 0% growth from $28.5 billion in Q2 2021 to $29 billion, at the midpoint for Q2 2022. This analysis looks at why Alphabet is able to provide higher revenue guidance despite 80% of its revenue coming from ads while Facebook is guiding for flat growth.
Notably, Q2 is particularly hard because there are three heavy macro headwinds: supply chain issues, Ukraine-Russia situation, and the transition that Apple has forced with changes to attribution and measurement on iOS. When you add the one-time event of Covid, which plummeted ad spend in Q2 2020, only to lead to a surge in ad spend the following year Q2 2021, the hurdle to clear for revenue growth is at a historic high. We believe those ad-tech stocks that can show top line growth right now are providing important clues for when macro headwinds clear.
BACKGROUND:
The ad-tech industry remains in a whirlwind of changes following iOS privacy changes that limit third-party tracking on Apple mobile devices. I am hyper focused on identifying who the winners and losers will be following these changes, as it will determine who will lead ad-tech going forward. This issue is important because it impacts leading FAANG ad-tech companies, such as Facebook (Meta) and Google (Alphabet). Wall Street particularly likes ad-tech’s bottom line, and will aptly reward those stocks that can capture more ad spend.
In the below analysis, I review Google’s Q1 2022 results and focus on its ad platform (I am ignoring Google Cloud for now) and look for hints if Google is being impacted by the recent iOS changes. You’ll find that Google has held up well relative to other app-based advertising platforms, such as Facebook, following the changes to third-party identifiers. This is because Google has a first-party data advantage, which is critical during a time that attribution and measurement is limited by third parties. I explain why in more detail below.
Google’s Q1 Ad Growth Remains In-Line
While the market is still digesting the macro headwinds previously mentioned – supply chain and Ukraine-Russia; the third headwind of attribution and measurement changes is the headwind that investors should pay most attention to as it leads to a material change in story for ad-tech companies. Meanwhile, the other two headwinds will resolve in time.
Q1 earnings are provide valuable data of who is most and least impacted. Two critical data points will be Facebook’s and Google’s Q1 results, as most of their sales come from mobile ads. Google recently reported that sales grew 23% YoY to $68 billion, which were in-line with estimates. Furthermore, Google’s Search business slightly outperformed and grew 24% YoY to $40 billion. This follows the outperformance in Q4 as Search sales grew 36% YoY in Q4 while total Q4 sales grew 32% on a year-over-year basis. It may appear that Alphabet’s search revenue is slowing from 30% in the year-ago quarter, but the deceleration in search revenue is due to the tough comps, and relative to Facebook, is outperforming.
The strength in Search highlights the advantage that having first-party data provides. This is because Search is primarily done on a browser, allowing Google to capture valuable first party data from ownership of Google Chrome, Google Search and also from Android OS. Moreover, Google is releasing new products, such as Topics API, which enables behavioral targeting. This is a direct shot at Meta Platforms, who is known to be quite competitive on behavioral targeting through taxonomies.
Sign up for I/O Fund's free newsletter with gains of up to 403% - Click hereSign up for I/O Fund's free newsletter with gains of up to 403% - Click hereClick here
However, while Search remained strong, both YouTube and Google Network sales underperformed during the quarter. For instance, YouTube grew sales just 14% YoY to $7 billion, a steep slowdown from the 25% and 49% YoY growth rates from last quarter in Q4 and Q1 2021, respectively. Google Network sales increased 20% YoY to $8 billion. This also represented a deacceleration from the 26% YoY growth rate in the prior quarter.
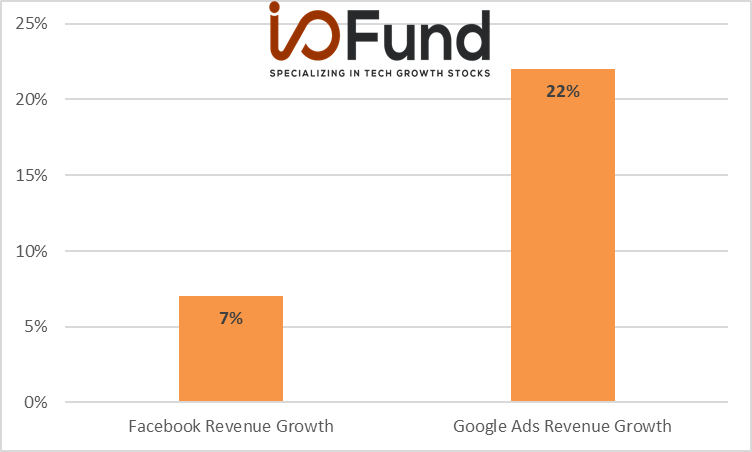
In aggregate, total ad sales increased 22% YoY to $55 billion, a deacceleration from the 33% YoY growth rate in the prior quarter. It is notable that despite the headwinds in YouTube and Google Network, Google’s sales vastly outpaced Facebook’s Q1 revenue growth. As shown below, Google’s ad sales grew nearly 3x faster than Facebook’s 7% growth.
I/O Fund
I believe this outperformance was driven by Google’s first-party data advantage. Moreover, YouTube revenue was the biggest laggard during the quarter and YouTube sales grew 14% YoY to $7 billion during the last three-months (fun fact: YouTube is larger than Google Cloud). The slowdown in YouTube may suggest that ads have been impacted by iOS changes, but its important to consider that YouTube grew sales 49% YoY in the year-ago quarter, leading to a tougher comparable base period.


