
Broadcom stock joined Nvidia, Alphabet and Microsoft in calling out surging AI inference demand, noting that this rapid growth could drive increased demand for custom silicon in the second half of 2026, and with it, higher AI revenue.
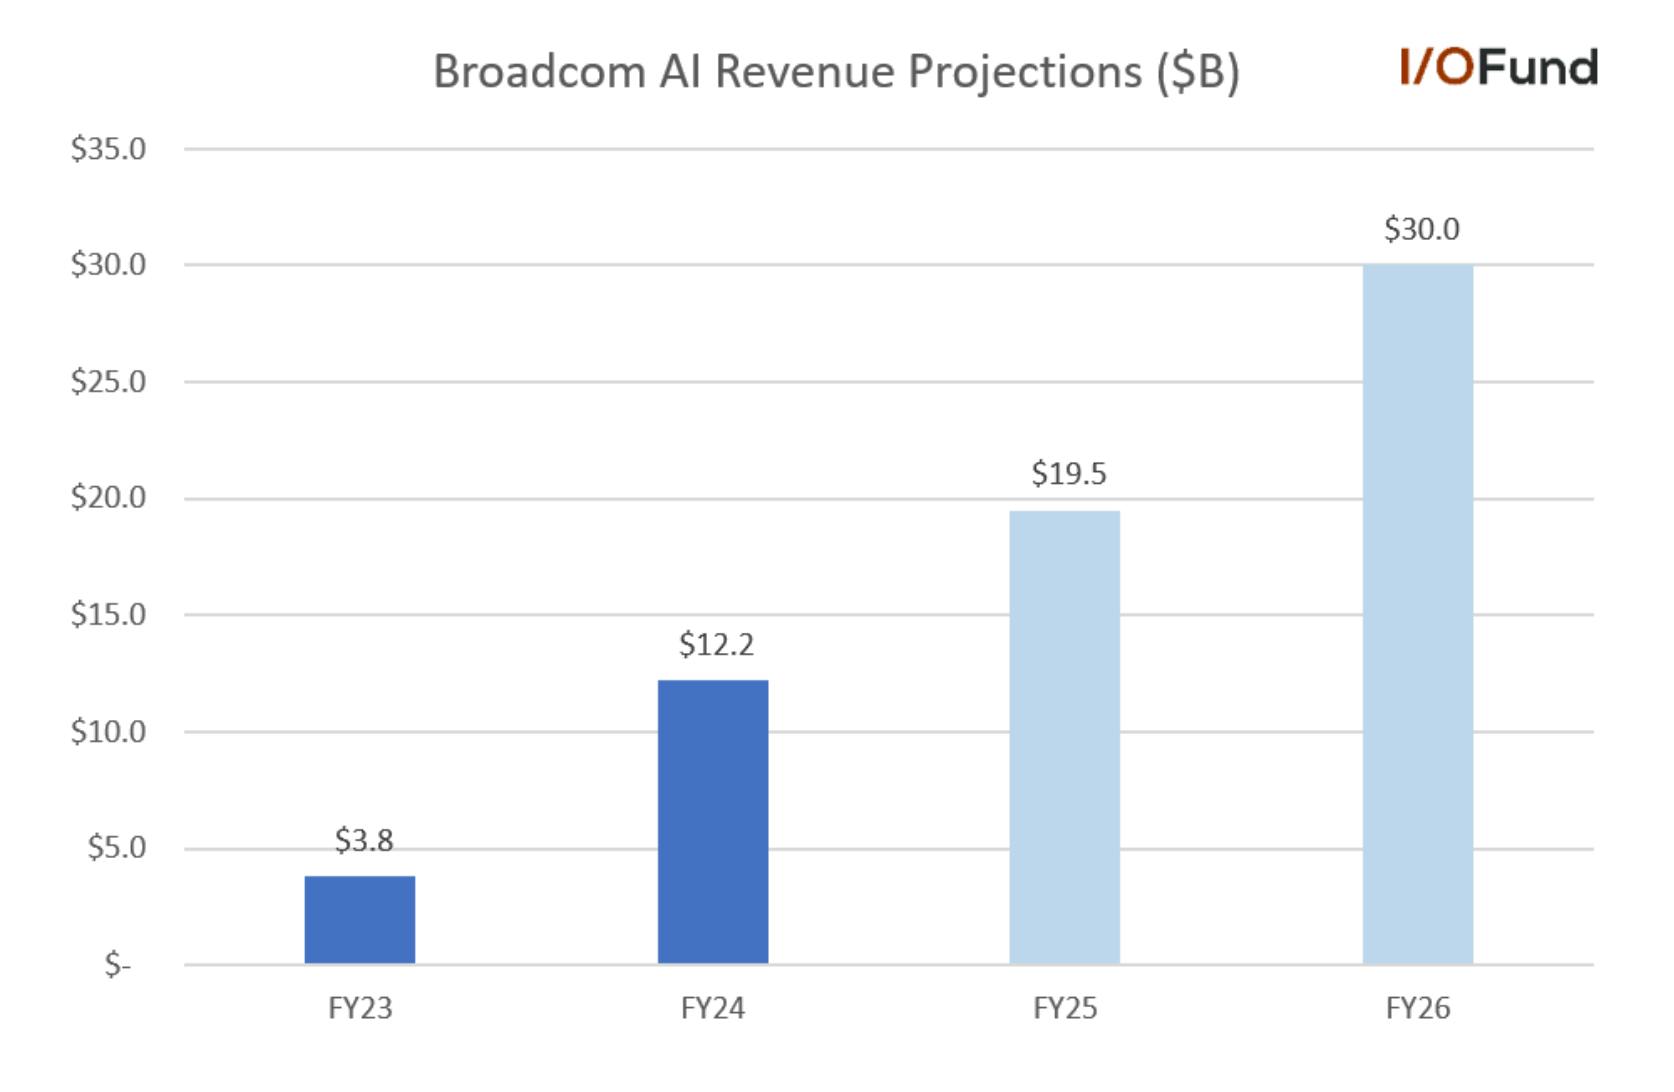
Despite an in-line print and guide, Broadcom’s AI revenue is tracking above Street estimates for next year towards the $30 billion mark, up nearly 150% in two years, with growing tailwinds from inference and networking as clusters increase in size. AI revenue growth is also tracking Broadcom’s addressable market forecast of a 60% CAGR.
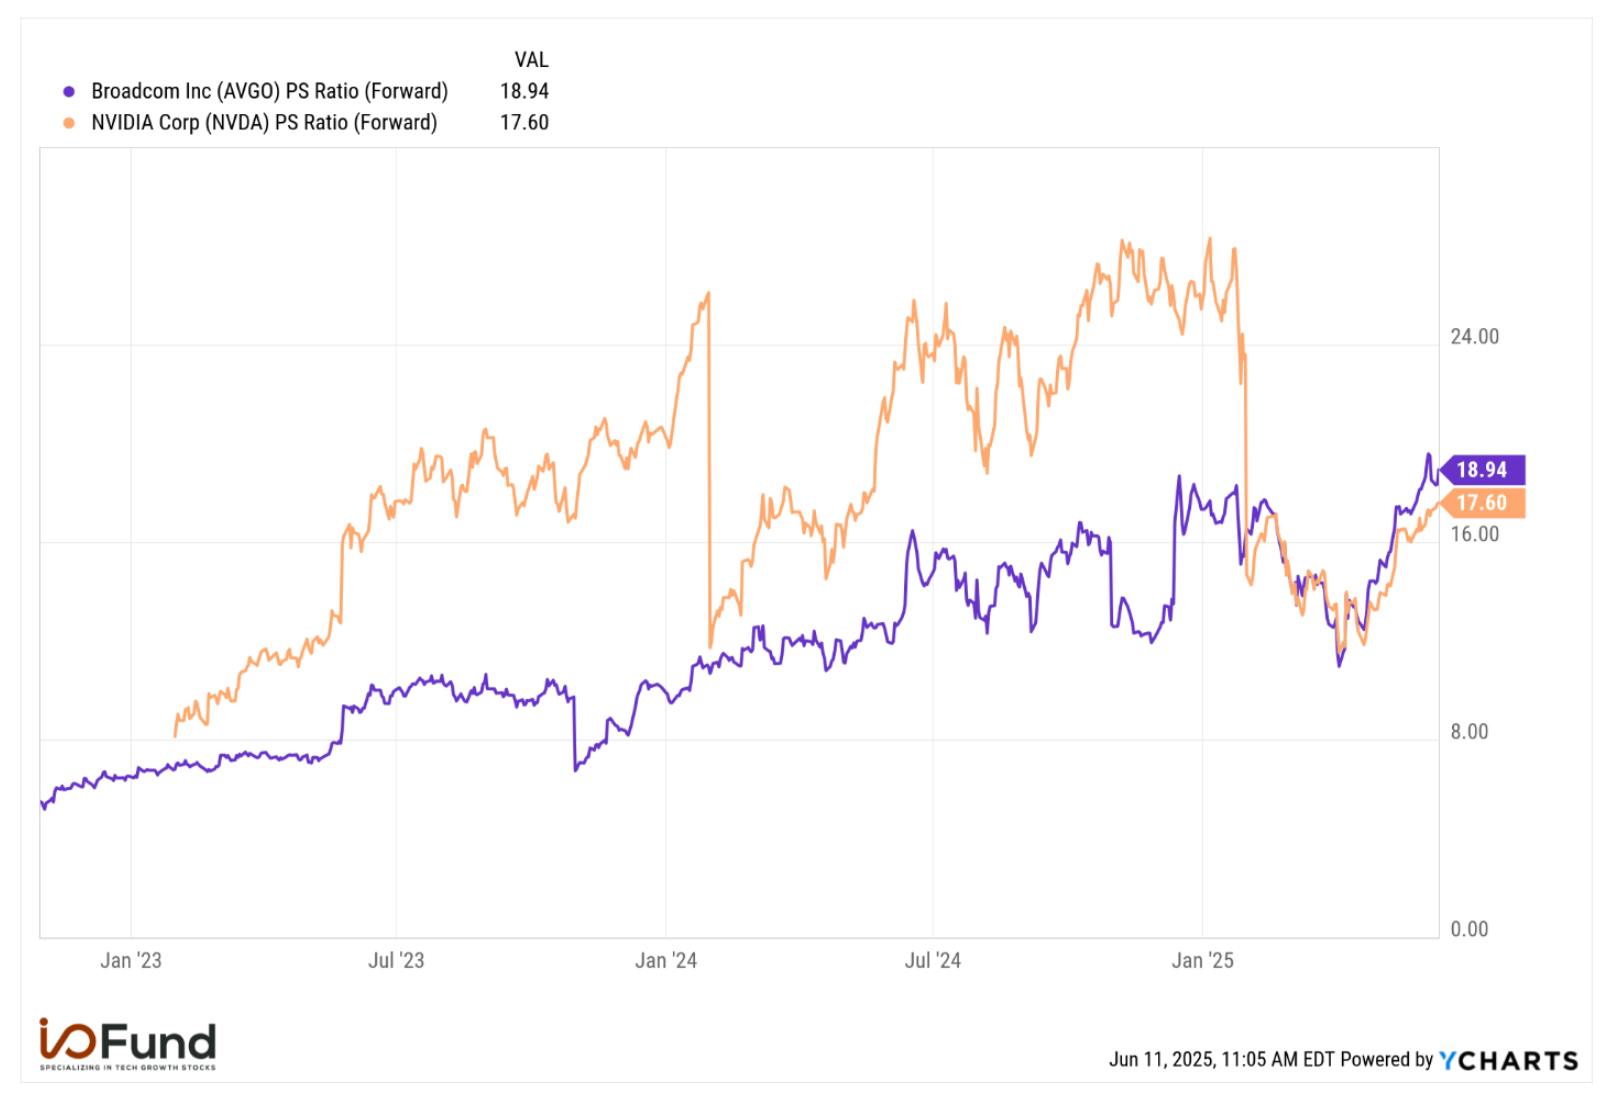
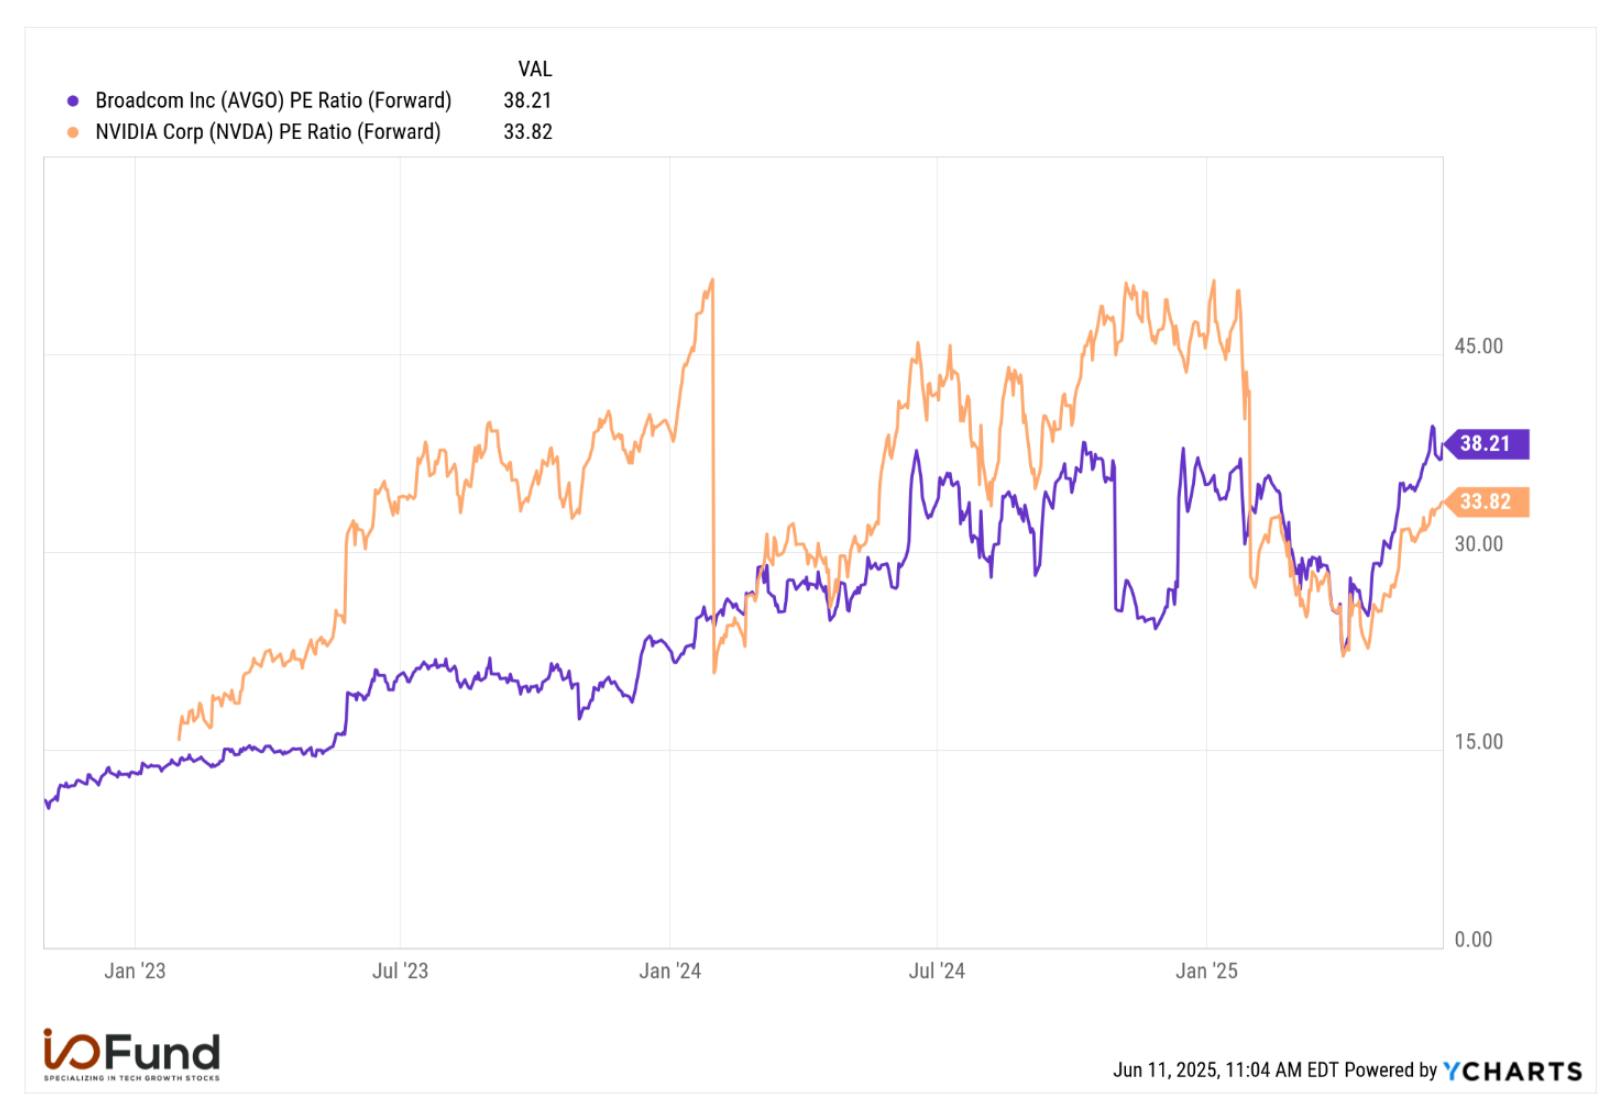
Broadcom is cementing itself as the clear second in AI with key ingredients for success as inference demand rises. However, its premium valuation to Nvidia looks to be pricing in above-expected AI revenue growth into 2027, likely closer to a 70%+ CAGR, as there exists a $160 billion gap in AI-driven revenue between the two.
Inference Driving Possible Acceleration into 2H 26
The AI ecosystem’s pivot from training to inference, now emerging as a strong revenue engine for hyperscalers, is a structural tailwind for Broadcom’s custom silicon and networking products.
We’ve seen quite a handful of signs over the last couple of months that inference demand (and revenues) are beginning to explode:
- Microsoft reported 5x YoY growth in tokens processed to 100T in Q1, with AI contributing 16 points or nearly half of Azure’s 33% growth last quarter. Microsoft’s AI run rate at the end of January was $13 billion, up more than 175% YoY.
- Alphabet reported 9x YoY growth to 480T tokens processed in April.
- OpenAI this week announced that it had crossed $10 billion in ARR, nearly doubling from $5.5 billion at the end of 2024.
- Anthropic’s ARR rose 200% in five months and 50% in 2 months to $3 billion.
With hundreds of millions of users interacting frequently with AI assistants, inference becomes the focal point for providers such as OpenAI and Google. Meeting these levels of growing demand, without significant response delays or downtime, requires more and more accelerators, networking and interconnect products.
Broadcom’s edge goes beyond the fact that custom accelerators are often multiples cheaper than Nvidia’s GPUs for inference tasks – it’s that custom silicon is increasingly performant with each generation. By optimizing algorithms (software), Big Tech can drive higher performance from large language models (LLMs) — which helps to drive down costs while also increasing output for specific workloads. For example, a rough idea as to how much it costs Nvidia to make merchant GPUs is estimated around $3,000 to $5,000 whereas the company charges $25,000 to $30,000 – hence the AI leader’s excellent margins. Reducing Nvidia’s high pricing power is what Big Tech is after and this can be accomplished both in the hardware costs but also through optimizing the workloads for specific use cases.
Big Tech is prominent in Broadcom’s custom silicon customer list, which includes Google and Meta. ByteDance reportedly emerged as the third customer last summer, though some reports surfaced earlier this year that this project could be cancelled. OpenAI and Apple are also heavily rumored to be prospective customers.
Why Big Tech Is Chasing Cheaper Inference
For the providers in the AI ecosystem, monetizing GPUs depends on inference, and thus revenue becomes a function of GPUs and tokens and profits become a function of cost. Nvidia’s Blackwell offers a massive leap in performance and can train models such as Meta’s Llama 3.1 405B in as little as 27 minutes, yet the cost advantages offered by custom silicon can translate into higher margins in the long run from lower inference serving costs.
For example, Google recently announced that its upcoming seventh-gen TPU Ironwood is its “most performant and scalable custom AI accelerator to date, and the first designed specifically for inference.” Ironwood comes in two sizes, a 256 and a 9,216 chip configuration, with the larger size offering up to 42.5 exaflops of performance.
Google adds that Ironwood offers 2x the performance per watt as last-year’s generation Trillium, with 6x more HBM and 4.5x the HBM bandwidth. This allows it to deliver more capacity per watt at a time when power is a primary constraint, and provide customers with more cost-effective AI workloads.
This is exactly what Broadcom sees arising from this inference growth curve, as CEO Hock Tan asserted that the company has quite a bit of visibility into “increased deployment of XPUs next year, much more than we originally thought and hand-in-hand with it, of course, more and more networking.” The necessity of networking in larger clusters means demand is likely to remain robust even given custom silicon will not keep pace with Nvidia’s merchant sales into the hundreds of billions.
Higher-than-expected deployments of custom silicon combined with strong demand for networking should provide robust tailwinds for AI revenue growth beyond 2026. Broadcom currently has enough visibility to place possible demand acceleration for 2H 2026 on the table, and this could easily persist through 2027 and beyond should inference demand flourish and as the path to 1 million accelerator clusters materializes.
Assuming Broadcom can maintain another 60% YoY growth in FY27 on stronger demand and potential conversion of its 4 current prospects, AI revenue would close in on $50 billion, or up to 60% share of revenue. Even if growth then slows to 30% YoY in FY28, Broadcom would still be more than doubling its AI revenue to $65 billion in just three years.
Broadcom Reports 170% YoY Growth in AI Networking
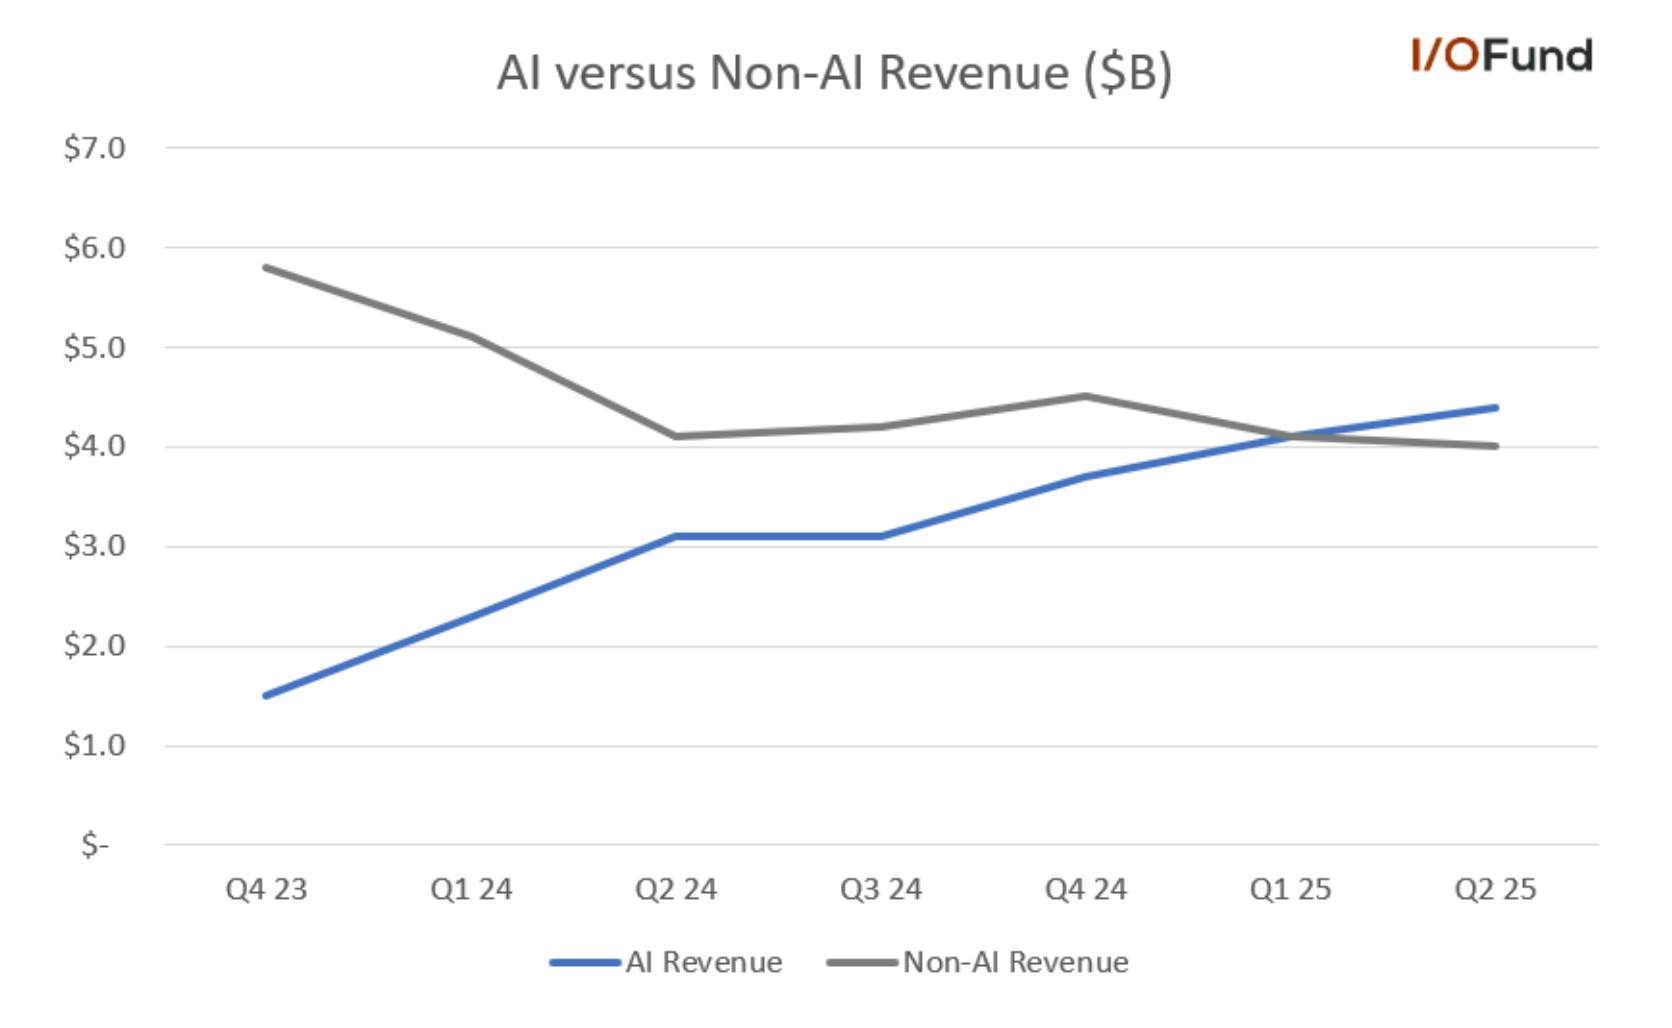
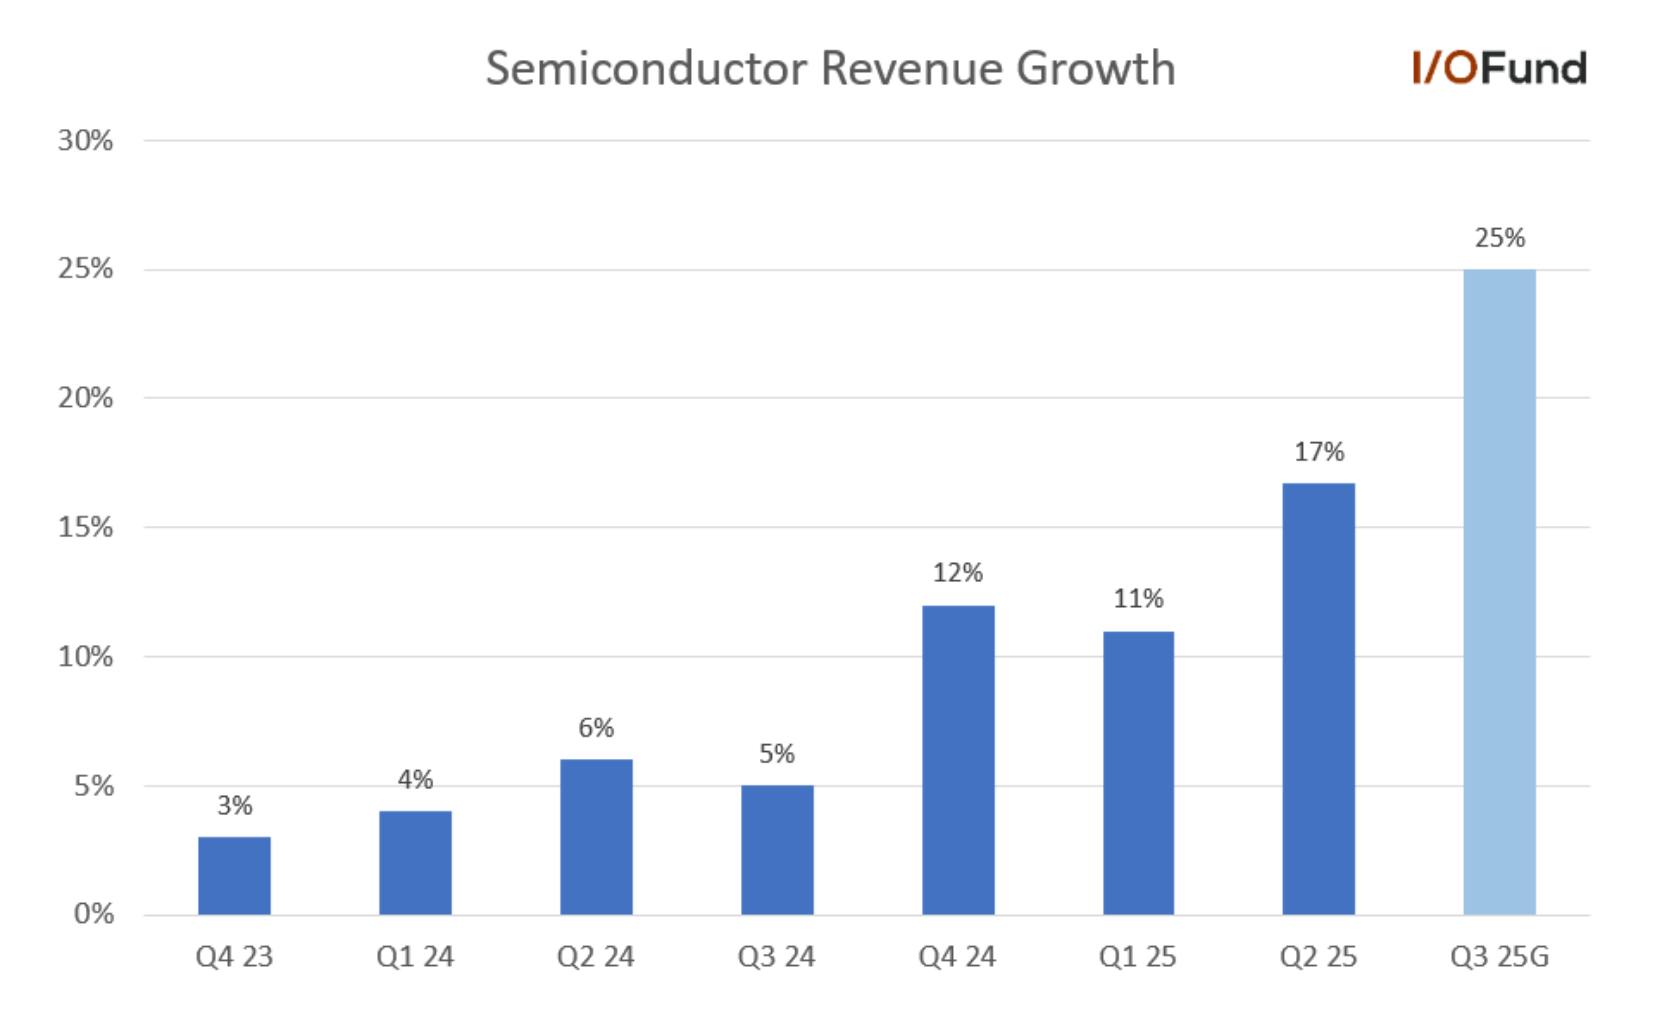
Broadcom has cemented itself in second place in AI revenue as it closes in on $20 billion this fiscal year in AI revenue — with a line of sight toward $30 billion by the end of fiscal 2026. AI revenue accounted for more than 50% of Semiconductor revenue for two quarters in a row and nearly 32% of total revenue in Q2.
AI semiconductor revenue rose 46% YoY to $4.4 billion, in line with management’s guidance. Although this was a deceleration from 77% YoY growth in Q1, Broadcom forecast $5.1 billion in AI revenue in Q3, pointing to a rebound to 60% YoY growth – marking ten consecutive quarters of growth.
In the current quarter, the 46% AI semiconductor growth was driven by networking, which was up 170% YoY and represented 40% of AI revenue. In the opening remarks, the CEO stated the following regarding this outsized growth: “As a standard-based open protocol, Ethernet enables one single fabric for both scale out and scale up and remains the preferred choice by our hyperscale customers. Our networking portfolio of Tomahawk switches, Jericho routers and NICs is what’s driving our success within AI clusters in hyperscalers.”
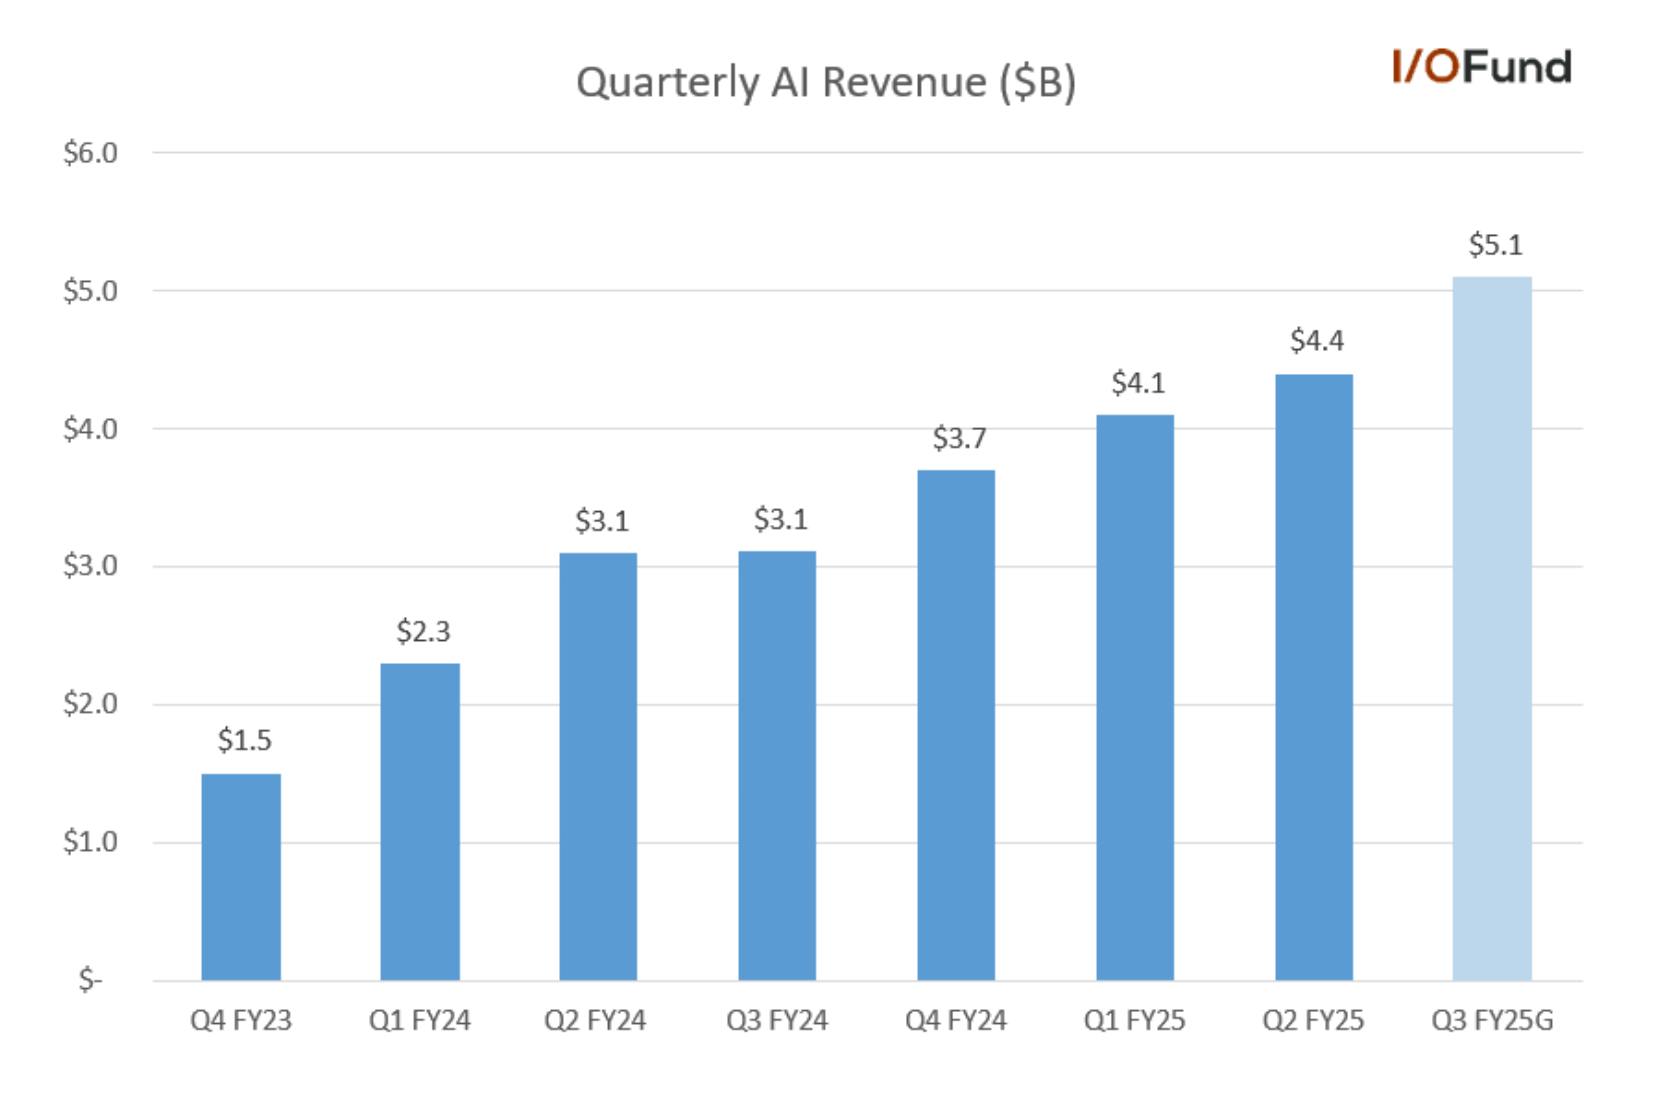
Q3’s guidance was ahead of some analyst expectations for $4.9 billion in AI revenue in the quarter, ticking higher as Google’s TPU v7p (Ironwood) begins to ramp. Q3 would also mark the largest sequential growth in over a year on a dollar basis, at ~$700 million.
Additionally, analysts look to already be penciling in further strength in Q4, with Bernstein’s Stacy Rasgon suggesting that Broadcom could be eyeing $5.8 billion in AI revenue in Q4 assuming it sustains 60% YoY growth. Given that Broadcom’s 1H revenue was up more than 57% YoY, this seems a reasonable assumption, especially considering management is eyeing near 60% growth in FY26.
More importantly, AI’s strength is masking persisting softness in non-AI revenue, which could continue to be pressured due to Broadcom’s high consumer exposure. Broadcom noted that non-AI revenue “is close to the bottom” but it “has been relatively slow to recover” with revenue down (5%) YoY to $4 billion in Q2.