
This article was originally published on Forbes on Nov 12, 2020,09:01pm ESTForbes on Nov 12, 2020,09:01pm EST
Roku
Roku reported Q3 earnings on November 5th. The 73% year-over-year revenue growth the company announced was 23% above consensus expectations. Gross profit rose 81% YoY while gross margin rose 216 basis points in total to 47.6%.
Roku added 2.9M active accounts in the quarter (+43% YoY). Total streaming hours increased by 0.2 billion hours over the last quarter to 14.8B (+54% YoY), while ARPU grew 20% YoY to $27.
Roku was a beneficiary of the rebound in ad spend, as the company saw Q3 monetized video ad impressions grow 90% YoY vs. 50% YoY growth last quarter. Roku is anticipating that Q4 revenue growth will likely be in the mid-40% range, similar to the growth rate seen in the last few holiday seasons. Per the earnings call, the company is being cautious about holiday spending with this forecasted guidance.
ROKU shares briefly hit all-time highs immediately following the announcement of these results.
Brands like DraftKings are shifting budgets especially as TV sports have been canceled and delayed. Roku also pointed towards CPG brands as a large driver for ad revenue in the current quarter.
We have got brands like DraftKings, for example, who is a big sports spender, had to shift budgets out of TV as sports were canceled and delayed. Has moved a significant portion of their budget into OTT.
In the earnings call, management felt confident the migration from linear TV would be a long-lasting trend after COVID.
We are not going back to the way it was to be clear. I mean, I think, COVID did — COVID triggered a lasting durable change in how CMOs and marketers are thinking about their TV ad spend. In Q3, we saw a 17% drop in linear viewing, Roku was up 54%, 92% of Roku cord-cutters are very satisfied with their decision to cut the cord and aren't planning to go back.
So I really think this is a one-way transfer function. We don’t go back to the older spending patterns, because the audience isn’t there, marketers need to follow the audience into OTT. And they stay, they stay because of the enhanced capabilities.
Roku also tackled the question of Wal-Mart and Comcast partnering. The CEO reiterated that Roku is the #1 TV operating system and software operating system in the United States and now Canada with a world-class team of software engineers. He also emphasized that Walmart is a large partner with Roku and has carried many Roku OEMs:
In terms of Walmart, I will just say a few words. I mean, Walmart is a big retailer, a very strong partner of Roku’s. We have a great relationship with them. They sell millions of Roku players a year. They sell millions of Roku TVs for various Roku OEMs, including TCL, Hisense, RCA, Philips, JVC.
We build — we help them build on branded, which is their house brand, Roku TVs, smart TVs, and that’s a business that’s been growing extremely well for them. So, it’s a great partnership and it’s a long-standing partnership, and we have put a lot of work into making sure that it stays strong.
Square
Square announced blowout Q3 results with huge beats on both the top and bottom lines. Non-GAAP EPS of $0.34 beat consensus expectations by $0.18. The company saw revenue grow 140% YoY to $3.03B, beating the consensus estimate by $950M or 46%.
Gross payment volume of $31.7B was 6% above expectations. In total, Square saw gross profit rise 59% YoY, while Cash App gross profit soared 212% YoY.
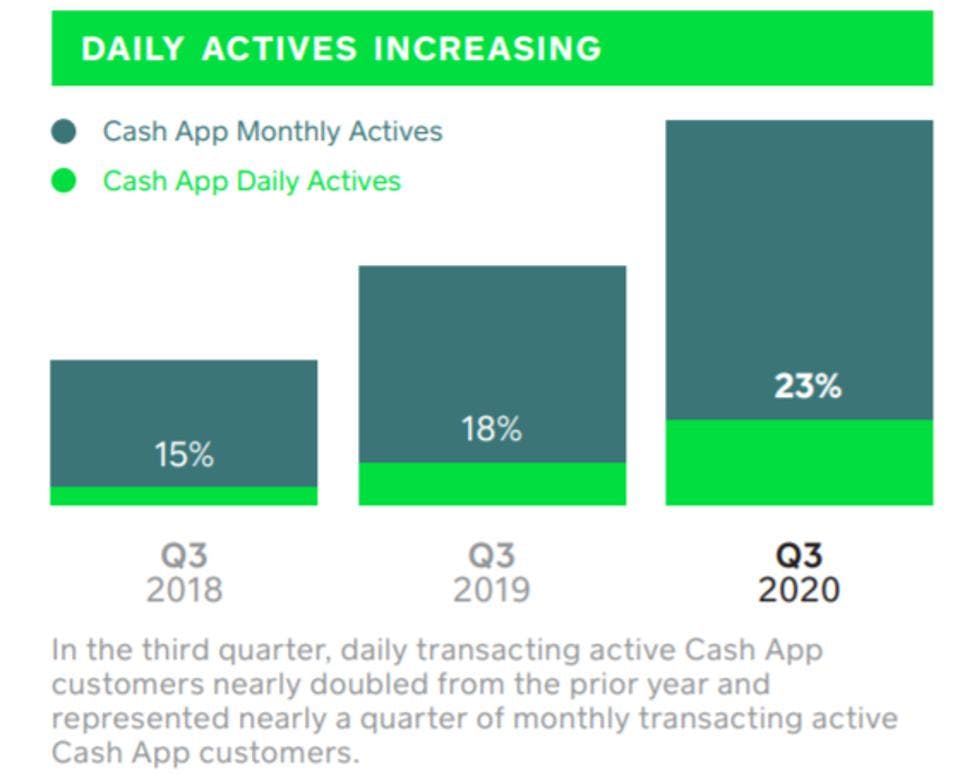
In the quarter, the number of average daily transacting Cash App customers nearly doubled from the same period last year. Square did not provide guidance for Q4, but noted in its shareholder letter that the trends they observed in Q3 remained strong through October.
Sign up for I/O Fund's free newsletter with gains of up to 403% - Click hereSign up for I/O Fund's free newsletter with gains of up to 403% - Click hereClick here
Square’s Seller Ecosystem revenue grew 5% YoY as regions began to reopen. More impressive was the growth of Square’s Cash App Ecosystem, which saw an increase of 23% in daily active users and 574% YoY growth in revenue.
Bitcoin revenue for Square grew 11x last year’s total, but even excluding Bitcoin transactions, Square grew Cash App revenue 174% YoY this quarter. This is an acceleration from the 140% Cash App growth (excluding bitcoin revenue) Square recorded last quarter, and 98% growth previous to that.
Square is focused on expanding Cash App’s utility beyond peer-to-peer payments, CEO Jack Dorsey remarked in the company’s shareholder letter: “We remain focused on increasing daily utility for our Cash App customers to products beyond peer-to-peer payments, which helps drive higher engagement and monetization.”
Square’s investments into increasing Cash App engagement continue to pay off as the company’s Cash App Ecosystem displayed an acceleration in growth across the board this quarter.
BETH.TECHNOLOGY
Jack Dorsey noted that Square is positioned to benefit in both segments moving forward:
“We continue to believe that our Seller and Cash App ecosystems are well-positioned to benefit from the acceleration of secular shifts, such as omnichannel commerce, contactless payments, and digital wallets for consumers.”
The company did not give Q4 guidance due to uncertainties yet did discuss what they have seen so far through Q4. Square's Seller Ecosystem saw a modest acceleration from Q3 in October:
“Seller GPV was up 8% year over year, which improved modestly compared to year-over-year results in the third quarter.”
Cash App has seen a modest decrease in transaction volume in October, which management attributes to the end of government stimulus programs and unemployment benefits:
“Gross profit growth in October moderated compared to the third quarter, driven by a decrease in transaction volume per active customer. We believe this was partly a result of the end of government stimulus programs and unemployment benefits at the end of July, as stored funds in Cash App have decreased since July.”.
The Trade Desk
The Trade Desk announced Q3 results that easily cleared analysts’ expectations. Revenue grew 32% YoY, beating consensus estimates by 19%. Non-GAAP EPS of $1.27 was a big beat on the consensus bottom-line expectation of $0.45. The company noted that it saw Connected TV grow over 100%, Mobile video spend grow 70% and Audio spend grow 70%.
Management issued an upbeat outlook for Q4, expecting $289M in revenue at the midpoint vs. expectations of $255.1M. At the midpoint of this estimate, The Trade Desk is expecting roughly 34% YoY revenue growth in Q4. TTD shares traded over $700 for the first time immediately following the announcement of these results.
Most impressive from TTD’s report was exceeding 100% YoY growth in their Connected TV segment. CEO Jeff Green remarked in the company’s press release that COVID has accelerated advertising innovation across the board:
"So far in 2020, we've seen several years of advertising disruption and innovation compressed into a few months. As a result, advertisers have become more deliberate and data-driven with every advertising dollar."
In the Q3 earnings call, Green talked more about how companies are adapting data-driven measurement strategies for justifying marketing budgets:
“We recently surveyed more than 200 top advertisers, around 85% of them said they are under new pressure from CFOs to justify marketing spend and to measure against business goals.”
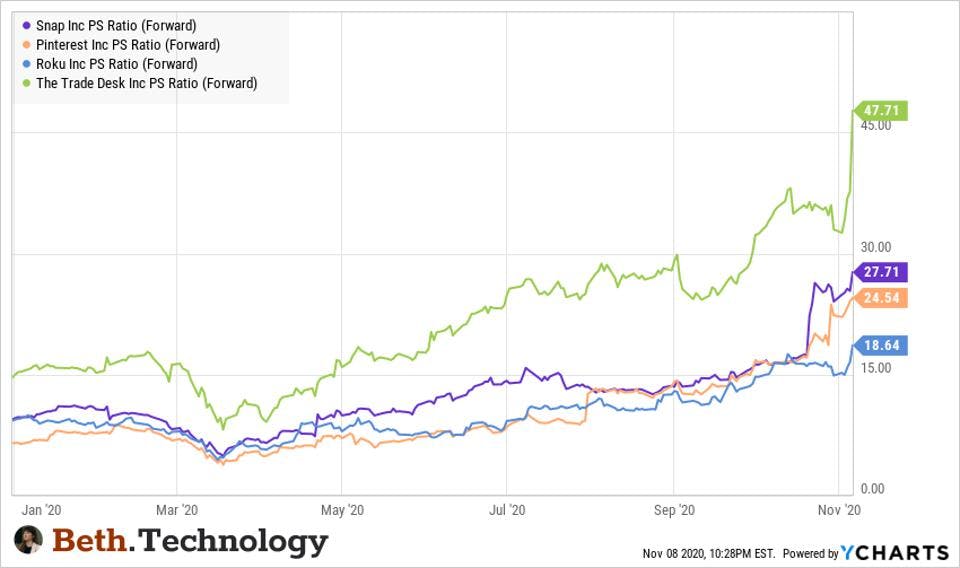
Despite The Trade Desk’s beat, the company did not report the numbers that Snap or Pinterest did (32% growth versus 50-60% growth). TTD’s stock is trading at a valuation that has been historically very hard to sustain in ad-tech.
Rarely, does ad-tech trade over 20 forward price-to-sales even during high-growth periods. Not only is The Trade Desk well exceeding the mean but is trading roughly 200% higher than peers even though Roku, Pinterest and Snap had a better current quarter and are forecasting stronger forward guidance.