
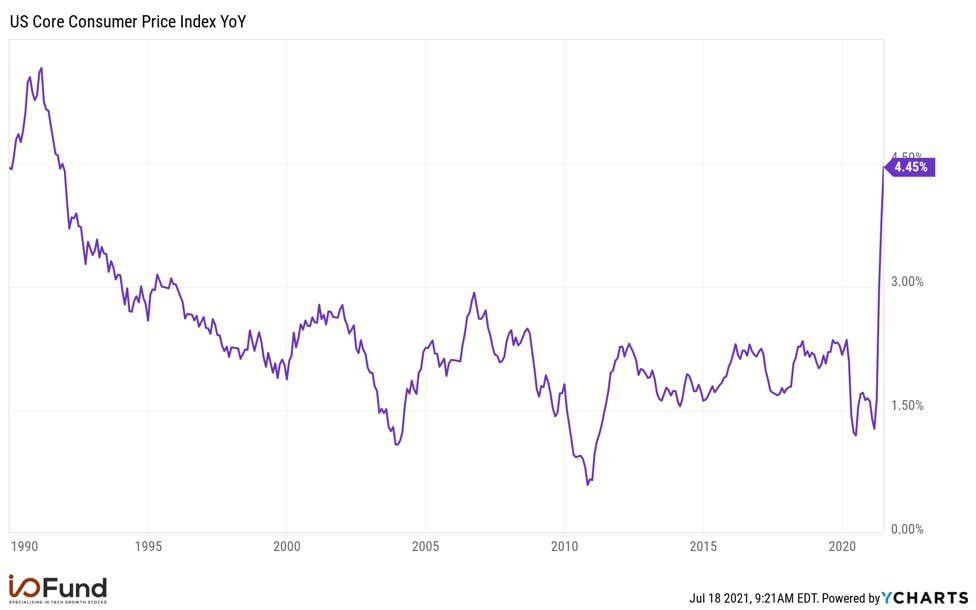
Investors were taken by surprise last week when the US consumer price index rose 5.4% year-over-year in June, the fastest pace seen since August 2008. On a monthly basis, it rose 0.9%. Excluding the volatile food and energy prices, while the Core Consumer Price Index rose 4.5% in June, this was the fastest pace since 1991.
Source: YCharts
There is an argument that the recent rise in inflation is temporary. One prime reason is attributed to the supply constraints due to the pandemic. The sudden rise in used cars and trucks accounted for a major portion of the inflation number, and this was mainly due to the global chip shortage, which reduced the supply of new cars. Used cars and trucks rose 10.5% in June from the previous month, when you compare on a yearly basis, prices rose about 45%.
Last week, we discussed in detail technical signals that suggest the market is not currently concerned with inflation. We see this in the new uptrend in bonds and the collapse of certain economically sensitive commodities. The market is shrugging off inflation fears, for now.
You can read our Portfolio Manager’s July Market Update that discusses this in detail here.
We are prepared to shift our investing thesis if the narrative changes. If inflation is not transitory, this reality will show up in price relations first. For example, if bonds continue down while commodities continue up, this could lead to the FED increasing the Fed Fund rate sooner than expected.
Historically, the rise in interest rates has been negative for equities, which ultimately stops the bull market. Some of the possible reasons are when the discount rate increases the present value of future cash flows will be lower. Another reason is that debt servicing costs for companies with high debt will be higher. The exception will be banking stocks which benefit from rising interest rates.
Even if this happens, history tells us that the time to worry is not when the first rate hike happens, but up to 18 months on average after the yield curve inverts. So, even if rates increase ahead of schedule, history tells us that we still have time for the bull market to run.
It’s important to remember that what causes the cascade of events that leads to a bear market, is the FED reacting to rising inflation. So, the sky-high data regarding inflation is nothing to shrug off completely. If inflation numbers do not subside, the FED will have no choice but to raise rates, and we could be looking to invest in an inflationary environment.
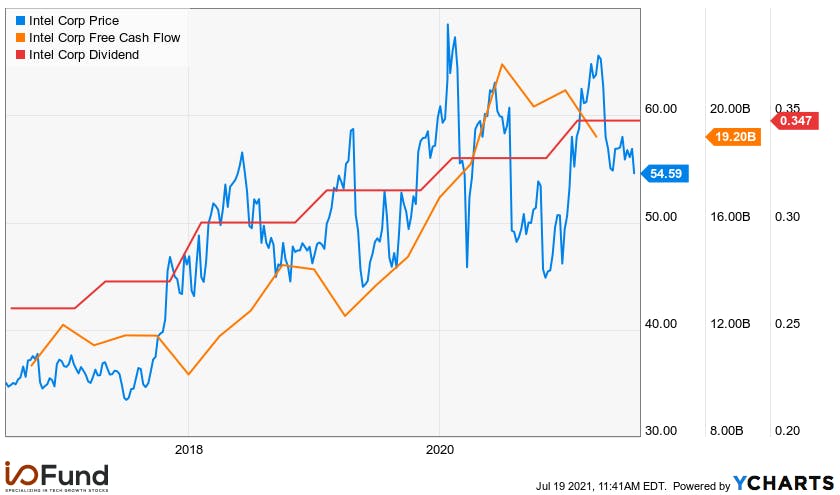
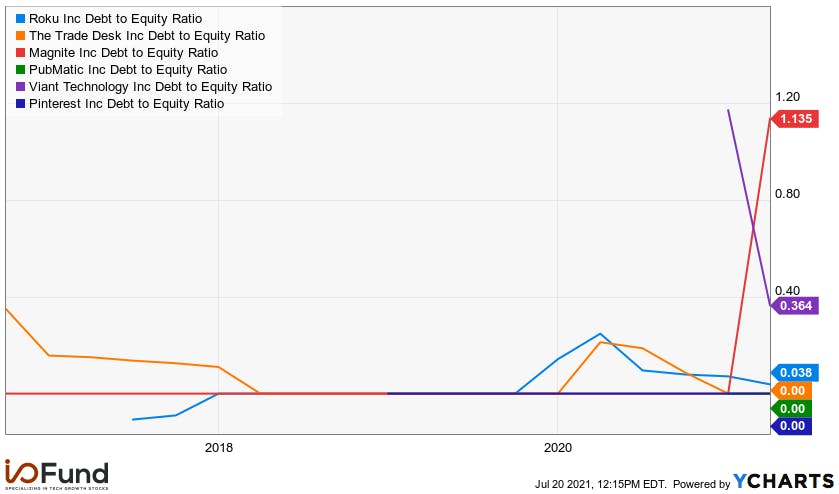
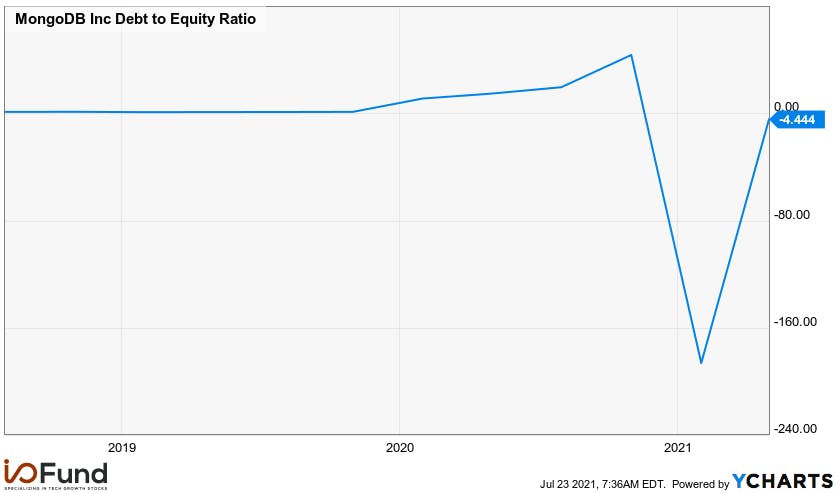
Stocks can make solid investments precisely because they beat inflation in the long-term. On a more granular level, the more traditional thinking here is that dividend stocks are ideal during periods of inflation because of the periodic dividend payouts. Dividends also help to fund your increased expenses due to inflation. While growth appreciation stocks are good in the long term, many institutions will see dividend stocks that have reasonable growth as an important hedge. They will also typically view low debt companies with low debt servicing costs as favorable.
Please note: the I/O Fund is a tech growth portfolio that places an emphasis on growth over profits, and for this reason, the I/O Fund does not currently hold stocks for their dividends. Below, we discuss what inflation trades can look like for a more forward-looking discussion.
Dividend Stocks that Institutions Could Favor for an Inflation Trade
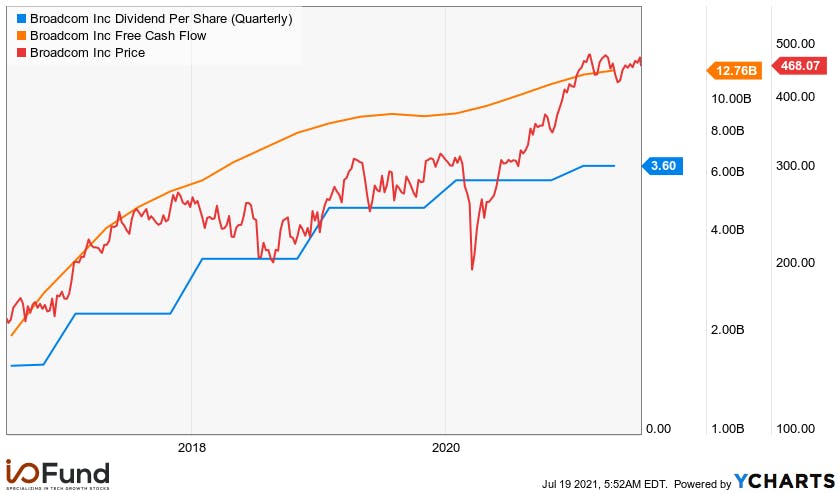
Broadcom Inc. (NASDAQ: AVGO) shares rose 50% in the past year. The company’s revenue growth has been strong as it grew at a compound annual growth rate (CAGR) of 16% in the past five years. It also has a very good profit margin which also plays an important role in the long-term stability of dividend payouts.
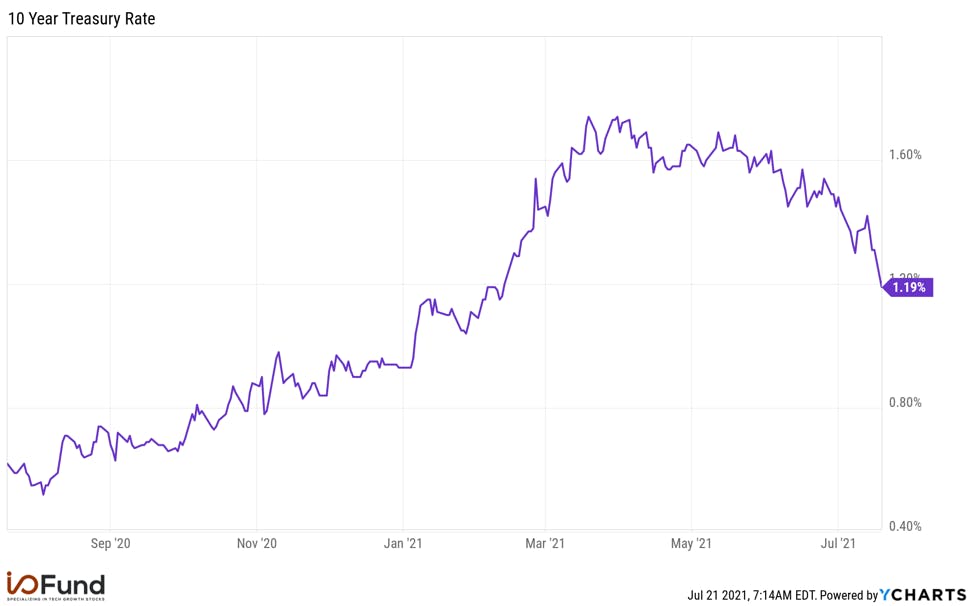
The company has a dividend yield of 3.00%. It is comfortably above the US 10-year treasury rate of 1.19%. The company has steadily increased its dividends. The free cash flow from which the dividends are paid is also increasing. In the recent earnings call, the company’s CFO, Kirsten Spears mentioned “Relative to capital allocation, first and foremost, we're dedicated to paying 50% of our free cash flows to our shareholders.” In the recent quarter, it had a free cash flow of $3.4 billion and dividends paid were $1.6 billion.