Data Center

Oracle Hit From All Sides: Iaas Cloud and Programmatic

Written by

Beth Kindig

Founder, CEO and Lead Technology Analyst

Published: June 25, 2018

Last Updated: June 25, 2018

Summary: Infrastructure as a service (IaaS) is the fastest growing cloud segment and will continue to be with AI, machine learning and connected cars. Gartner, an authority in tech analysis, placed Oracle in the “niche player quadrant” (not the leader quadrant) for Infrastructure as a Service (IaaS) May 22. In addition to IaaS, Oracle’s Data as a Service business model will weaken as marketers fail to get proper consent for ad targeting.

Cloud infrastructure is hot right now and for good reason. The world increasingly relies on cloud data centers due to server virtualization, smartphones, movies and entertainment, chatbots, office productivity, software as a service, and social media, to name a few.

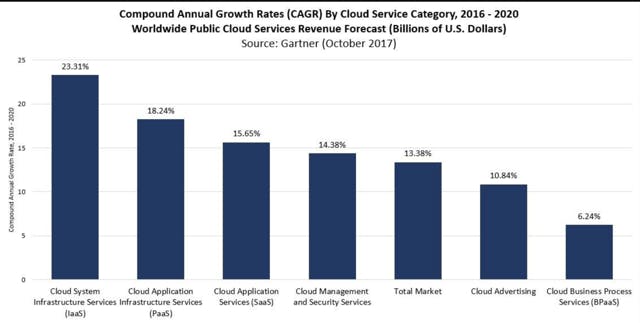
Gartner predicts the worldwide public cloud services market will grow to 21.4 percent in 2018 to $186.4 billion. The fastest growing segment is infrastructure as a service (IaaS) forecast to grow 35.9 percent in 2018. As we store more data in the cloud from AI and machine learning, this sector will continue to expand. For instance, fully automated cars will produce an estimated 25 Gigabytes of data per hour or 300 TB per year. Therefore, any savvy investor should place bets in this sector for 2021 and beyond.
No Medal for 4th Place in Cloud Infrastructure

Oracle (ORCL) is a long-time enterprise cloud powerhouse with billions invested in engineering and strategic acquisitions. On the quest to build and defend a range of cloud services, the company is expanding hybrid-cloud technologies, investing in customer-success programs, and benefiting from a less-than-expected decline in on-premise revenue. On the other hand, the transition to the cloud is taking longer than expected, according to Keybanc analysts, and is at risk for lagging behind Amazon (AMZN), Microsoft (MSFT) and Google (GOOG) in the Infrastructure as a Service category, the fastest growing category in public cloud services.

Last quarter, Oracle beat earnings estimates but came in slightly below expectations for revenue at $9.77 billion vs. $9.78 billion. The adjusted earnings of 83 cents beat the consensus estimate of 72 cents and was up 20% for its fiscal third quarter, which ended February 28. The better than expected earnings were not enough to convince investors in Q3 as the stock fell 4 percent after earnings were reported, then fell an additional 8 percent in pre-market trading. The stock is at $46.16 today compared to $52.90 before Q3 earnings.

One major concern is Oracle’s low share of cloud infrastructure and platform revenue, which came in at $415 million with 28 percent growth compared to Amazon at $5.11 billion revenue at 45 percent growth. It doesn’t help that Gartner, an authority for accurate tech analysis, placed Oracle in the “niche player quadrant” in the Magic Quadrant (not the leader quadrant) for Infrastructure as a Service (IaaS). Notably, financial analysts from JP Morgan and Murphy lowered Oracle targets yesterday, however, Gartner published this magic quadrant on May 22nd and it is likely what these analysts based their predictions on.

Meanwhile, in another category, cloud software (SaaS) revenue was up 33% last quarter for Oracle at $1.15 billion with notable competitors SAP and SalesForce. The remaining revenue is primarily on-premise revenue of $6.42 billion, and software license revenue of $1.39 billion.

While Oracle has maintained a name for itself in cloud services, it’s offerings are not strong enough to earn a medal as a front runner, which will spell trouble for earnings as Data as a Service (DaaS) undergoes regulations.

DaaS: Programmatic Will Crash

Oracle pursues many strategies and acquisitions for cloud services because it knows it has to be seen as a cloud company in order for Wall Street to invest in its future. However, one of Oracle’s main market positions is Data as a Service (DaaS). From 2012 to 2014, Oracle went on a tear of acquisitions to increase their marketing stack and to cement their position in the digital advertising space. In May of 2012, Oracle bought social marketing solutions provider Virtue for an estimated $300 million, the marketing automation firm Eloqua for $810 million in December of 2012, Responsys for $1.5 billion which is a business to consumer solution and the data management platform, BlueKai, for $400 million in 2014. This totaled an estimated $3 billion in collective marketing tech acquisitions to enhance DaaS.

Beth Kindig, founder and lead tech analyst of I/O Fund

Get Our Free Weekly Stock Newsletter

Get weekly stock insights, market analysis, and technology updates straight to your inbox.

  • Weekly stock insights
  • Market analysis
  • Technology updates

Programmatic is the automatic trading of advertising which is augmented by data for superior digital advertising. Oracle’s DaaS is essentially a way for companies to upload their data and potentially enrich their data by anonymously sharing and matching data sets. Oracle calls this “making your data smarter.”

Notably, BlueKai was a private company that captured the data boom with 9,245% growth from 2009-2012 – although competitors in the market saw a whopping 21,337% revenue growth (Data Xu). BlueKai was originally a buyer and seller of consumer data and pivoted to become a seller of data analytics and management technologies. These acquisitions were designed to help Oracle enable private data sharing. This is where the marketing ecosystem ingests first-party data and brokers marketing communications (MarCom) and advertisements in a second- party data transaction. While the data is not being sold, the information is being shared to third-parties without consent for the purpose of more advertisements.

My newsletter subscribers get this information first. Sign up here.My newsletter subscribers get this information first. Sign up here.here.

As the Oracle BlueKai deck states, here are some examples:

  • Hotel chain sharing data with a bank to target customers who do not have bank rewards cards
  • Online broker sharing data with a social media site for audience based targeting
  • Social media site sharing data with a technology company

While Oracle Blue Kai may not come directly under regulation because they are the middleman, and not the company with a direct relationship to the user, their business model is likely to weaken due to the way the data is being used. Marketing platforms and data management platforms will increase a marketers liability if they choose to transfer and trade private, first-party data. For these marketers, under the GDPR, consent must be given for each processing operation need and cannot be bundled together. Therefore, there will be less advertising and Marcom data to process, lowering Oracle’s revenue.

My Prediction: Cloud infrastructure will continue to grow as data storage increasingly provides the infrastructure for technological advancement. Amazon, Microsoft and now Google have been upgraded while Oracle has been downgraded during a key growth stage for IaaS. In addition, Oracle acquired many companies in the DaaS space which will continue to wane as regulations increase on customers using Oracle for targeted data. Couple this with fierce competitors in the IaaS and SaaS space, and Oracle will see lower than expected earnings this year.

I consult for financial firms. Inquire here.

About the author

Beth Kindig

Beth Kindig

Profile

Beth Kindig is the Founder, CEO and Lead Technology Analyst at I/O Fund, with more than 15 years of experience covering private and public technology companies. Known for her early Nvidia research beginning in 2018 and bold, high-conviction calls on emerging technology trends, Beth also manages I/O Fund's audited technology portfolio, which has returned 326% since May 2020, or 29.2% annualized. She is a regular guest on Fox Business and Bloomberg and has appeared on Real Vision, CNBC, Yahoo Finance, BBC, MarketWatch, Forbes, and more.

Curation

Expand your knowledge

View all posts
Beyond Hyperscalers: Here’s the Next $1 Trillion AI Infrastructure Opportunity
AI STOCKS

Beyond Hyperscalers: Here’s the Next $1 Trillion AI Infrastructure Opportunity

Since 2022, Big Tech capex has been the clearest barometer of AI demand. But the market’s reaction to Google’s latest earnings shows investors are questioning how long that spending can last. While the market frets over hyperscalers’ cash flows, a second wave of AI infrastructure spending has quietly emerged, driven by enterprises and neocloud customers.

AI STOCKSOCT 30, 2026
Google’s $250 Billion AI Chip Opportunity Takes Aim at Nvidia
AI PLATFORMS

Google’s $250 Billion AI Chip Opportunity Takes Aim at Nvidia

In April, there was a major shift in the AI accelerator market, and for once, it didn’t come from Nvidia. Six months later, merchant TPUs are moving from announcement to commercial execution, with Google recognizing its first revenue from TPU systems in Q2 (from a small base). Last quarter, Cloud revenue growth accelerated to 82% for $24.8 billion, compared to $22.5 billion expected. In addition, new details around the TPU 8t show that Google’s threat to Nvidia is not limited to inference. At the time, we pointed out that Google may be one of Nvidia’s strongest AI challengers, as Big Tech is closest to the problems that accelerators must solve. The problem that Google is prioritizing is lower cost per token, with token economics becoming a predominant concern as AI spending is pushing Big Tech’s free cash flows into the red. Below, we discuss two reasons why Google’s AI story is about to change, not from advancements in AI software, but by going after one of the most profitable hardware businesses the tech industry has ever seen.

AI PLATFORMSOCT 23, 2026
AI Debt Nears $500 Billion in 2026: What It Means for Nvidia, Oracle, CoreWeave and AI Stocks
AI STOCKS

AI Debt Nears $500 Billion in 2026: What It Means for Nvidia, Oracle, CoreWeave and AI Stocks

AI-related debt reached $466 billion through September 2026, more than four times last year’s pace. We break down who is borrowing, the three ways new AI chip deals are being structured, and where interest costs land across Nvidia, Oracle, CoreWeave, Broadcom and Big Tech.

AI STOCKSOCT 23, 2026
Oracle Faces Pressure From IaaS Cloud and Programmatic Ads