
I/O Fund is covering the preview for the second part of earnings for cloud stocks. It includes seven of the leading cloud security, productivity tools and data analytics companies.
We covered the first round of cloud earnings at the beginning of November.
We now cover:
- Zscaler Inc
- CrowdStrike Holdings Inc
- Elastic N.V
- Snowflake Inc
- Okta Inc
- DocuSign Inc
- Asana Inc
These earnings previews help our readers keep track of changes in trends and where to focus for new opportunities. It also helps to hear what analysts are saying about key companies prior to earnings reports.
We noticed that cloud companies with solid stock performance on the run-up to the results beat estimates. For example, Cloudflare stock rose 67% a month before our coverage and the company had a blowout result. We identified in this analysis that the company is adding numerous customers and, also, the trend continued in its third-quarter results.
To better understand recent valuations across cloud stocks and how the sector is positioned, please refer to our analyst Bradley Cipriano’s analysis, “I/O Fund Q3 2021 Cloud Stock Earnings Preview – December Edition”.
Zscaler – Earnings on November 30
Source: YCharts and Earnings Reports
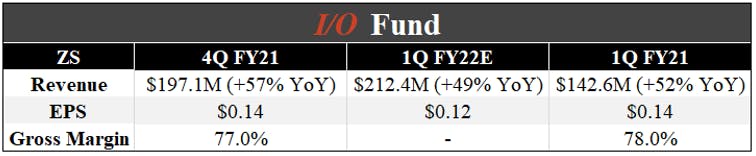
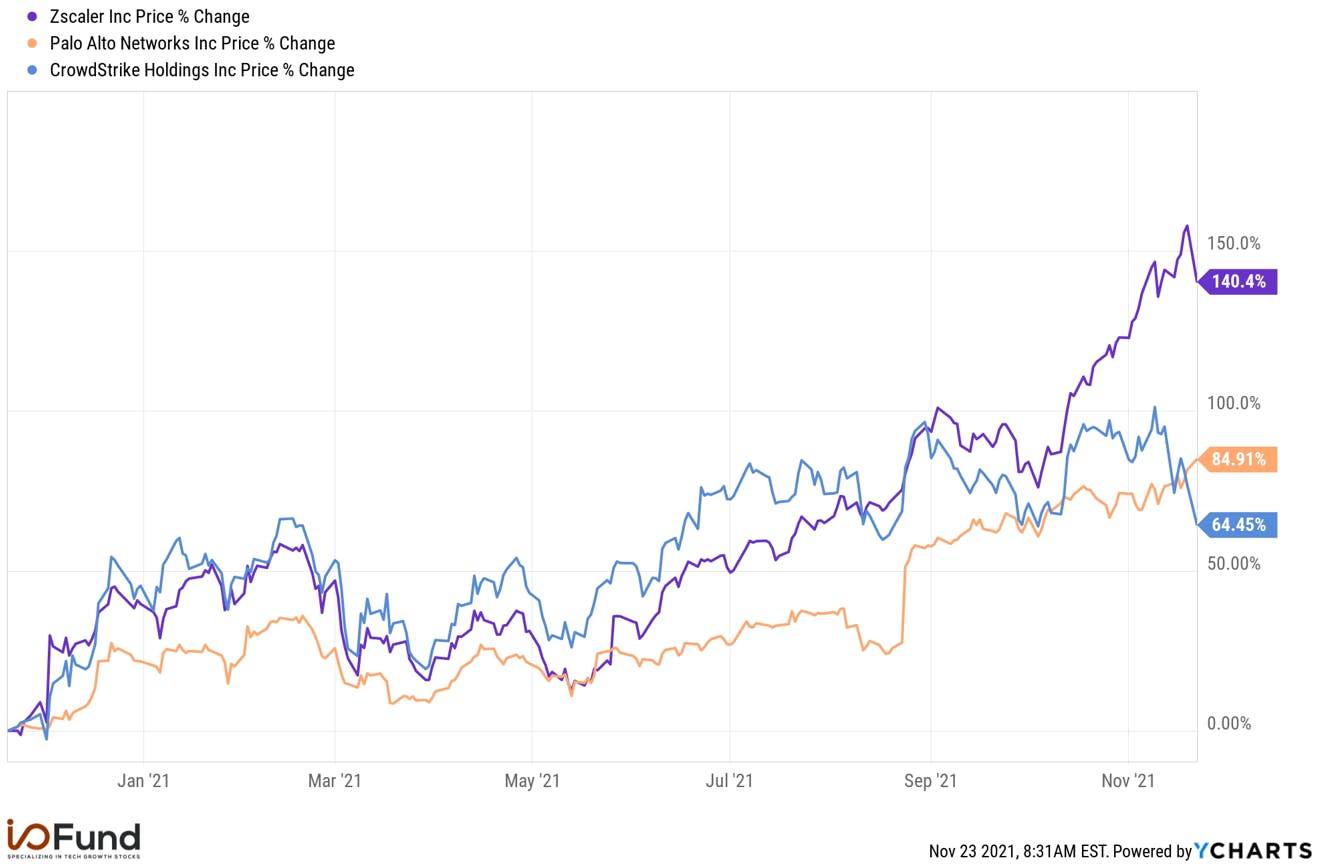
Zscaler Inc has recently rescheduled the release of its results a day earlier as peer companies are releasing on December 1st. The consensus revenue estimates suggest a 49% YoY growth and are slightly higher than the management’s revenue guidance of $210M to $212M. Zscaler is up around 140% in the past year and has been outperforming cybersecurity peers.
Source: YCharts
Mizuho analyst Gregg Moskowitz raised the firm's price target to $385 from $320 and has a buy rating on the company. The analyst says software valuations have "continued their ascent in recent weeks" and that he's raising price targets to reflect recent appreciation in comp multiples.
BTIG analyst Gray Powell has a buy rating and raised the firm's price target to $401 from $324. The analyst states that his discussion with an industry expert and his checks over the last few weeks indicate a positive spending environment across the majority of categories in the space. Powell adds that the expert described the Zscaler business as one that continues to accelerate, following "strong" demand trends observed for the company in October.
Sign up for I/O Fund's free newsletter with gains of up to 1100% - Click hereSign up for I/O Fund's free newsletter with gains of up to 1100% - Click hereClick here
Daiwa analyst Stephen Bersey initiated coverage of Zscaler with a neutral rating and a $266 price target. The analyst says the stock's trading multiple is near a level that he believes is appropriate. While Zscaler's recent sales growth results have been well above many of its peers, a 28x sales multiple more than accounts for its strong top-line growth and earnings potential.
Please note, I/O Fund is objectively reporting what the Street is saying. We covered Zscaler previously below:
Tech Growth Earnings Review for Q3 2020 - Part 3
CrowdStrike – Earnings on December 1
Source: YCharts and Earnings Reports
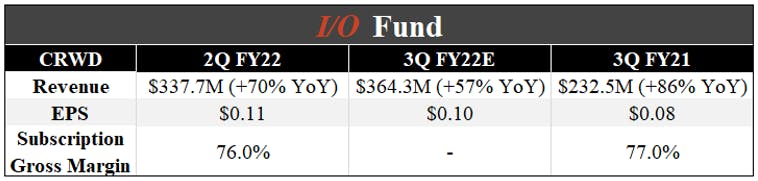
CrowdStrike’s revenue accelerated 70% in the 2Q to $337.7M and subscription revenue increased by 71% YoY to $315.8M. It added a net 1,660 subscription customers, raising the total to 13,080 subscription customers. Recently, it announced new security products to expand its reach in extended detection technology (XDR).
DA Davidson analyst Rudy Kessinger initiated coverage of CrowdStrike with a buy rating and a $320 price target. The analyst is positive on the company's "superior" cloud-native technology that has significant network effects driving sustainable competitive advantages, along with its large and expanding total addressable market. Kessinger further cites CrowdStrike's multiple drivers to sustain high rates of growth and its "significant operating margin expansion" that is likely over the next several years.
Morgan Stanley analyst Hamza Fodderwala has undertaken coverage on the stock with an underweight rating and a price target of $247. He said in a research note that CrowdStrike has benefitted from the shift toward digitalization and remote work over the past two years and gained a leading position in the area of what’s called endpoint detection and response (EDR) security.
However, Fodderwala said that checks within the security industry "indicate CrowdStrike's early leadership position is now increasingly challenged by more competitive next-gen EDR alternatives." Fodderwala said that competitors have come in and undercut CrowdStrike's prices by at least 15% to 20%, and that "this competitive dynamic will make sustaining [CrowdStrike's] current pace of share gains more difficult" through 2022 as working from home becomes commonplace.
Read our previous analyses below:
Nasdaq100 Levels to Watch for the Next Leg Higher
Tech Growth Earnings Review for Q3 2020 - Part 3
Momentum is on CrowdStrike’s Side: Will it Last?
Elastic – Earnings on December 1
Source: YCharts and Earnings Reports
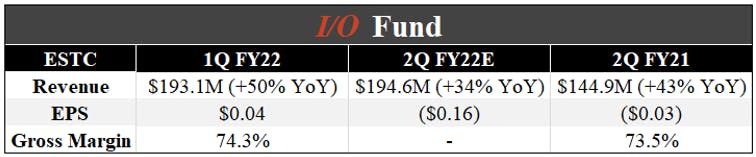
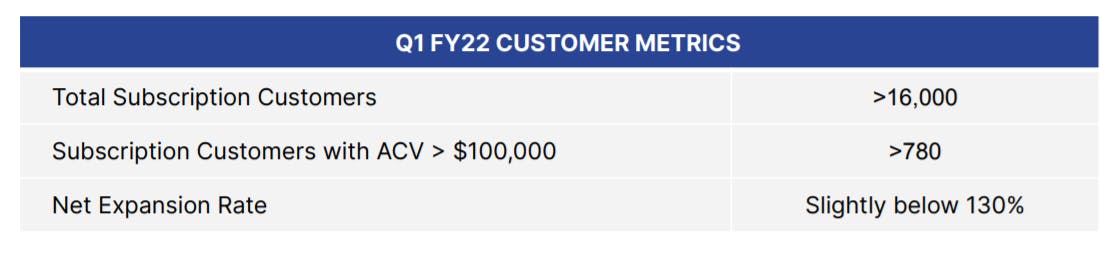
Elastic N.V’s revenue grew by 50% in the last quarter and Elastic Cloud revenues increased 89% YoY to $61.5M (accounts for about 32% of total revenue). The company had over 16,000 subscription customers at the end of Q1. However, growth is expected to slow down in the next quarter. Management’s revenue guidance is between $193M to $195M, representing a YoY growth of 34% at the mid-point.
Source: Investor Presentation
Barclays analyst Raimo Lenschow raised the firm's price target on Elastic to $200 from $185 and kept an overweight rating on shares. In a research note, Lenschow informs investors that over the next few months, investors will move to 2023, their new base year for valuations. For software, "with its high growth rates, this move is important as valuation levels often see a meaningful step down," says the analyst.
Oppenheimer analyst Ittai Kidron has an overweight rating and a price target of $185. The analyst notes Elastic reported a "strong" Q1 well ahead of consensus, reflecting broad-based demand across search, observability, and security; continued SaaS momentum; strong customer adds; and steady expansion metrics.
Read our previous analysis on the stock here: Tech Growth Earnings Review for Q3 2020 - Part 3
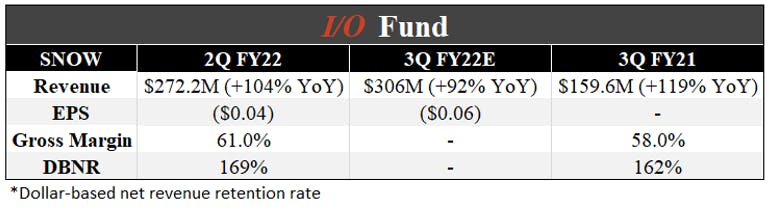
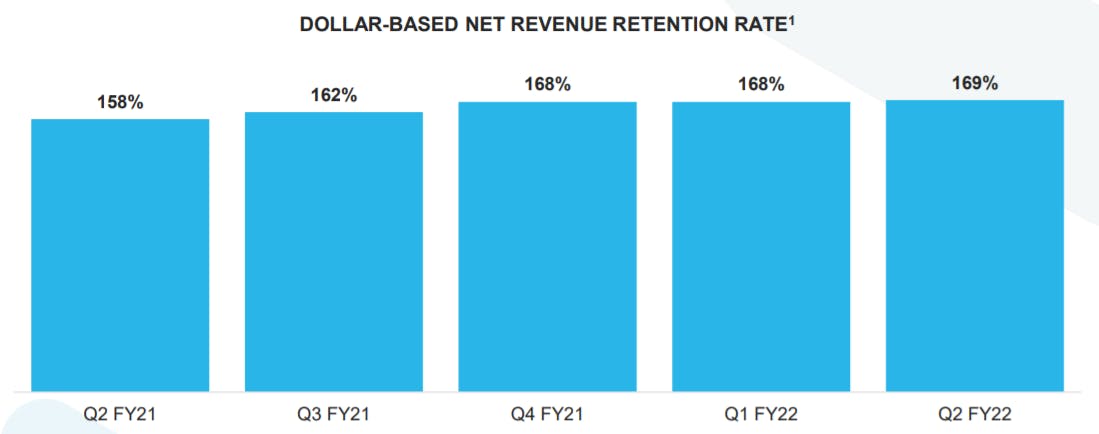
Snowflake – Earnings on December 1