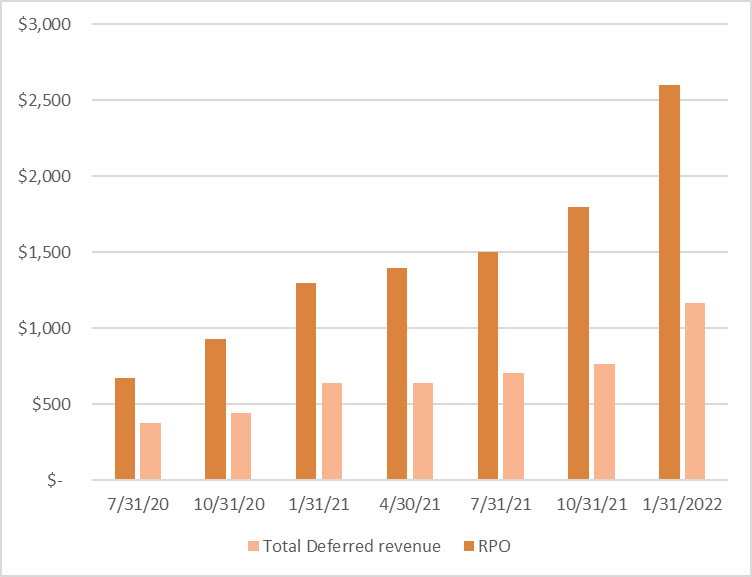

With Q4 earnings drawing to a close, many high-performing technology stocks have been penalized despite reporting excellent results. With macro headwinds taking center stage, many investors are simply tossing high performers aside as they look to de-risk.
At the I/O Fund, we track numerous earnings reports from hyper-growth technology companies, and we believe that Snowflake’s most recent results position the company as a premier software firm. While there were some blemishes in the Q4 print that impacted near-term growth, the long-term story remains very much intact. In fact, key forward-looking metrics improved during the quarter, providing support for future sales and improving the quality of recently reported resultsquality of recently reported results.
However, there remains a difference between great businesses and great investments. Snowflake is a great business, but does its premium multiple pose a risk? In the discussion below, I outline Snowflake’s most recent results and what likely led to the recent the sell-off, followed by a discussion of key metrics that warrant Snowflake a premium multiple. Given the recent market volatility, I believe that there is upside in Snowflake’s valuation given a longer time horizon.
Snowflake’s Q4 Results and What to Look For in FY2022
The I/O Fund’s lead Tech Analyst Beth Kindig had previously released a deep dive on Snowflake’s product for free here. At this point, most would agree Snowflake is a solid tech product that promises to disrupt data warehouses by decoupling compute and storage, which reduces costs. Rather than focus on product in this discussion, I will instead focus on the company’s most recent financial results and its outlook going forward.
The key takeaway is that sales growth remains robust and high quality, however, the company’s consumption billing model can make growth lumpy in the near term. This is unique from subscription models in cloud because growth from consumption billings is non-linear: growth oscillates more than subscription models. Importantly, consumption billing is uncapped and can lead to stronger growth over the long term as customers find new uses for Snowflake’s platform and continue to ramp spending over time.
In the latest quarter, Snowflake’s Q4 product sales increased 102% YoY to $360 million, after increasing 116% YoY in the year-ago quarter. For the year, FY2022 product sales increased 106% YoY to over $1.1 billion. Despite the triple-digit revenue growth during the quarter, this represented the slowest pace of quarterly YoY growth since Snowflake went public. Considering Snowflake’s premium multiple (discussed in more detail below), the market was likely disappointed at a lack of acceleration in sales growth, which may have contributed to the recent sell-off.
Moreover, analysts had anticipated a slow-down in sales during the quarter and Snowflake still beat topline estimates by $10 million. Yet, this represented the smallest beat on record and was half of the $25 million beat reported in the prior quarter. As I’ll discuss in more detail below, management could have reported a larger beat by delaying product improvements and/or by liquidating RPO and deferred revenue. I believe that management’s approach to prioritizing long-term growth over beating near-term expectations should be applauded, and speaks to the quality of managementquality of management.
Looking forward, the company’s guide also came in largely as expected. In FY2023, product revenue is expected to grow 66% YoY to $1.9 billion, which was near the Street’s initial estimate of 67% growth. Since cloud is known for surpassing expectations, the in-line guide was likely viewed as a disappointment, contributing to the recent sell off.
The lackluster guide was due to customer-friendly product improvements instituted in the new year which lowered the costs of using Snowflake’s platform, but also lowered near-term topline growth expectations.
Importantly, the soft guide was not due to a lack of strong demand. Rather, management instituted customer improvements that are expected to be a near-term topline headwind (by lowering prices) but will ultimately lead to stronger growth over time as customers move more of their data onto Snowflake’s platform.
Essentially, the cost savings (which are crucial in the cloud, where data volumes grow exponentially) will lead to more volumes over time, leading to stronger growth in the long run. During the Q4 call, management explained that the process improvements made during the year are expected to reduce costs for customers, which is also expected to reduce FY2023 revenues by about ~$100 million.
Specifically, CFO Mike Scarpelli stated on the Q4 call that “throughout this year, we are rolling out platform improvements within our cloud deployments. No two customers are the same, but our initial testing has shown performance improvements ranging on average from 10% to 20%. We have assumed an approximately $97 million revenue impact in our full year forecast, but there is still uncertainty around the full impact these improvements can have.”
SVP of Product Christian Kleinerman added that “The more improving the economics of the platform, the more use cases come to Snowflake. So we’re looking at this with a very long-term view” and CEO Frank Slootman explained further that the change is expected to stimulate more demand and that “we’ve done this over-and-over and it does stimulate demand but it doesn’t do it in real time, there’s a lag involved in this processand it does stimulate demand but it doesn’t do it in real time, there’s a lag involved in this process”
Had management not made these process improvements, then its FY2023 sales guide would likely have been $97 million higher, and its guide of 66% YoY growth would have instead been close to 74% YoY, besting initial estimates. As mentioned above, these impacts are expected to be only a temporary headwind and will lead to stronger demand in the future. As I’ll discuss in more detail further below, the company’s forward-looking metrics support management’s claims that demand will remain strong going forward.
Continuing down the income statement, Snowflake’s Q4 adjusted product gross margin increased 500 bps YoY to 75%, while non-GAAP operating margin improved YoY from -24% to 5%. For the year, FY2022 adjusted product gross margin was 74% and non-GAAP operating margin was a loss of -3%. Looking forward, management expects FY2023 adjusted product gross margin to increase 50 bps YoY 74.5% in FY2023 and for adjusted operating margins to be positive at 1%. The market tends to award companies that are profitable with premium multiples, and Snowflake’s guide for 66% topline growth coupled with positive earnings warrants a premium multiple, in our view.
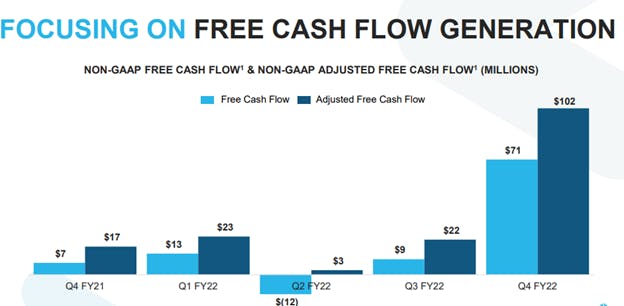
The company remains on track to meet its long-term guide for $10 billion in annual sales by FY2029 with 15% free cash flow margins. In fact, the company guided for 15% free cash flow margins in FY2023, driven by strong bookings. It is notable that Snowflake’s Q4 cash flows improved by $59 million YoY while stock-based compensation increased YoY by just $2 million during the quarter. Snowflake has kept its shareholder dilution under control and its fully diluted share count is expected to increase less than 1% in FY2023.
Despite the recent volatility in Snowflake’s valuation, we continue to believe that the company deserves a premium multiple. For instance, Snowflake’s growth is outsized relative to peers, adjusted earnings are expected to turn positive in FY2023 and cash flow growth is robust and is being driven by increased bookings, rather than excessive amounts of stock-based compensation. In the next section, I highlight a few more metrics that warrant Snowflake a premium multiple.
Trends That Support a Premium Multiple
As noted above, management is focusing on long-term growth by reducing costs for customers in order to attract more volumes. This process improvement led to a slight miss on the company’s guidance, and the company has been penalized for this decision. However, I suspect that the market is too fixated on near term growth and has largely ignored Snowflake’s high quality forward-looking metrics, which improved during the quarter and outweighed the near-term growth headwinds.
Below I outline key metrics that improved that I believe support a premium multiple for Snowflake:
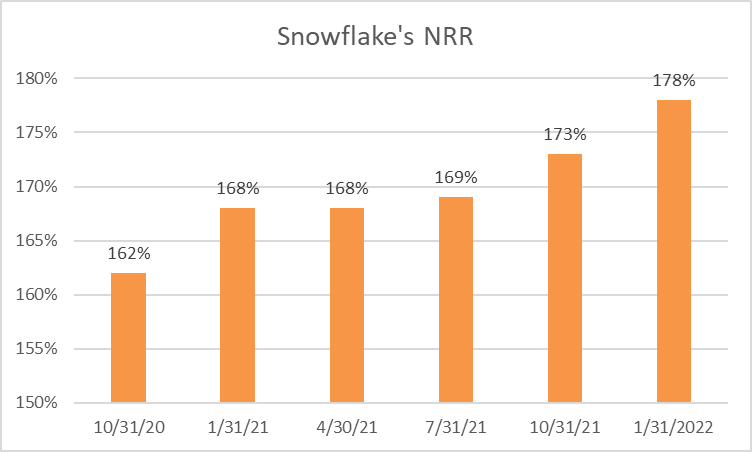
- Snowflake’s improving net retention ratio (NRR), which remains world-class;
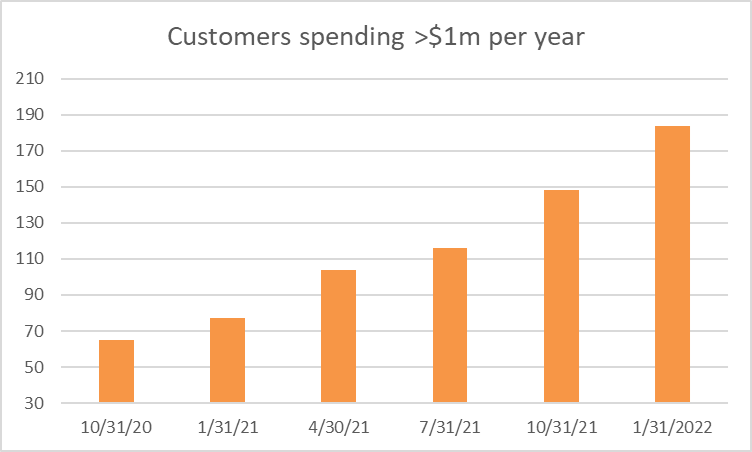
- Snowflake’s strength with enterprise customers, which are low-churn with large budgets;
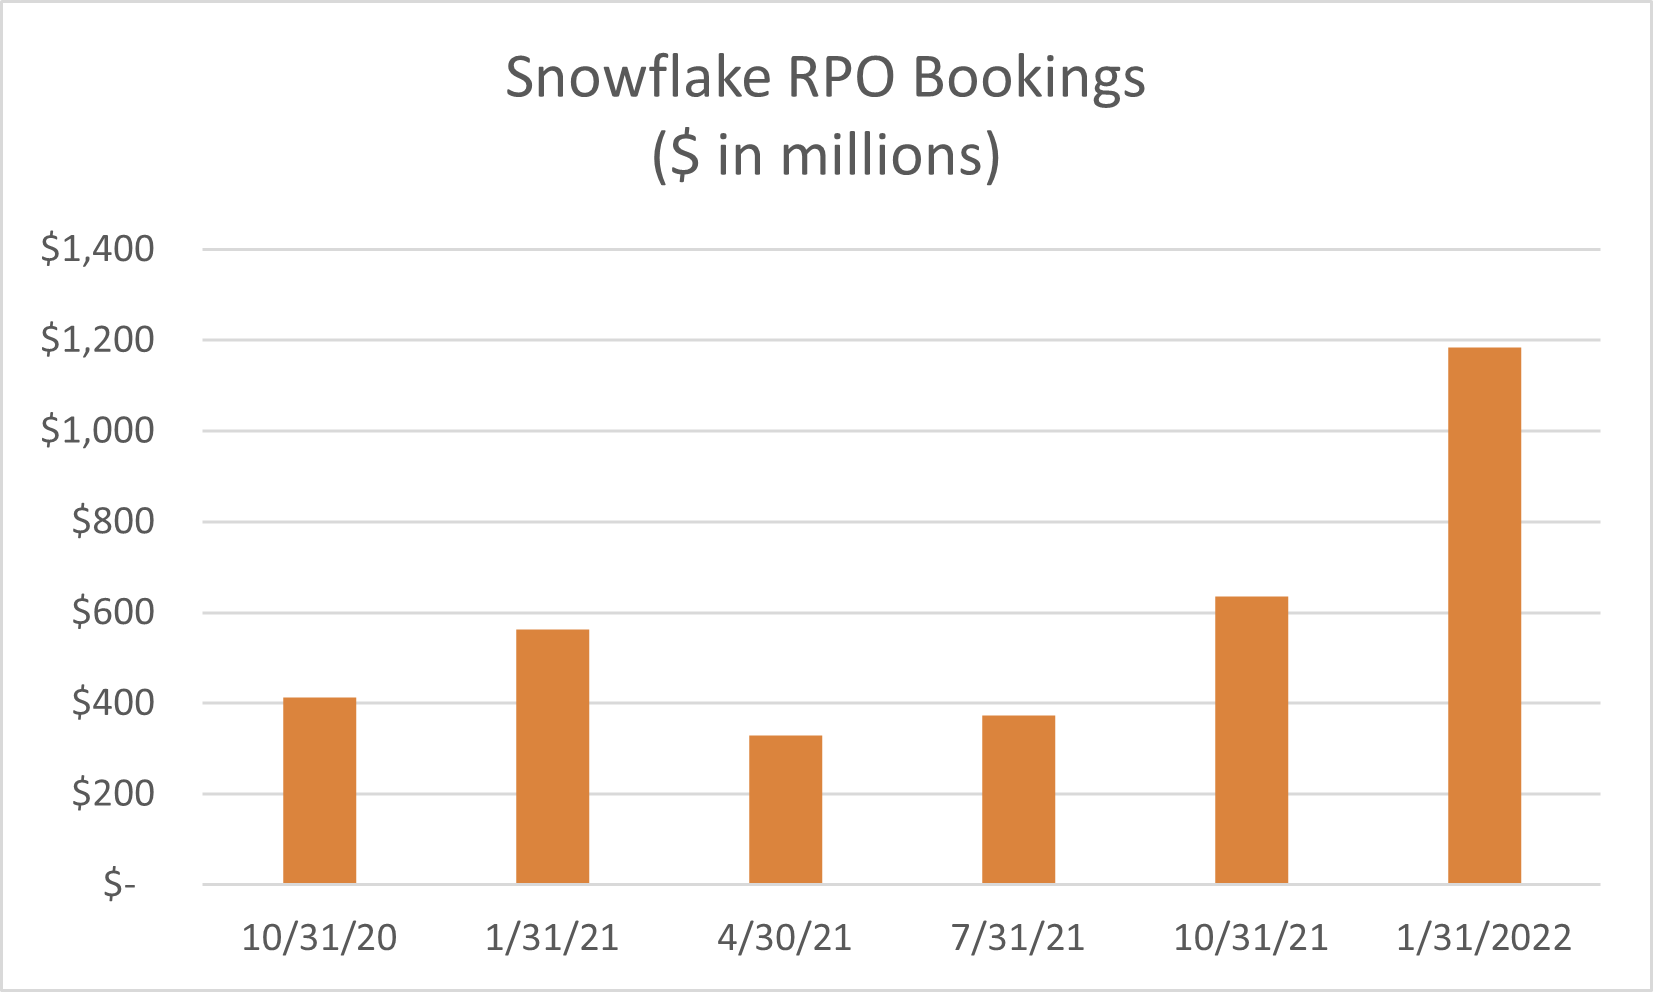
- Snowflake’s ramp in RPO bookings, which supports strong growth going forward;
- Snowflake’s cash support for future sales, which improves the quality of its recent bookings and;