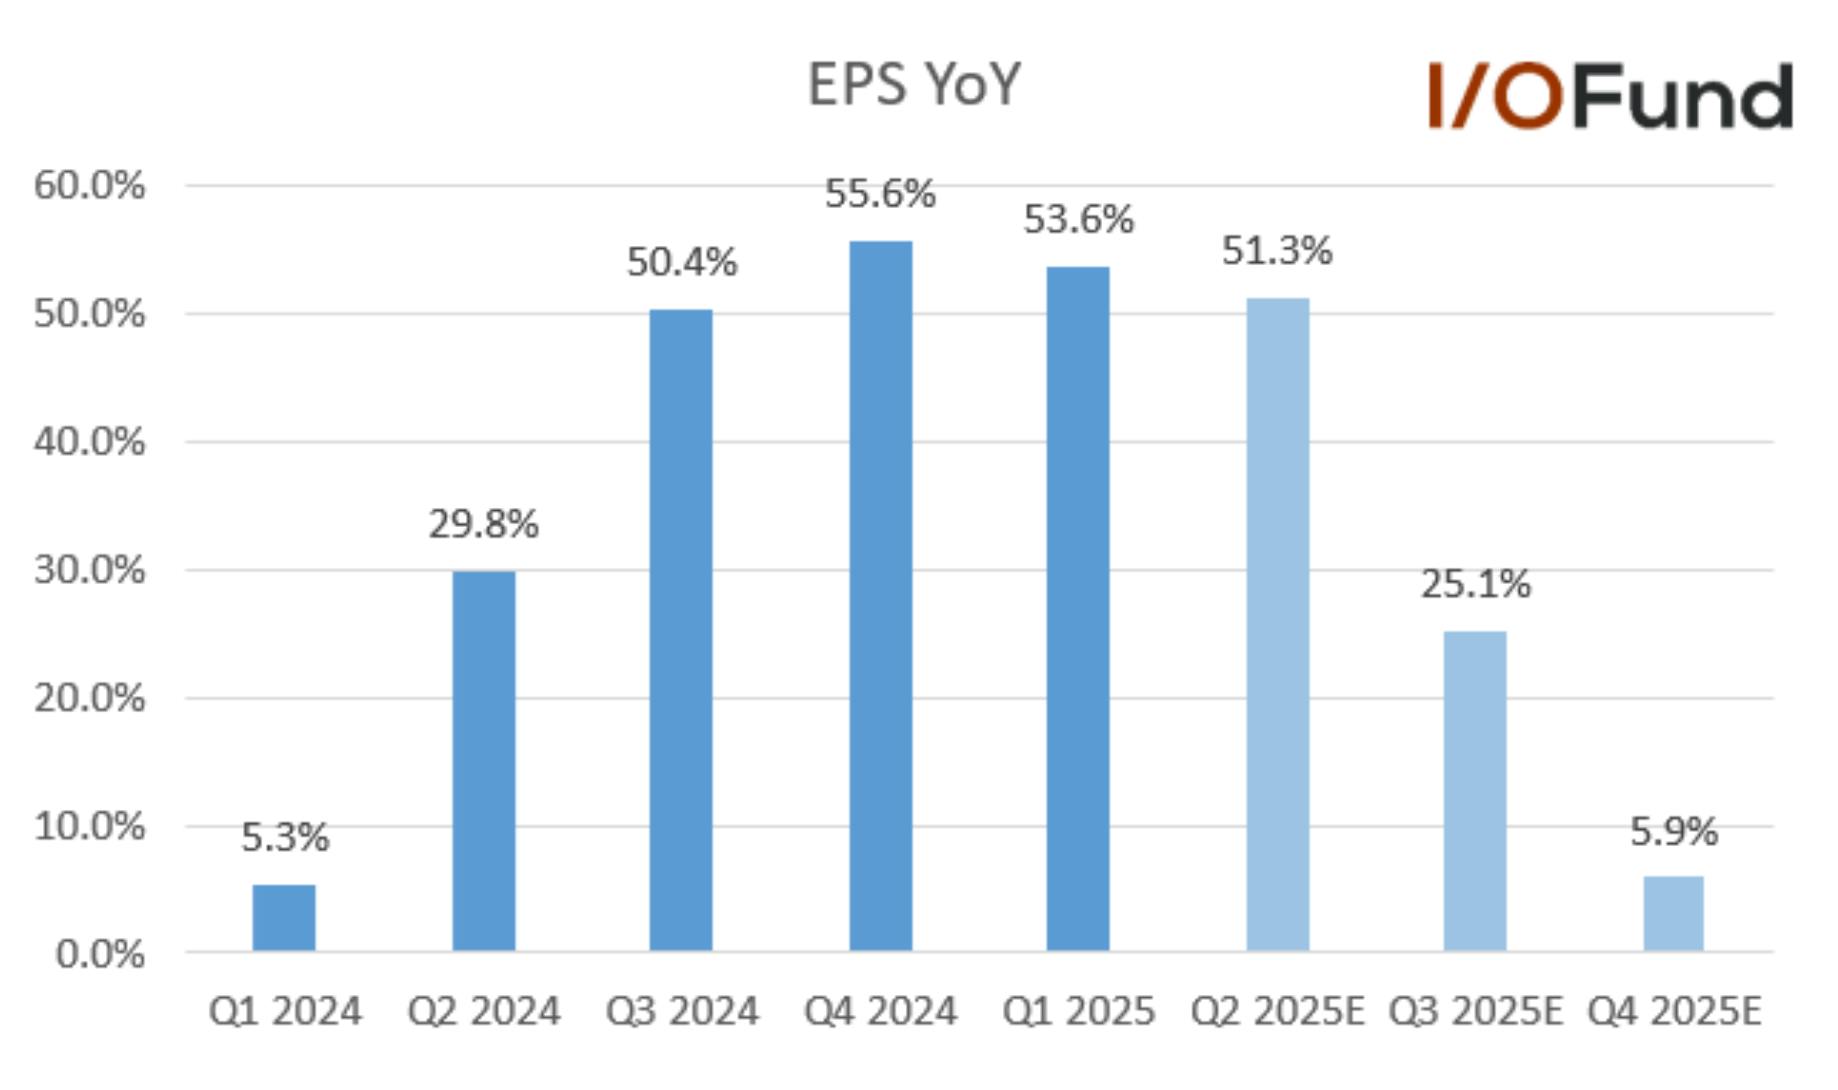

Despite their leadership, AI stocks like Taiwan Semiconductor and Nvidia are flat year-to-date and trading at similar levels as June 2024. Clearly, the AI trade is not as straightforward as it might seem. Taiwan Semiconductor, in particular, sits at the center of geopolitical tensions — yet those tensions tend to surround companies with deep IP in the AI economy. What makes this economy so distinct is not just the extraordinary commercial demand, but also its rare, historical role in shaping global alliances (and adversaries).
Investors are confronted almost daily with friction between the U.S. and China — and at the center of it all is one stock: Taiwan Semiconductor (TSMC). While enthusiasm around AI demand remains strong, assuming it will simply override geopolitical headwinds is overly optimistic. Onshoring a supply chain like TSMC’s takes years, yet markets can react to a negative headline in seconds.
Headlines aside, the bigger picture is that TSMC is deepening its moat with advanced nodes, such as N2 and A16. The company already powers tens of trillions in market cap on the stock market when you consider Apple, Nvidia, Broadcom, Amazon, AMD and Google are customers of TSMC. Essentially, all mega cap stocks have an AI strategy spanning merchant GPUs and custom silicon, and of course, software – yet the common denominator to these strategies is they all funnel into TSMC.
The problem my firm helps with is this — how does an investor ride out the inherent cyclical nature of semiconductors given the powerful, secular trend of AI? For every stock that becomes a multi-generational winner, there are dozens that never reclaim their all-time highs. The cloud sector for example, is becoming an all-time high graveyard with once-upon-a-time Wall Street darlings trading meaningfully below their ATHs for over three years now.
TSMC will very likely push beyond its ATH yet returns can increase meaningfully if an investor has the guts to buy during a steep selloff. Other times, that selloff isn’t coming and it’s best to buy before a breakout. We answer these complex questions in the analysis below.
TSMC’s Advanced Nodes have Created a Competitive Moat
The most advanced node shipping today is the 3nm, offering 15% better performance than the 5nm process when power level and transistors are equal. The die sizes are an estimated 42% smaller than the 5nm and TSMC also states the 3nm process can lower power consumption by as much as 30%.
Power efficiency is a major advantage, helping to deepen TSMC’s moat. Samsung was first to introduce 3nm process chips in 2022 yet has not been as competitive on yield and power efficiency at a roughly 10% to 20% difference compared to TSMC. The moat is visibly seen in TSM’s pricing power with the dominant foundry charging 25% more for its 3nm process compared to its 5nm process, and customers are willing to forego Samsung to pay the higher pricing.
Last year, companies such as Apple, Nvidia, AMD and Intel committed to working with TSMC for its 3nm process, and eventually Google and Qualcomm left Samsung “after careful consideration” to also secure a partnership with TSMC.
This was an important moment for TSMC to complete its near-monopoly in advanced nodes as Google had been outsourcing its Tensor processors to Samsung’s foundry for four generations, before moving to TSMC for the fifth generation. Qualcomm also switched to TSMC from Samsung for the Snapdragon 8 Gen 4 series.
To attract these large customers with different end markets, TSMC offers a few 3nm processes, such as the N3E, N3P and N3X. This allows a company like Apple to customize the 3nm chips differently than AI chips for hyperscalers. N3E is the baseline for IP design with 18% increased performance and 34% power reduction, N3P has higher performance and lower power consumption, whereas the N3X will offer high-performance computing very high performance but with higher power leakage.
To illustrate the near monopoly that TSMC has over other foundries, consider that its market share stands at 67.1%, up 2.4% QoQ in Q4. Meanwhile, second-place Samsung was at 8.1% down from 9.1% for a lead of 59 points.
When comparing revenue, TSMC reported $26.85 billion in Q4 for a 14.1% increase compared to Samsung’s $3.26 billion, which declined 100 basis points to 8.1%.
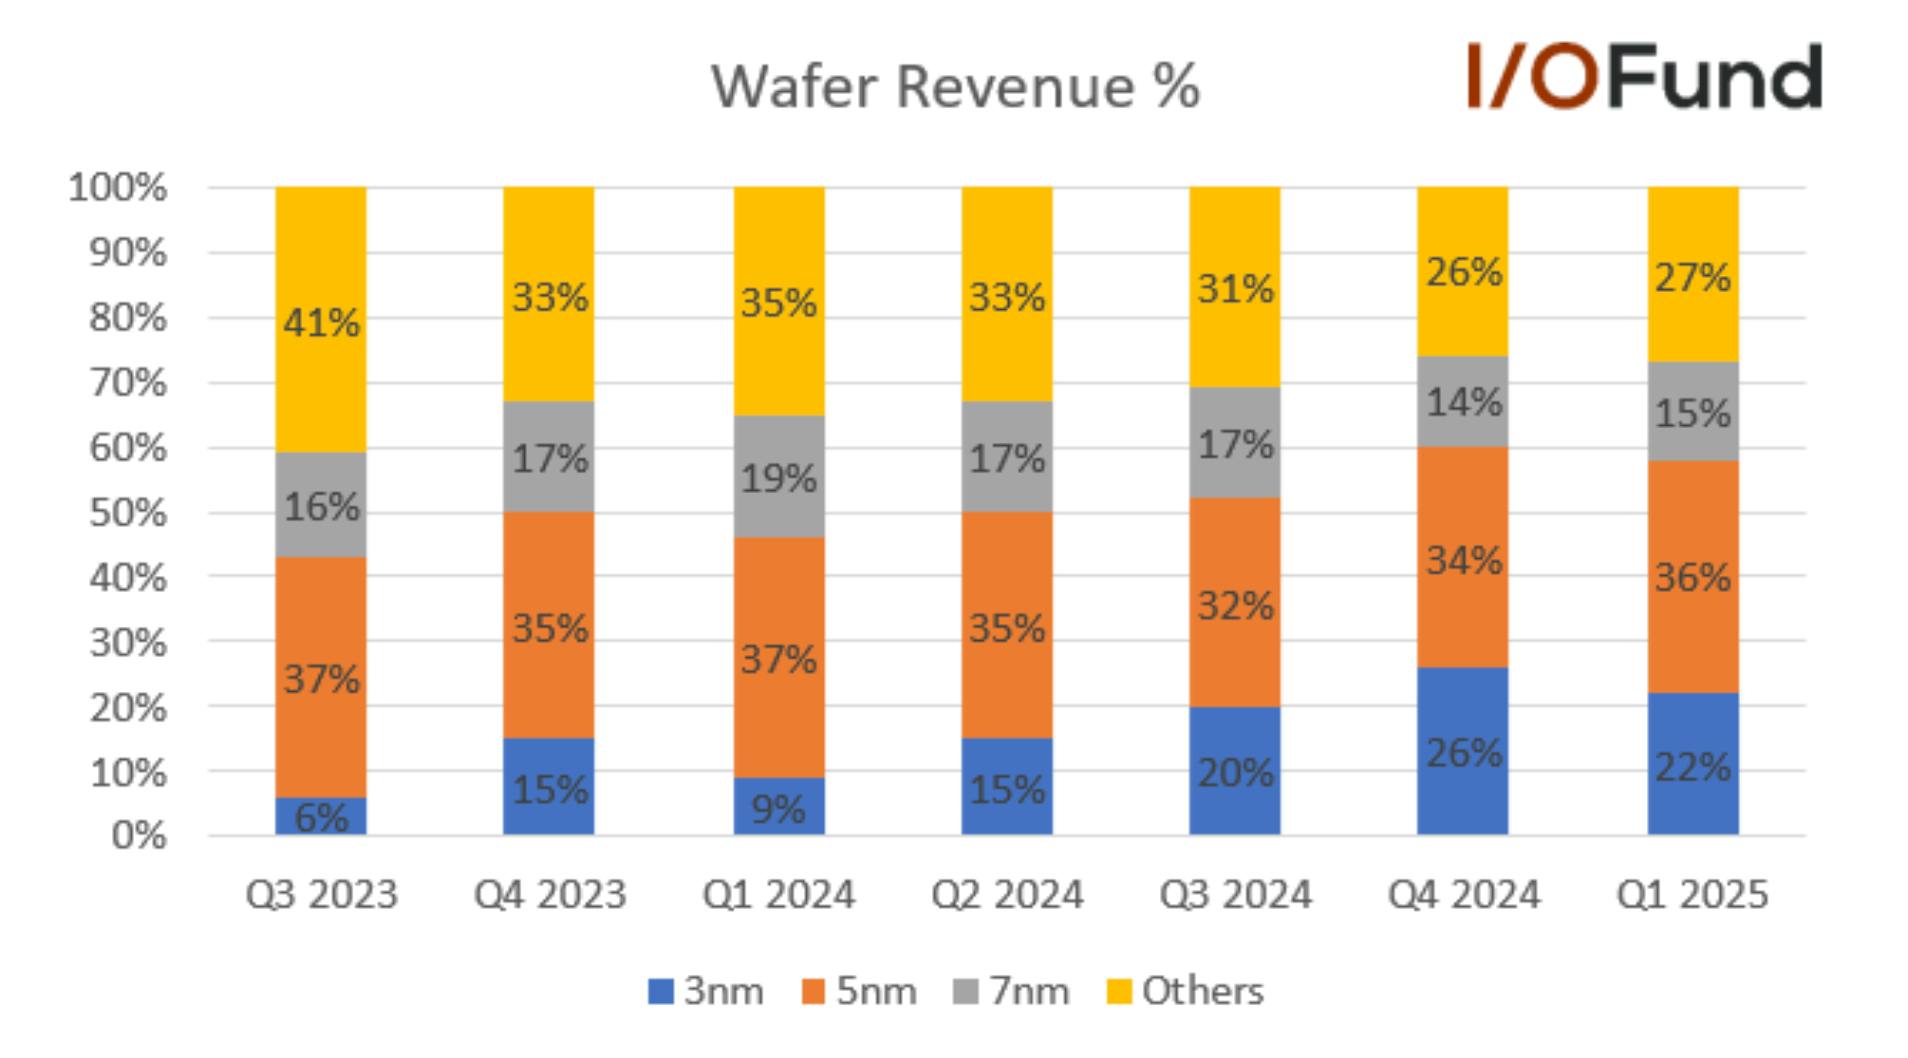
In the latest quarter, advanced nodes below 7nm drove 73% of wafer revenue with 3nm contributing 22% of revenue and 5nm representing 36% of revenue. Nvidia is not on the 3nm process yet for its Blackwell shipments, thus 5nm is outsized in terms of its market share.
TSMC’s 2nm Nanosheet Transistors (Gate All-Around)
Looking ahead, 2nm is expected to see volume production in the second half of 2025 with a more advanced iteration called N2P scheduled for volume production in the second half of 2026. The 2nm marks a new era in TSMC’s transistor architecture as N3 relied on FinFET while gate-all-around (GAA) is being introduced for N2. As the name implies, the gate is wrapped around on all sides compared to FinFET which had a gate wrapped on three sides. By having the gate wrap “all-around,” a greater surface is created for better electrostatic control and to also reduce leakage.
For TSMC, the 2nm will feature NanoFlex technology, which is similar to FinFlex to where designers can use cells from different libraries. However, due to the new gate-all-around (GAA) nanosheet transistors, there are additional benefits, such as customizing the width and height of cells. For example, GAA can uniquely widen the channels for a performance boost, or there is an option to narrow the channel to optimize power cost. The goal is to increase the performance-per-watt to enable higher levels of output and efficiency.
According to management on the earnings call: “N2 will deliver full-node performance and power benefits with 10% to 15% speed improvement at the same power or 20% to 30% power improvement at the same speed and more than 15% chip density increase as compared with N3E.”
Similar to the 3nm, there will be a few variants of the 2nm chip for customers to optimize performance with power requirements. The first two years of the 2nm ramp is outpacing the 3nm and 5nm ramp, signaling good things to come for TSMC.
TSMC Stock will Close out the Decade with Pricing Power
As a growth investor, it certainly doesn’t hurt to keep an eye on the horizon. A16 is the 1.6nm process node that will emphasize backside power delivery. Our firm first covered this topic last year in the analysis: “Taiwan Semiconductor Stock: April Sales Soar From Advanced Nodes” stating the Angstrom era will translate to “future process generations where the nodes are not smaller necessarily, rather the transistors they’re built with will be improved upon.”
For the A16, the Super Power Rail (SPR) backside delivery will offer a redesign to where power routing is moved from the front to the back, which allows for the signaling on the front side to have lower latency. By reducing voltage drop, SPR becomes attractive for AI workloads since multiple cores are operating at high speeds with complex signal routes and dense power requirements.
Intel’s PowerVia is first to market with the backside power delivery design, yet TSMC’s design will likely result in higher yields and volume production. TSMC also connects the backside power delivery to each transistor’s source and drain, which is more expensive yet also more efficient compared to Intel’s approach.
The A14 is due out in 2028 and will offer a significant breakthrough in performance while offering up to 25% to 30% lower power consumption, with increased density of 20% to 23%. There will be an A14 variant that offers backside power delivery in 2029. It’s expected that A14 will help to drive forward edge AI due to a combination of speed improvements and power reduction. Pricing for the A14 is expected to increase from $30,000 per wafer for the 2nm process to $45,000 per wafer as we close out the decade.
TSMC to Grow Revenue Mid-20%; AI Accelerator Revenue will Double
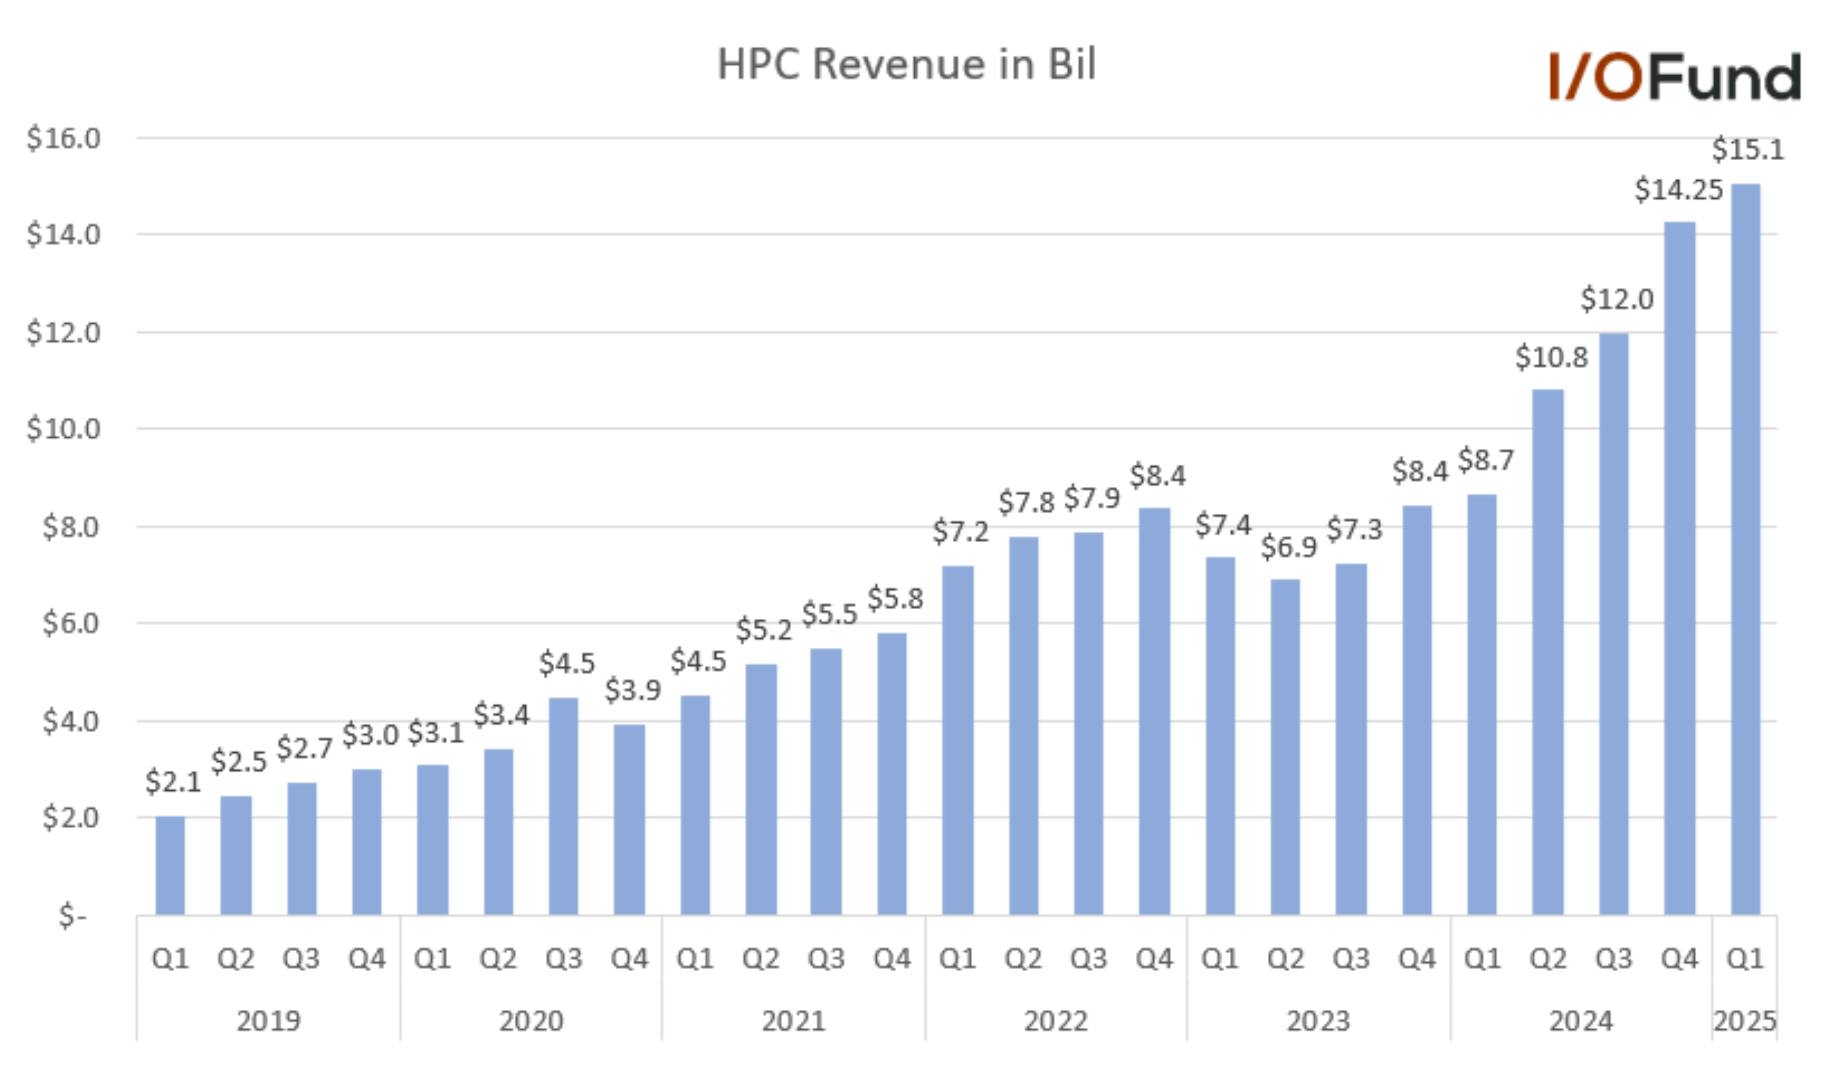
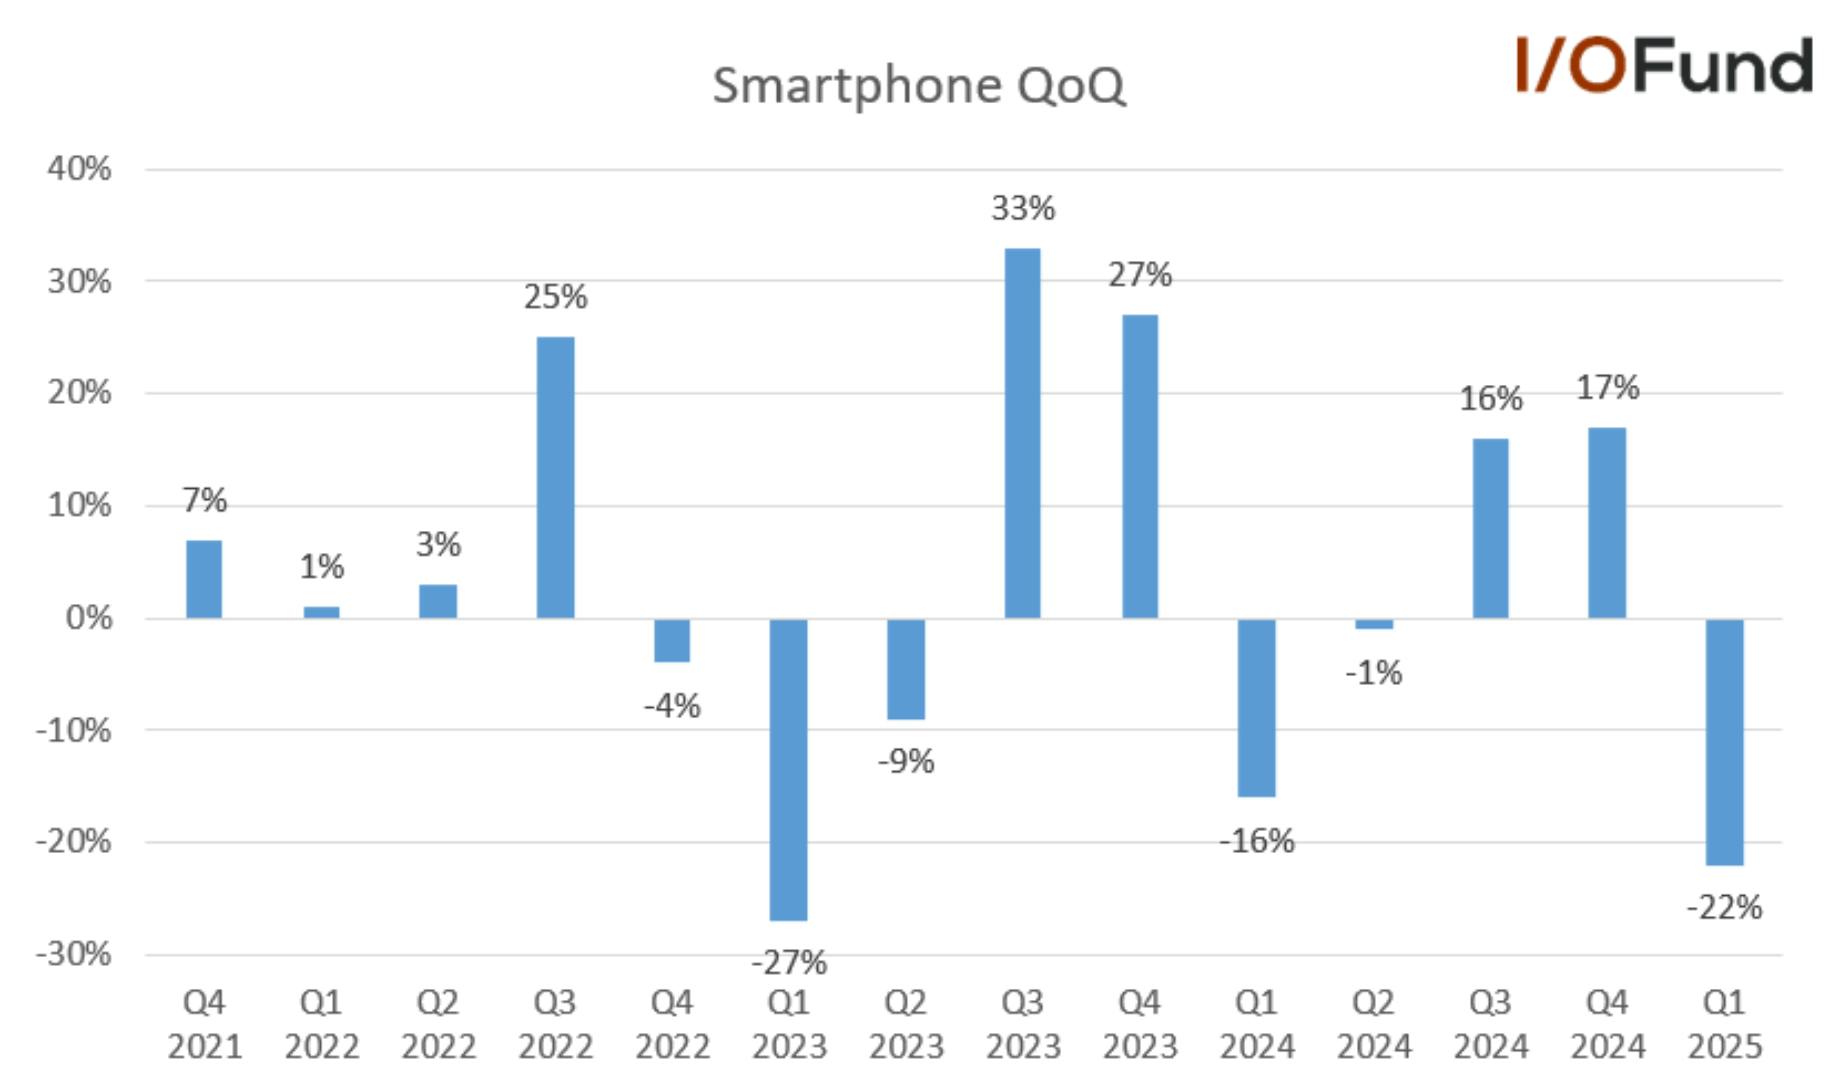
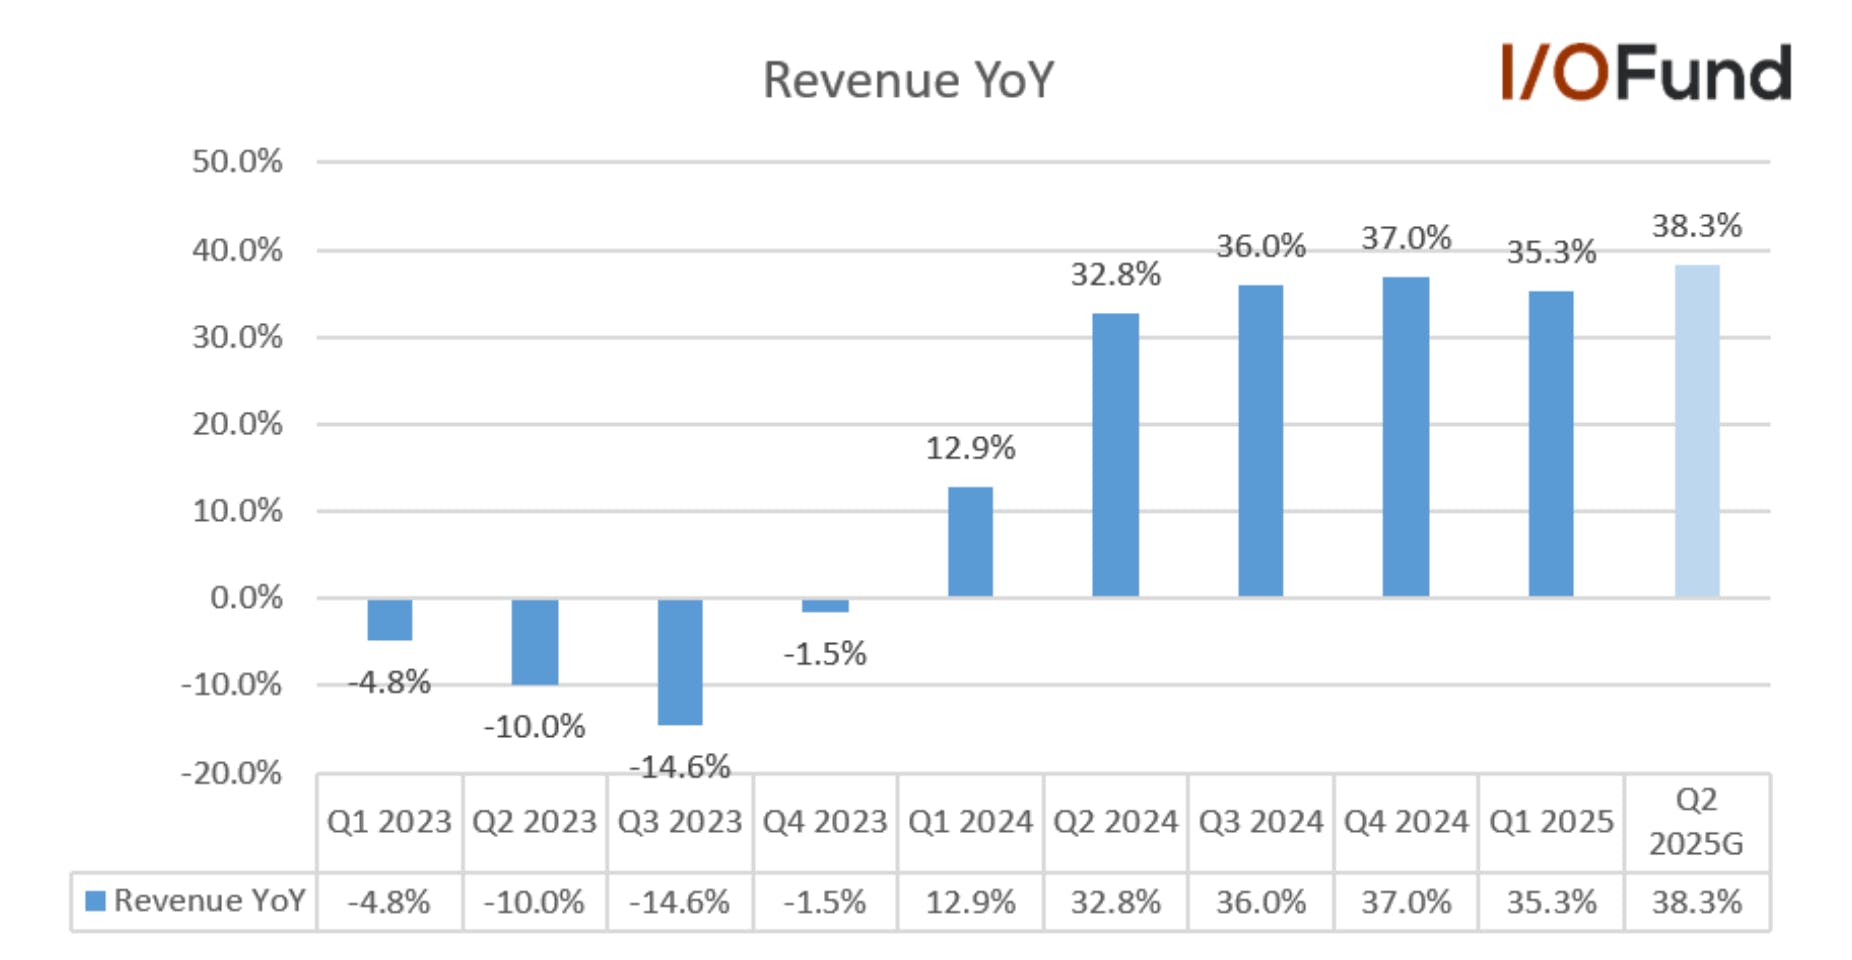
The company is off to a good start for the year with revenue growth of 35.3% YoY while guiding for an acceleration to the 38% range in Q2. Revenue was down (5.1%) sequentially, impacted by smartphone seasonality, partially offset by AI-related demand growth. However, the Q2 guide represents 13% QoQ growth with revenue between $28.4-29.2 billion.
TSMC offers monthly reports with April starting Q2 off strong as monthly revenue surged 48.1% YoY and 22% MoM to ~$11.55 billion, with Bloomberg stating the outperformance could be due to a rush in pre-tariff ordering, although certainly 3nm and 5nm demand helped as well.
This year, IDC is forecasting Foundry 2.0 will grow by 11% compared to 6% last year. Foundry 2.0 describes a broader range of foundry technologies, with the foundry segment expected to grow 18% down from 20% last year.
Regardless of which way you dice it, TSMC is guiding for above industry growth, stating in the most recent quarter: “we continue to expect our full-year 2025 revenue to increase by close to mid-20s percent in U.S. dollar term.”
Of this, AI accelerator revenue is expected to double in 2025 and management also forecasts AI to grow at a mid-40% CAGR for five years from 2024: “Based on our planning framework, we are confident that our revenue growth from AI accelerators will approach a mid-40s percentage CAGR for the next five years period starting from 2024.”