
This post originally appeared on FATrader.com on April 16th, 2019. Beth later appeared on Yahoo Finance discussing this analysis. This post originally appeared on FATrader.com on April 16th, 2019. Beth later appeared on Yahoo Finance discussing this analysis. appeared on Yahoo Finance discussing this analysis.
This may be hard to believe, but on Thursday, Silicon Valley will have a company go public that is already profitable. If you’ve used Cisco’s Webex for meetings, then you’ll understand Zoom. The company provides web conferencing that is simple for users to join and has a lot of features to assist in virtual meetings.
Zoom has a “bottoms-up” viral customer base, which means junior employees evangelize the service at the company. These are often some of the most loyal customers. For instance, 55% of $100,000 or higher revenue customers were started with a single employee’s free trial.
Financials
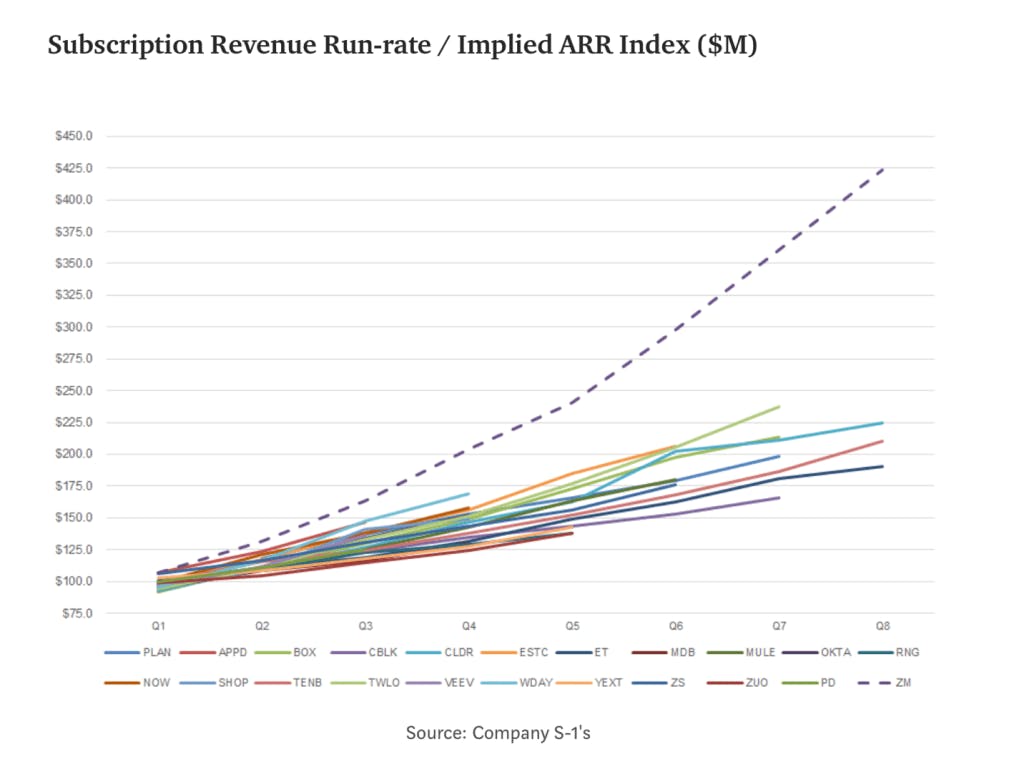
Zoom’s financials outperform successful software-as-a-service companies on the public markets today, such as Workday and Okta. Here’s a snapshot of the S-1 Filing showing $60M in revenue in 2017, $151M in revenue in 2018 and $330M in revenue in 2019. The company has been posting 100%+ revenue growth for three years with gross profit margins in the high 70% to low 80% range compared to more mature SaaS companies currently on the public market posting increasing net losses (Okta and Workday).
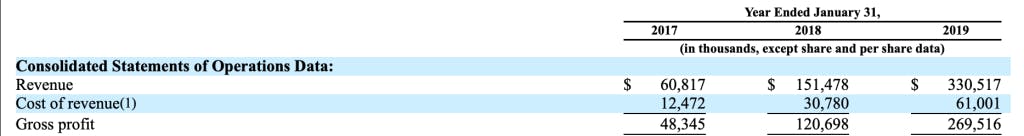
In the year ending January 31st, 2019, Zoom became profitable with $7.58 million in net income or 3 cents EPS. The year prior, Zoom posted a net loss of $4.8 million. Compare this to Okta’s net loss of $125M on similar revenue this past year or Workday’s net losses of $418M on approx. $2.8B revenue.
Zoom’s IPO price continues to change daily. The shares are now being priced 8 percent higher than previously estimated last week with a valuation around $9 billion. This is up 9x from the company’s most recent private funding round, which was priced at a $1 billion valuation. SalesForce Ventures has agreed to buy $100 million Class A stock at the IPO.
Zoom has disrupted Cisco’s WebEx, which is clunky and more intensive software for video conferencing. Some Wall Street analysts have speculated Cisco and Microsoft are a threat to Zoom, although the opposite is true.
Zoom’s CEO Eric Yuan, owns 19 percent of the stake in the company, and was a former engineer at WebEx before it was acquired by Cisco. On a similar note, I would not be surprised if SalesForce acquired Zoom given its large stake and the loyal customers Zoom could bring to a predominant SaaS platform. Yuan has adamantly stated he would not sell a company after his experience with the WebEx acquisition, although this may be too idealistic for a standalone conferencing product. Long story short, it is likely Zoom will agree to an acquisition in the future.
SaaS Metrics
There is a breakdown of Zoom by venture capitalist Alex Clayton of Spark Capital. It bears mentioning that many of the software-as-a-service VCs support one another in public offerings and Clayton is a little too enthusiastic about Zoom. However, Clayton does a good job of visualizing the data. I’ll summarize some of what he says here and point out a few things you should consider when looking at the data that comes from the VC side.Spark Capital. It bears mentioning that many of the software-as-a-service VCs support one another in public offerings and Clayton is a little too enthusiastic about Zoom. However, Clayton does a good job of visualizing the data. I’ll summarize some of what he says here and point out a few things you should consider when looking at the data that comes from the VC side.