Productivity

How to pick long-term stock winners in cloud computing

Written by

Beth Kindig

Founder, CEO and Lead Technology Analyst

Published: September 13, 2019

Last Updated: September 13, 2019

Cloud software stocks suffered a reversal that has produced losses of close to 50% from record highs.

The story for those stocks hasn’t changed, but the valuations have, and that could be a good thing for investors who know what they own.

The biggest risk for investors in cloud stocks isn’t the losses that have pummeled prices over the past two weeks, but rather the big reversal that may scare them away from the sector. It’s painful to watch large declines in stocks, yet nobody wants to miss out on a potential 10-bagger either. When the market rewards, and penalizes, all cloud software stocks equally, with little differentiation, it’s prudent to choose a select group that has compelling stories for a buy-and-hold strategy.

An investing adage is to buy when others are fearful. I would say to buy when others can’t differentiate among companies. Clearly, from what we saw over the past two weeks, a broad range of companies are being lumped together, with little recognition as to which are the winners.

To put it simply, this is a great time to know what you own as the story for these stocks is much deeper than the simple descriptor of “cloud software.”
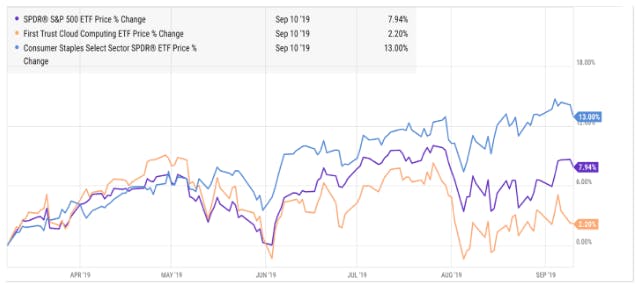
In the graphic above, the orange line represents the First Trust Cloud Computing ETF SKYY, +0.12% which holds about 60 positions, all of which dominate the cloud space. The light-blue line is the Consumer Staples Select Sector ETF XLP, +0.41%, which tracks the consumer staples sector, a group that’s thought to be impervious to recessions. Those have historically been the laggards in this long, growth-driven bull market. The dark purple line is the benchmark S&P 500 Index SPX, +0.29%.

Before the stock market correction in May, cloud stocks were the leader in the market, while the staples were trailing. However, since that first correction, and up till today, there’s been a reversal. Over the past week high-growth leaders in this bull market, mostly cloud, have taken big hits.

For example:

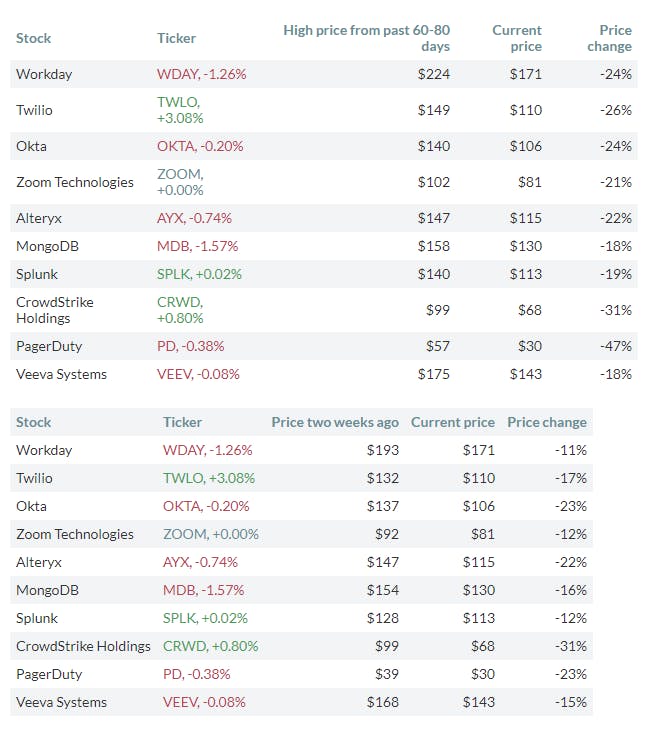
Workday WDAY, -1.26% is down 25% from its high. Twilio TWLO, +3.08%, down 26%. Okta OKTA, -0.20%, down 22%. Zoom ZM, +1.02%, down 27%. MongoDB MDB, -1.57%, down 29%. PagerDuty PD, -0.38%, down 47%. (All prices are current as of 2 p.m. Eastern time Sept. 11.)
Cloud software categories

To start, cloud software needs to be broken up into categories to look more closely at the markets they serve. Here are some examples:

• Twilio is at the intersection of communications and mobile.

• CrowdStrike CRWD, +0.80% and Okta are security companies.

• PagerDuty simplifies operations, and Workday simplifies human resources and the finance department.

• Alteryx AYX, -0.74% and Splunk SPLK, +0.02% are big data analytics.

• Salesforce CRM, +0.43% is customer relationship management (CRM), but the market it serves is the sales and marketing industry.

• Zoom simplifies communications for enterprises and business-to-business (B2B), as does Slack WORK, +1.47%.

• Veeva Systems VEEV, -0.08% serves the life sciences and pharmaceutical industry.

Twilio has more in common with Skype, and even Verizon VZ, +0.50% and AT&T T, -0.93%, than it does with Okta. Workday has more in common with SAP and Oracle ORCL, -4.26% than it does with Alteryx. Yet, cloud stocks experienced a categorical black swan as if they all serve the same markets.

What this means is that some investors don’t understand these companies. The viability of a company’s product and how it fits the market is not factored into the investments, and this is creating a window of opportunity for investors who take the time to study individual stocks.

Valuations

The more logical explanation is that there was a clearance sale for overpriced stocks, and the common denominator in the sell-off was high valuations. However, the issue with this theory is that some of the companies will go on to be big winners, and higher price-to-sales (P/S) or enterprise-value-to-sales (EV/S) ratios are warranted because of the enormous markets they serve in contrast with their small size.

For instance, Zoom’s P/S and EV/S are gut-wrenching (no argument there), but the company’s revenue growth is unusual. You’d be hard-pressed to find triple-digit revenue growth for eight straight quarters in the stock market. The prospects of disrupting Cisco and other enterprise telecommunications at a $22 billion market cap is worth more than other companies that are serving smaller, more saturated markets. Zoom’s rapid growth, which is unprecedented, makes it hard to pinpoint a fair valuation.

Beth Kindig, founder and lead tech analyst of I/O Fund

Get Our Free Weekly Stock Newsletter

Get weekly stock insights, market analysis, and technology updates straight to your inbox.

  • Weekly stock insights
  • Market analysis
  • Technology updates

Workday is another example of a company that carries high P/S and EV/S ratios, in this case twice as high as its large competitors, Oracle and SAP. In this scenario, you get a pure-play option that is moving quickly on machine learning to reduce the overhead required in human resources and finance departments. What Workday’s software aims to do, which is to reduce the number of employees needed in those departments, delivers a value that is worth many times over the cost of the software. If Workday is successful, the company will be worth much more than two times its current market cap, whereas, Oracle and SAP are essentially defending territory.

See: Beth Kindig runs a forum on tech stocks where she answers readers’ questions.

Splunk has P/S and EV/S ratios of eight compared with Alteryx’s 24 and 22, respectively, yet both were affected by the sell-off despite being in similar markets. Splunk should have held steady if this was a clearance sale on high valuations.

The evidence doesn’t point to a rational reason for the sell-offs. Some stocks are priced high, but knowing which ones deserve to be is going to be more important than ever.

Also Read: Okta Earnings: More to Squeeze From Valuation?

How to evaluate cloud software

• The larger the market, the safer the investment. Can every enterprise employee in the world use the product for maximum scale? Does the product solve a pain and reduce overhead for businesses? These will outlast the more niche markets and products that are considered a convenience. To illustrate, if you are providing software for office communications that replaces office telecom equipment, not only is your product a necessity but it will be the solution to high telecom bills during a time when costs are being cut. There are numerous examples of fulfilling a (non-negotiable) necessity while reducing costs in the cloud software category.

• Ignore earnings estimates. Many estimates were lowered this past year, and when companies “beat” earnings estimates, they were actually declining year-over-year, sometimes substantially. Apple AAPL, -0.23% is a prime example of this. The stock continues to reach all-time highs and “beat earnings” despite two straight quarters of negative growth and mere 1% growth in the most recent quarter. That may work for Apple, but smaller-cap companies that are declining won’t last long, especially in a value rotation. Another example is Okta, which I believe had weakening fundamentals yet beat earnings estimates. Okta is now one of the hardest-hit cloud software stocks over the past two weeks, with a 22% drop since the end of August.

• We hear a lot about competitive moats, yet high switching costs is a protective buffer that serves two purposes: It locks in subscription revenue and staves off competitors. Often, switching from a cloud software provider will cost a customer time and resources. Look for companies that have high switching costs.

My prediction is this may be one of the last cycles when tech is considered less safe than value stocks. As the market will find out (the hard way), cloud software is actually very safe. It is insulated from trade wars and overseas manufacturing issues. It reduces costs for enterprises, which is ideal for a recession. Lastly, cloud software is at the beginning of a rapid growth cycle compared to its counterparts in tech — such as mobile, e-commerce and advertising — which are reaching saturation, are finding themselves in the cross hairs of anti-trust and are susceptible to consumer spending changes.

The best companies in the category of “cloud software” will continue to post rapid growth regardless of economic conditions, and the investors who run from this sector will suffer bigger losses from missed opportunities than investors who know their winners.

This article appeared on MarketWatch September 12th, 2019.MarketWatch September 12th, 2019.

About the author

Beth Kindig

Beth Kindig

Profile

Beth Kindig is the Founder, CEO and Lead Technology Analyst at I/O Fund, with more than 15 years of experience covering private and public technology companies. Known for her early Nvidia research beginning in 2018 and bold, high-conviction calls on emerging technology trends, Beth also manages I/O Fund's audited technology portfolio, which has returned 326% since May 2020, or 29.2% annualized. She is a regular guest on Fox Business and Bloomberg and has appeared on Real Vision, CNBC, Yahoo Finance, BBC, MarketWatch, Forbes, and more.

Curation

Expand your knowledge

View all posts
AMD Stock: Two-Catalyst Punch Leads to 80% Growth Next Year
SEMICONDUCTOR STOCKS

AMD Stock: Two-Catalyst Punch Leads to 80% Growth Next Year

In August, our premium article "Venice Meets Helios" pointed to two strategic product releases that were arriving soon - AMD’s Venice CPUs and the highly anticipated Helios MI400 Series. At the time, management expected server CPU revenue to grow more than 70% in 2027, while total Data Center revenue would grow “well over 100%,” driven by the Helios ramp. Three months later, AMD has raised its outlook considerably, and the two product ramps are now exceeding the I/O Fund’s original expectations. Server CPU revenue is now expected to more than double in 2027, up from the previous outlook for 70%+ growth. Meanwhile, Data Center AI revenue (GPUs) is expected to significantly more than double.

SEMICONDUCTOR STOCKSNOV 13, 2026
Nvidia Says Capacity Is the Constraint: 3 Bottlenecks Holding Back the AI Buildout
AI STOCKS

Nvidia Says Capacity Is the Constraint: 3 Bottlenecks Holding Back the AI Buildout

Nvidia has signed capacity agreements with six key suppliers for chip parts and has a new design to build AI data centers, even as CEO Jensen Huang points out extraordinary demand amid capacity constraints. However, grid power remains the limit Nvidia can’t fix on its own.

AI STOCKSNOV 13, 2026
Data Centers in Space: Google Runs AI on 1 kW in Orbit as SpaceX Bets on Orbital Compute
DATA CENTER

Data Centers in Space: Google Runs AI on 1 kW in Orbit as SpaceX Bets on Orbital Compute

Google ran AI in orbit on about 1 kW. SpaceX plans 250 kW satellites. A 1 GW campus on Earth uses 1,000,000 kW. We take a deep dive into what it takes to put data centers in space.

DATA CENTERNOV 12, 2026