
This article was originally published on Forbes on Sep 3, 2020,11:33pm EDTForbes on Sep 3, 2020,11:33pm EDT
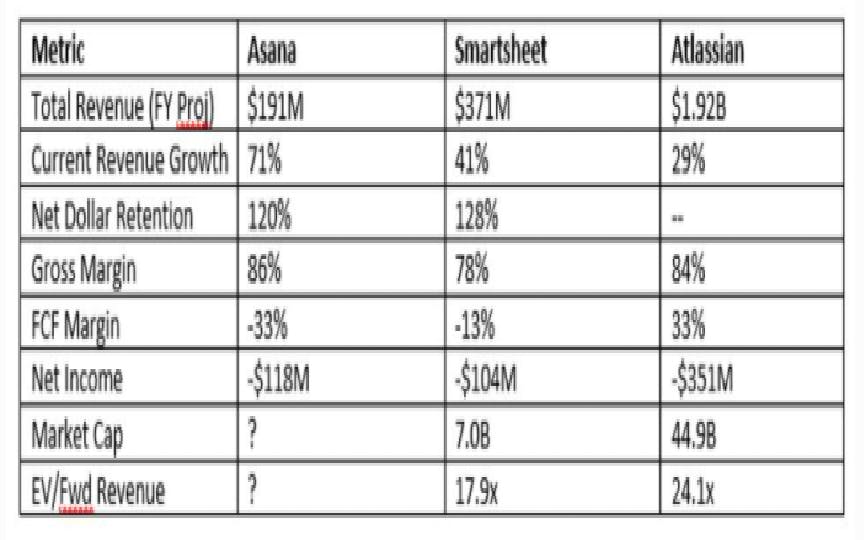
When considering if I should buy into a SaaS public offering, my first thought is the company better be special because there are some very solid choices already on the market. Despite Asana having investable growth, the company may be in too-crowded of a space for the size of the addressable market. This is evident in the widening losses and the need to double R&D and sales and marketing to keep their revenue growth competitive. Furthermore, in the most recent quarter, there was notable deceleration in revenue from 86% for the fiscal year to 71% year-over-year in the April quarter. Below I go over some of Asana’s strength and the maximum valuation I’m willing to pay.
History of Asana:
Asana was founded by Dustin Moskovitz, who is best known for co-founding Facebook with his Harvard roommate, Mark Zuckerberg. Asana filed its S-1 last week and is expected to list directly on the NYSE in late September. The company ranks at No. 17 in this year’s Forbes Cloud 100, the annual ranking of the world’s top private cloud-computing companies, up from No. 41 a year ago.
Asana is workplace collaboration and planning software that is designed to help teams orchestrate their work so they can achieve their goals more efficiently. The company’s software is used by more than 75,000 companies including AT&T, Google and NASA. Asana has 1.2 million paid users and an additional 3.2 million free activated accounts, according to the filing
The product provides teams with effective tools to coordinate their workflows and increase productivity. According to Asana’s filing, 28% of work time is spent answering emails, 19% is spent gathering information, and 14% is spent on internal communication.
Citing IDC data, the work management market that Asana addresses is expected to grow from $23B in 2020 to $32B in 2023. The company believes they have the opportunity to reach 1.25 billion global information workers and that their existing customer base represents less than 3% penetration of the total addressable market. Forrester research has listed Asana as one of three leaders in the collaborative work management space. You can view this here.
Notably, there are many competitors missing from the evaluation, for example Atlassian and Jira, Basecamp, Trello, Click Up, Pivotal Tracker – plus Salesforce with its project management applications.
Financials
For fiscal 2020, Asana’s revenue came in at $142.6 million, representing growth of 86% YoY. In its most recent quarter ending April 2020, Asana recorded 71% YoY revenue growth. The company also saw its losses grow from $50.9 million in 2019 to $118.6 million in fiscal 2020.
In its most recent quarter, net losses grew 138% year over year. The increase in losses can be attributed to the company more than doubling its spending on research & development as well as sales & marketing.