
This article was originally published on Forbes on Sep 11, 2020,03:02am EDTForbes on Sep 11, 2020,03:02am EDT
Snowflake is the most anticipated IPO of the year. Investors should decide in advance how much they are willing to pay as Snowflake will test the upper limits of what it means to have a stretched valuation. Heck, the company has even inspired value-legend Warren Buffet to change his thesis and invest in an IPO prior to profitability (!)
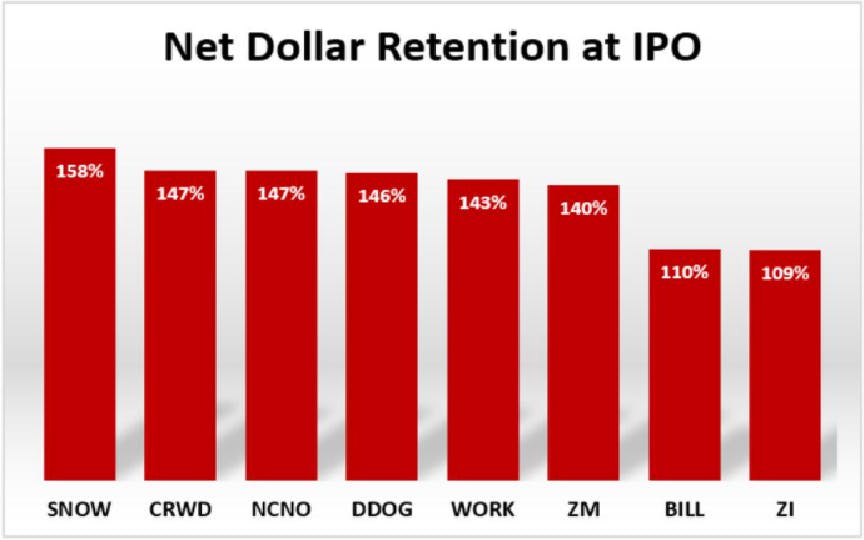
Perhaps because the company delivered sky-high revenue growth last fiscal year of 173% and 121% in the most recent quarter with a record-breaking net retention rate of 158% — which is the highest of any public cloud company at time of listing.
David Marlin
These industry-leading numbers are due to the company disrupting the data warehousing market with a superior cloud data platform that delivers across key differentiators (we review this below). Despite Snowflake demonstrating excellent product-market fit, clear competitive advantages, and strong management — no company is perfect. We go over a few key risks that investors should keep in mind as the bidding becomes fierce on opening day.
Snowflake Financials
Snowflake has strong financials for a tech IPO, yet it’s important to remember the product has been available for only six years and tech growth is typically strongest in the early days. The company delivered 173% growth in the fiscal year ending January 31, growing from $96.7 million to $264.7 million with gross profit margins of 56.2%.
These gross margins are below what cloud companies are capable of yet improved in the most recent period. Revenue grew 133% year-over-year in the first six months of fiscal 2021 ending in July, growing from $104 million to $242 million with improving gross profit margins of 61.5%.
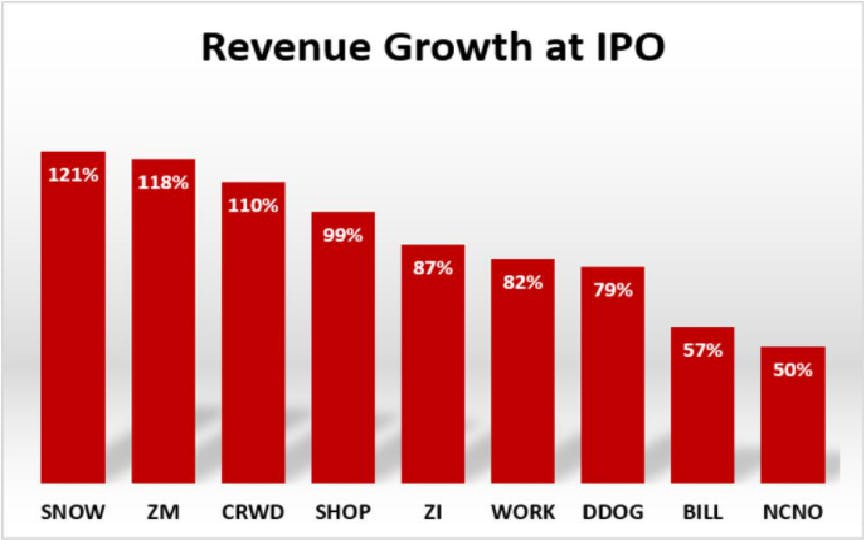
In the most recent quarter, the company reported growth of 121%. Here, we already see the effects of age within a short time period as Snowflake settles from 173% growth to 133% growth and now to 121% growth. This is not a negative by any means (triple-digit growth is to be celebrated) but keep in perspective it’s age when comparing Snowflake to any high-growth cloud SaaS peers.
David Marlin
The bottom line has been varied depending on what period you look at. The losses doubled from fiscal year 2019 with net losses of $178 million increasing to net losses of $348.5 million in fiscal year 2020.
More recently in the first six months of fiscal 2021, the net losses were flat period-over-period at $177.2 million compared to losses of $171.3 million. This could be an encouraging sign or it could be Snowflake tightening the belt temporarily for the public offering before returning to the original pace of worsening losses. There is not enough history to know if the more encouraging flat rate of losses is sustainable. Adjusted EPS was negative $1.63 in the fiscal year ending in January compared to negative adjusted EPS of $0.72 in the first half of fiscal 2021.
Sign up for I/O Fund's free newsletter with gains of up to 403% - Click hereSign up for I/O Fund's free newsletter with gains of up to 403% - Click hereClick here
Net retention rate for Snowflake is a record 158% — the highest of any company when going public. However, it’s important to remember that net retention rate lowers over time as customers become harder to retain long-term (I cover net retention rates more in-depth here).
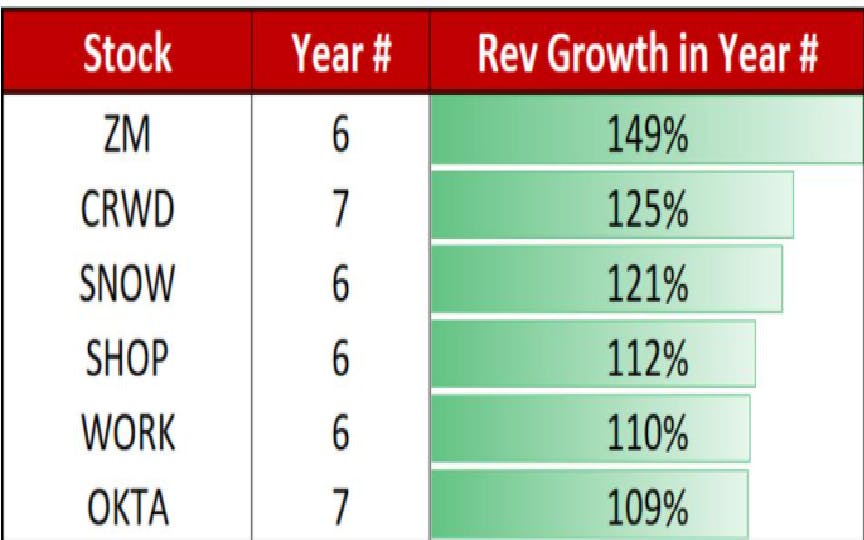
The company was founded in 2012 yet the product came out of stealth mode in 2014. When considering the product launch, Snowflake is a very young company of only six years old.
David Marlin
You can see evidence of how net retention is affected by number of years in Snowflake’s S-1 filing as the company had a rate of 223% in the first half of 2019 compared to 158% period-over-period. Annually, the company lost 11 percentage points in net retention rate from 180% to 169%.
SNOWFLAKE S-1 FILING
Regardless, Snowflake has impressive numbers. Perhaps the most impressive key metric in the S-1 filing is the growth in the percentage of customers with product revenue greater than $1 million. This has grown considerably from 14% in fiscal year 2019 to 41% in fiscal year 2020. There is evidence high-end accounts are continuing to grow with the first six months of 2020 at 56% compared to 22% in the year-ago period.
The new CEO, Frank Slootman, clearly knows how to make a company attractive to investors. Not only did the company quicky tighten its belt in regard to net losses, the company also doubled customers from 1,547 to 3,117 over the past twelve months. This includes 7 of the Fortune 10 and 146 of the Fortune 500.
Cash used in operating activities decreased from $110 million to $45.3 million in the first six months of fiscal 2021. The company has cash and investments of $591 million and no debt.
As outlined in the S-1, IDC places the addressable market for Analytics Data Management and Integration Platforms and Business Intelligence and Analytics Tools at $56 billion in 2020 and $84 billion in 2023.
In an effort to narrow this addressable market, I dug up a few more sources. According to MarketsandMarkets, the addressable market for Data Warehouse-as-a-Service is much smaller at $1.2 billion in 2018 and set to grow to $3.4 billion by 2023 at a CAGR of 23.8%. P&S Intelligence reports a similar CAGR of 29.2%, estimating the Data Warehouse-as-a-Service market to reach $23.8 billion by 2030. When combining on-premise, Allied Market Research places the data warehousing market at $34.7 billion by 2025.
You’ll find larger addressable markets in tech but the weight Snowflake brings to the category is considerable.
Snowflake’s former CEO, Bob Muglia, grew the company from 80 customers in 2015 to 1000 customers in early 2018 when he was replaced by Frank Slootman. The change likely happened due to pressure from private investors who want a grand slam exit (and looks like they’ll be getting just that).
Slootman is known for resuscitating Data Domain from nearly running out of money in 2003 to an acquisition in 2009 after the company “grew to sell more than all its competitors combined.” This was detailed in a book that Slootman wrote called: “TAPE SUCKS: Inside Data Domain, A Silicon Valley Growth Story.” Three years later, Slootman took over the CEO role of ServiceNow between 2011 to 2017 and grew the company from $75 million in annual revenue to $1.5 billion. This was achieved by diversifying the product beyond the IT department.
For many investors, management is a key factor in deciding to invest or not. Here, Snowflake fires on yet another cylinder.
Product:
Snowflake’s decoupled architecture allows for compute and storage to scale separately with the storage provided from any cloud provider the customer chooses. By processing queries using massively parallel processing (MPP), where each node in the cluster stores a portion of the data set locally, the virtual warehouses can access the storage layer independently so as not to compete for compute power. With the competitors, such as Redshift, where compute and storage are coupled, more time is spent reconfiguring the cluster.
Snowflake calls this offering a virtual data warehouse where workloads share the same data but can run independently. This is crucial because Snowflake’s competitors combine compute and storage and require customers to size and pay based on the largest workload.
Data warehouses are centralized data repositories that collect and store information across many sources that are both internal and external. The raw data is ingested into the data warehouse and processed to answer queries. To ingest data, warehouses follow the ETL process, which is: (1) Extract the data from the internal or external database or file, (2) Transform by cleaning and preparing the data to fit the schema and constraints of the data warehouse and (3) Load into the data warehouse. The ETL method helps to organize the data into a relational format. Notably, Snowflake supports both ETL and ELT, which allows for data transformation during or after loading.
One key product differentiator is that Snowflake is not built on Hadoop, rather the company uses a new SQL database engine with cloud-optimized architecture. Overall, this translates to faster queries and also reduces costs by scaling up or down for both capacity and performance. This also allows the shift to the cloud while still honoring traditional relational database tools. Just like cloud infrastructure does not require you to hold server space for peak times year-round, a cloud data warehouse does not require you to plan, acquire or manage resources for peak data demand (i.e. elasticity).
The need for resources could change by either increasing or decreasing (scaling up or down). Customers that have a need for storage but less of a need for CPU computations do not have to pay up front and can shrink the environment dynamically. Users either pay for terabytes or are billed on a per-second basis for computations. Notably, Snowflake charges by execution-based usage and is not a cloud SaaS-company that charges by subscription.
Snowflake has a multi-cluster architecture which is unique from single cluster databases. The multi-cluster approach allows the clusters to access the same underlying data yet to run independently. This allows for heavy queries and operations to run very quickly and with fewer errors because the queries are not accessing the same data warehouse.
Queries are made with standard SQL, for analytics, and integrates with R and Python programming languages. The company delivers the ability to handle all incongruent data types in a single data warehouse. Because the data is accessible through SQL, there is widespread developer uptake as it’s the most common database language.
Snowflake supports both structured data and semi-structured data. As machine-generated data grows to include applications, sensors and mobile devices, Snowflake allows semi-structure data to be handled without preparation or schema definitions. The result is handling JSON, Avro, ORC, Parquet or XML data as if it were relational and structured.