
Debuting in 1980, Apple is nearing its 40th anniversary on the stock market. The company has undergone many pivots successfully from computers to improved operating systems, to iPods, iPhones, app stores and music services. Many of these pivots were executed beautifully, with the most recent one being Apple Music, which took a majority of market share in music streaming within 4 years in the United States.
Of course, the iPhone is Apple’s force extender. One quick glimpse at the stock chart history and it’s easy to see something important happened in 2008. The invention has sold over 2.2 billion units with an average price tag of $793. The iPhone altered the United States economy, creating a thriving developer ecosystem while 87 percent of smartphone profits despite selling 18 percent of all smartphone units. With the iPhone’s release, Apple not only became one of the biggest companies in the world, but it also has more cash reserves than most countries’ GDP at $285 billion.
There are many positives to Apple’s story beyond the iPhone, with a wearables business up over 50%, cloud services up 40%, and Apple News readership at 85 million active monthly users. Apple Music is also now the number one streaming service in the United States over Spotify and closing the gap globally with 53M subscribers vs 83M subscribers. Most importantly, Apple has a media announcement planned for March 25th, which will add to the growing services revenue.
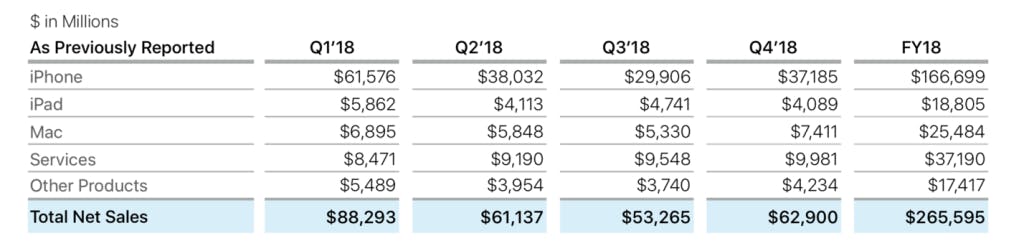
Earnings reported on January 29th, 2019 were more encouraging than anticipated following the lowered guidance. Apple beat earnings at $4.17 compared to last years $3.89. Total revenue was lower at $84 billion, down by 4.51% and beat guidance by $312 million. Future guidance expects revenue between $55 billion and $59 billion for this quarter to be reported at the end of April. Gross margins are expected between 37 percent and 38 percent. The company has a hoard of cash and the stock pays an increasing dividend.
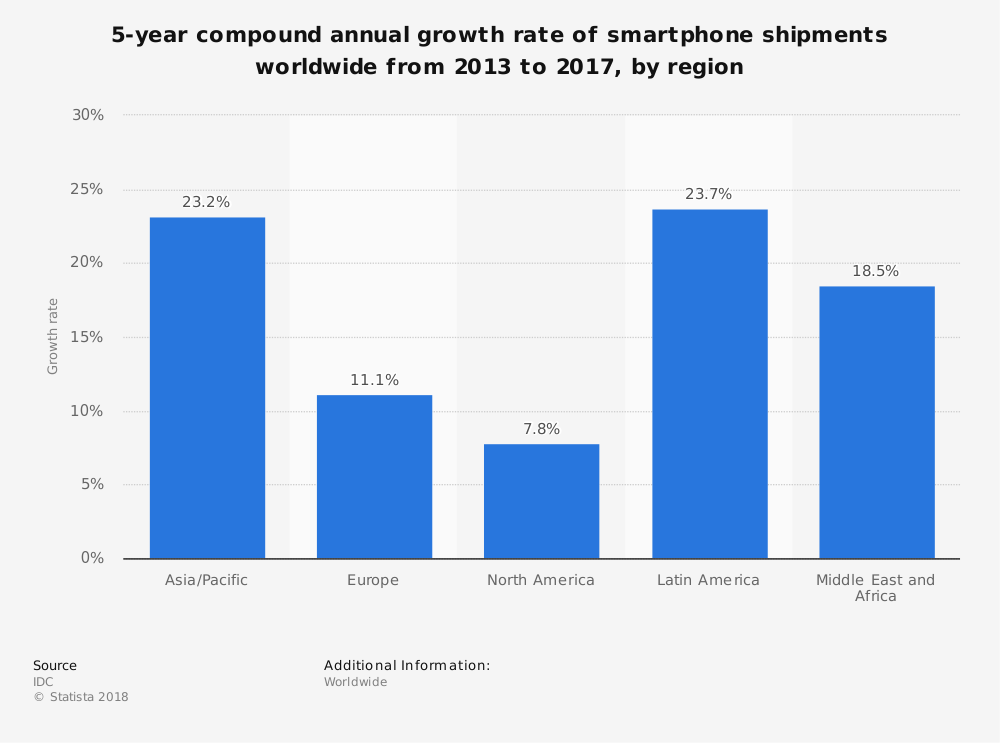
Investors should exercise caution, however, as the broader mobile market is slowing down and is at the point of saturation. Mobile has been the de facto leader for tech growth during this historical bull market, and has provided consistent YoY returns that the dot-com bubble would be envious of. Investors should recognize mobile has reached its top as a primary driver across tech growth stocks, and I do not believe the mobile slowdown is over yet, or that the full effects have been completely reflected in earnings.
Apple can (and will) pivot. One day, the company will be known for health services, vehicle software, as a media titan, and more. However, But to expect one quarter of decreasing iPhone sales before the stock resumes previous heights would defy the laws of the tech hype cycle. Apple simply has not hit the iPhone bottom, and the effects of mobile saturation are not fully reflected yet in the company’s earnings.
The Fifth Factor: Mobile Saturation
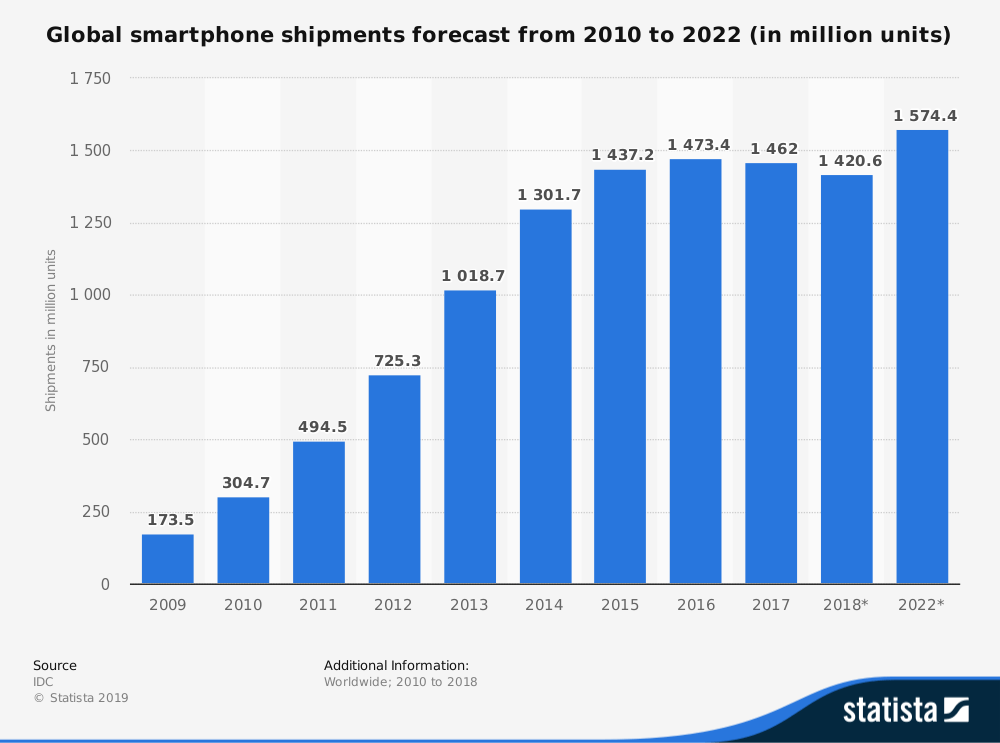
Apple noted four factors that impacted results when the company provided guidance in November: “different iPhone launch timing from a year ago, FX headwinds, supply constraints on certain products and macroeconomic conditions in emerging markets.” I would call this the 1,000 foot-view while the 30,000 foot-view tells us the fifth factor is mobile saturation. Eventually, everyone has a television set and a laptop – and now, a smartphone. This will continue to be the reality that Apple contends with.source: https://www.statista.com/statistics/263441/global-smartphone-shipments-forecast/
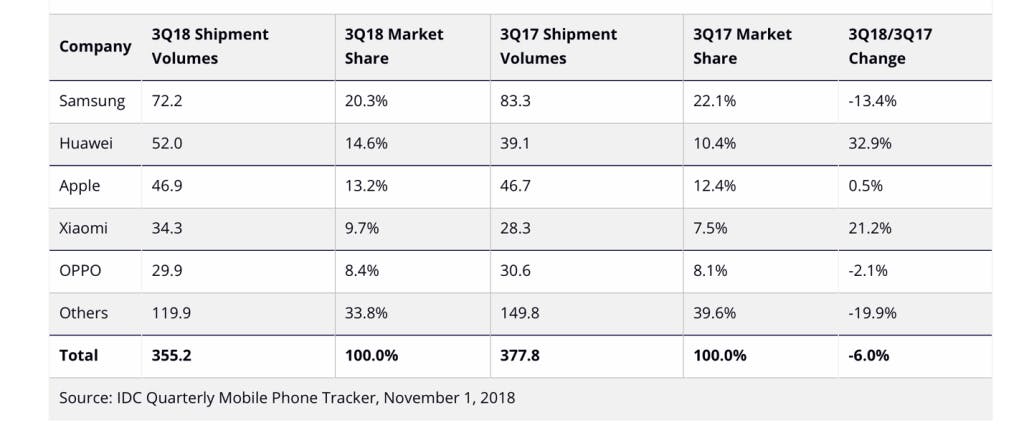
The smartphone market contracted in 2017 to 1.462 billion units and in 2018 to 1.42 billion units, and is expected to return to minimal yet positive growth percentages at a CAGR of 2.5%. While 1.5 billion smartphones per year is substantial, the law of saturation is likely to drive prices down, with Android owning 85% of the market today, and we see decreasing iPhone penetration in China where lower-priced competitors gain market share.
IDC estimated Apple will sell 242 million smartphones by 2022 up from 221 million in 2018. The issue with these estimates is that IDC does not break down the percentage of potential decline between 2018 to 2022. The most up to date number available from IDC is an anticipated decline of 0.8% in worldwide smartphone sales in 2019, published on March 6th.
We saw China decline 10% last year in global shipments of smartphones. Taiwanese company, TSMC, is the sole supplier of iPhone core processor chips and told Nikkei Asian Review that the company is cautious about demand for high-end smart phones, which is a nod toward Apple from a main supplier. Samsung Electronic’s Vice President Lee Myung-jin told investors in late January that “demand for memory chips has declined in the fourth quarter as external circumstances worsened and customers adjusted their orders” and he believes the decline “will continue in the first quarter, as key customers keep adjusting their orders.”