Tech Stock News

Will We See Another Dot-Com Crash In Tech?

Written by

Beth Kindig

Founder, CEO and Lead Technology Analyst

Published: June 5, 2020

Last Updated: June 5, 2020

This article was originally published on Forbes on May 15, 2020,12:42am EDTForbes on May 15, 2020,12:42am EDT

Tech’s comeback since March has been nothing less than spectacular considering the backdrop of record unemployment and contracting GDP. According to a survey of fifty companies by FactSet, 60% had withdrawn guidance for the year. FactSet also estimates that the S&P 500’s earnings for 2020 have fallen 22% since the beginning of the year, while 2021 earnings have declined 13%.

Meanwhile, many tech stocks have reached all-time highs including one-day moves of up to 40% even when companies withdraw guidance. Twilio, for instance, rallied from $122 to $170 based on an 11% revenue surprise with total returns of 140% in the past two months. Twilio is hardly the exception with Teladoc up 115% and Fastly’s one-day move of 40% on May 7th.

Last month, Goldman Sachs analysts said in a financial note that the S&P 500 index concentration in the top tech companies—Facebook, Amazon, Apple, Microsoft, and Alphabet— was the greatest it has been in 20 years. Meanwhile, these mega-cap companies have reported mixed earnings results (Amazon) or pulled second quarter and full-year guidance (Facebook and Apple).

In a picture, this is what that looks like:
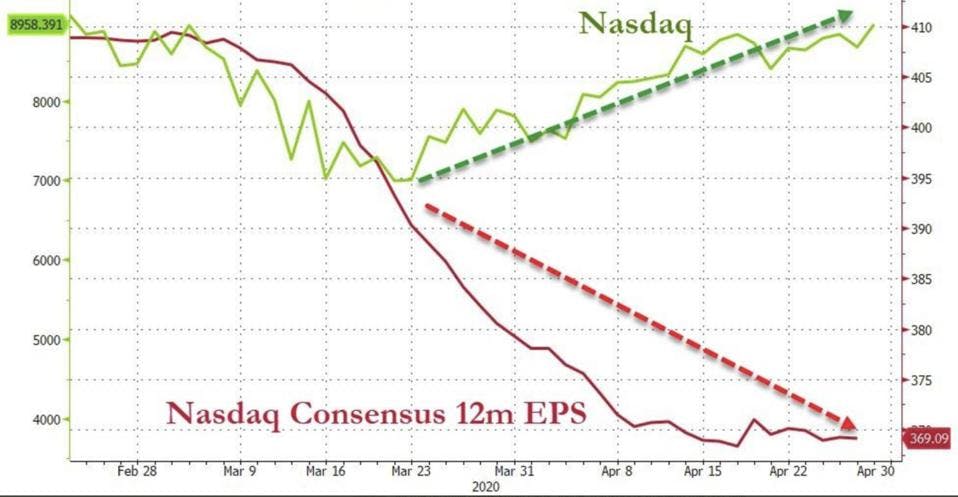
Tyler Durden, Zero Hedge from the article “"Poor Decisions" Galore As Newbie Millennial/Gen-X-ersPour Into Expensive Stock Market: https://www.zerohedge.com/personal-finance/poor-decisions-galore-newbie-millennialgen-x-ers-pour-expensive-stock-market

The saying “history does not repeat but it rhymes” has not yet applied to the dot-com bubble, when five years of euphoria burst into a 78% drop in prices over two years. Tech has largely gone unscathed as it has bumped oil from being the number one industry.

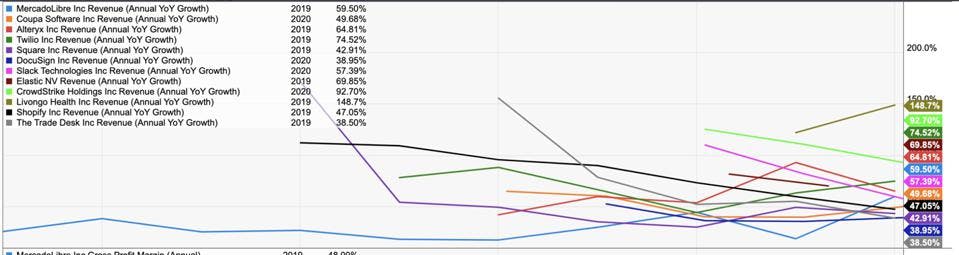
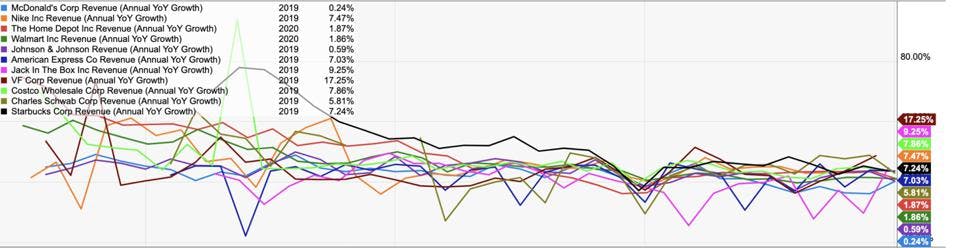
There is some solid support as to why this is not a tech bubble. Mainly, technology now runs nearly every industry. The second reason is that higher valuations are more sustainable today as the revenue growth from tech is much higher than other industries.

Tech Industry Growth has 40-80% growth with outliers up to 148%
TWITTER HTTPS://TWITTER.COM/SAXENA_PURU/STATUS/1256748503050539008

Versus other industries with 1-9% growth with outliers up to 17%
TWITTER HTTPS://TWITTER.COM/SAXENA_PURU/STATUS/1256748503050539008

In addition, cloud software and platforms also allow companies to scale proportionate to revenue growth. There is less overhead and this helps companies keep costs low as you can scale quickly in either direction.

Nearly a decade ago, Marc Andreessen famously said “software is eating the world” in an essay that spelled out how software was disrupting nearly every industry with “real, high-growth, high-margin, highly defensible businesses.” He questioned the low PE ratios of companies like Apple, which at the time was trading at 15 P/E. Notably, Andreessen’s essay came in close proximation to Facebook’s public offering, as well as Zynga, Groupon, Skype and many other exits for his firm’s portfolio.

Sign up for I/O Fund's free newsletter with gains of up to 403% - Click hereSign up for I/O Fund's free newsletter with gains of up to 403% - Click hereClick here

At the time, he pointed out that fast-growing companies like Facebook and Twitter were conjuring up memories of the dot-com bubble in 2011: “With scars from the heyday of Webvan and Pets.com still fresh in the investor psyche, people are asking, “Isn’t this just a dangerous new bubble?”

Beth Kindig, founder and lead tech analyst of I/O Fund

Get Our Free Weekly Stock Newsletter

Get weekly stock insights, market analysis, and technology updates straight to your inbox.

  • Weekly stock insights
  • Market analysis
  • Technology updates

Perhaps just as dangerous as thinking any fast-growing tech company with a high valuation is not a bubble is the idea that any fast-growing tech company with a high valuation is a bubble. This is because the market has a way of doing what you least expect.

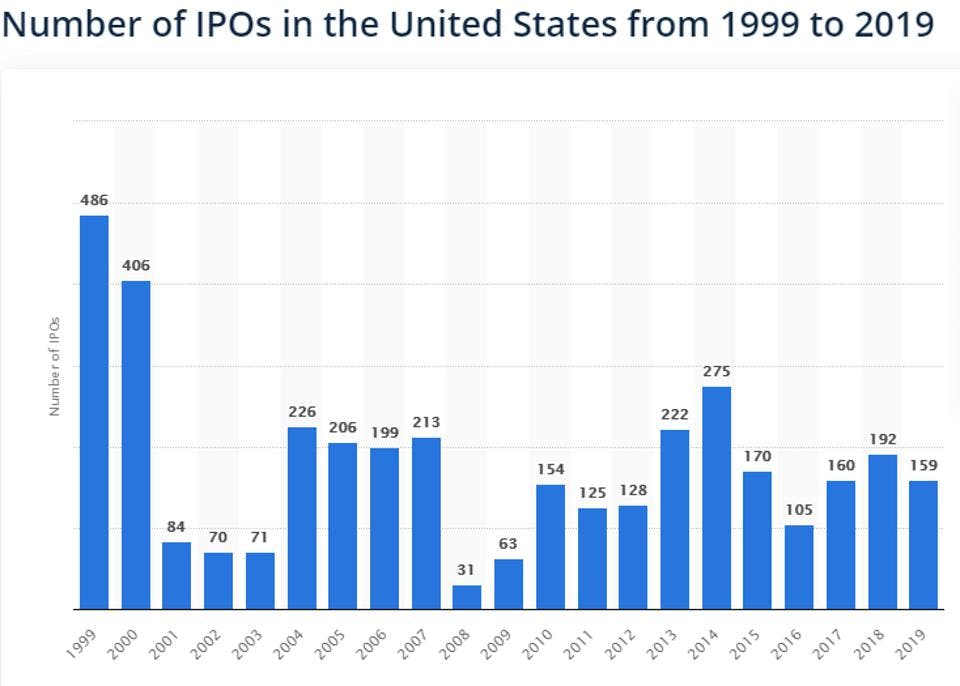
Pre-Pandemic, Silicon Valley Grew Quiet

If looking at the number of IPOs, we are not in a bubble as the years 2018-2019 saw less than half the number of IPOs during 1999-2000.

Beth.Technology

However, the value of IPO exits does look bubble-like. According to Pitchbook, the value of exits for venture-backed companies hit a record $256.4 billion in 2019. 82 venture-based IPOs accounted for 78% of the total value, or $198.7 billion – more than the previous four years combined (this was partly due to Uber and Lyft).

The exits were successful for venture capitalists as the $223 billion in post-money valuations came from $35 billion in venture investment, or a return of 637%. In turn, this means the public markets paid a significant premium.

Also, the years that followed the dot-com bust saw a serious leveling off. It is the absence of early stage deals in tech right now that is more concerning. Pre-pandemic, Silicon Valley was already noticeably quiet.

Forbes also recently reported on the slowdown in venture capital being ill-timed with the effects of the coronavirus forcing many startups to shut down. This followed a 16% drop in venture capital deals in Q4. The CEO of Starsky Robotics stated, “the downpour of investor interest became a drizzle.” As the article points out, the failure rates of 2020 could end up resembling 2001.

Recently, I published on the lack of venture funding in the Series A and Series B stage for tech companies. When combined with the data on initial public offerings from last year, we see a clear signal from venture capitalists that the exit window may be closing (or is already closed).

For instance, as reported by The Information, early-stage software deals in 2019 declined from 388 deals down to 279. In the seed stage, the number was below 200, or the lowest in six years. According to Inc.com and CB Insights, the estimate for Series A funding has dropped from one in three startups to one in six startups with an estimated 1,000 startups not receiving funding this year.

Meanwhile, the public market is flooded with high growth software companies that report over 40% growth due to an inverse law of small numbers. Basically, it’s easier to post rapid growth early-on but harder to sustain this growth.

Conclusion:

Many investors focus on valuations as the indication for a bubble. As pointed out, this can be misleading as hypergrowth companies are often outliers. In fact, the companies that challenge key metrics the most are often the ones that see the most upside. Amazon and Netflix are prime examples.

Valuations aside, there is a glut of high-growth software companies on the market that have not been tested by a less-than-ideal economy or slowing business cycle. This may not create a bubble, but it can create losses for both institutional and retail investors as the market attempts to guess the winners and is confronted by those that fizzle out.

The more that startups shut their doors, as well, the fewer cloud software customers there will be as the two ecosystems are closely intertwined. The recent pullback in March did not afford the opportunity to find the stable winners before hyper-speculation resumed.

About the author

Beth Kindig

Beth Kindig

Profile

Beth Kindig is the Founder, CEO and Lead Technology Analyst at I/O Fund, with more than 15 years of experience covering private and public technology companies. Known for her early Nvidia research beginning in 2018 and bold, high-conviction calls on emerging technology trends, Beth also manages I/O Fund's audited technology portfolio, which has returned 326% since May 2020, or 29.2% annualized. She is a regular guest on Fox Business and Bloomberg and has appeared on CNBC.

Curation

Expand your knowledge

View all posts
Beyond Hyperscalers: Here’s the Next $1 Trillion AI Infrastructure Opportunity
AI STOCKS

Beyond Hyperscalers: Here’s the Next $1 Trillion AI Infrastructure Opportunity

Since 2022, Big Tech capex has been the clearest barometer of AI demand. But the market’s reaction to Google’s latest earnings shows investors are questioning how long that spending can last. While the market frets over hyperscalers’ cash flows, a second wave of AI infrastructure spending has quietly emerged, driven by enterprises and neocloud customers.

AI STOCKSOCT 30, 2026
Google’s $250 Billion AI Chip Opportunity Takes Aim at Nvidia
AI PLATFORMS

Google’s $250 Billion AI Chip Opportunity Takes Aim at Nvidia

In April, there was a major shift in the AI accelerator market, and for once, it didn’t come from Nvidia. Six months later, merchant TPUs are moving from announcement to commercial execution, with Google recognizing its first revenue from TPU systems in Q2 (from a small base). Last quarter, Cloud revenue growth accelerated to 82% for $24.8 billion, compared to $22.5 billion expected. In addition, new details around the TPU 8t show that Google’s threat to Nvidia is not limited to inference. At the time, we pointed out that Google may be one of Nvidia’s strongest AI challengers, as Big Tech is closest to the problems that accelerators must solve. The problem that Google is prioritizing is lower cost per token, with token economics becoming a predominant concern as AI spending is pushing Big Tech’s free cash flows into the red. Below, we discuss two reasons why Google’s AI story is about to change, not from advancements in AI software, but by going after one of the most profitable hardware businesses the tech industry has ever seen.

AI PLATFORMSOCT 23, 2026
AI Debt Nears $500 Billion in 2026: What It Means for Nvidia, Oracle, CoreWeave and AI Stocks
AI STOCKS

AI Debt Nears $500 Billion in 2026: What It Means for Nvidia, Oracle, CoreWeave and AI Stocks

AI-related debt reached $466 billion through September 2026, more than four times last year’s pace. We break down who is borrowing, the three ways new AI chip deals are being structured, and where interest costs land across Nvidia, Oracle, CoreWeave, Broadcom and Big Tech.

AI STOCKSOCT 23, 2026