
Who doesn’t love the ease of using a mobile application to order a ride rather than stand awkwardly on a street corner hailing a taxi? Once I downloaded Lyft and Uber, I said goodbye to the rejection of occupied taxis forever. Lyft and Uber represent free market evolution by offering a better service than the outdated competition. The apps shave off valuable time with door-side pickup, and the overall cost is cheaper than taxis too. In San Francisco, these apps have become ubiquitous, but these biases have to take a backseat to investment discipline.
There is a tinge of glam to the upcoming Lyft IPO road show, and the anticipated IPO from Uber in 2019. Silicon Valley produces a lot of winners; however, I believe investors should be careful with both of these IPOs due to exuberant valuations, accelerating net losses, and a lack of geographic expansion opportunities. Yet, another concern is the liquidity event the large cap IPO provides, and the level of PR that can be bought leading up to the IPO, which will likely focus on the growing sales. There is evidence the growing revenue has been subsidized, therefore, revenue is not a safe bet when evaluating these particular stocks, and the prospectus fails to outline a clear path to profitability.
1. Risky Valuation with Accelerating Net Losses
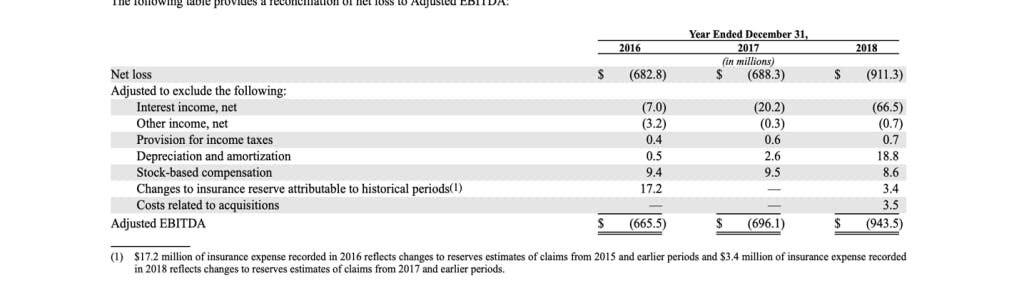
Lyft went from a $7 billion valuation in 2017 to a $15 billion valuation in 2018 and is now seeking a $20-$25 billion valuation on the public markets. The problem with this rising valuation is that losses are progressive with $2.6 billion in revenue in 2018 but a $911.3 million loss. Due to these losses, Lyft may need to borrow or raise more equity after its first year on the public market, which means debt or dilutive stock offerings.
Lyft’s sales, on the other hand, appear positive on the surface with incredible growth year-over-year from $343M in 2016 to $1.05 billion in 2017 and 100%+ growth in 2018 at $2.15 billion. The problem is that the losses are also accelerating.
Lyft’s filing also points to an important issue with growth marketing tactics for user acquisition (UA) and user retention. I’ll copy the paragraph here verbatim from the S-1 Filing and translate my understanding of how ridesharing apps subsidize UA.
“Ability to Cost-Effectively Attract and Retain Riders and Increase Our Share of Their Transportation Spend “Ability to Cost-Effectively Attract and Retain Riders and Increase Our Share of Their Transportation Spend
We grow our business by attracting new riders to our platform and increasing their usage of our platform over time. To effectively attract riders, we focus on driving organic adoption in our rider base, and do so with investments in brand and growth marketing to increase consumer awareness. We also offer incentives for first time riders to try Lyft, as well as incentives for existing drivers and riders to refer new riders. Once riders start using Lyft, we provide a quality experience and a diverse offering of products to accommodate different transportation use cases, retain riders and encourage repeat usage. We often also provide incentives to existing riders to encourage them to expand their use of our platform. If we fail to continue to attract riders to our platform and grow our rider base, expand riders’ usage of our platform over time or increase our share of riders’ transportation spend, our results of operations would be harmed.”
The translation here is that Lyft and Uber pay incentives to acquire and retain users. In gaming, a company might spend $8 to acquire a user with a lifetime value of $15 per user for a profit of $7. The problem with ride-sharing apps is that the incentives offered do not cover the costs of the ride, and that is one reason we see strong sales growth mired by accelerating losses.
Reuters has some historic information on this dated back to 2015, when Uber passengers paid only 41 percent of the actual cost of their trips. At the time, Reuters reported that this creates an “artificial signal about the size of the market” with Uber releasing limited financial data that showed losses of $708 million per quarter.
Going back to Lyft, the takeaway is that these incentives are creating an artificial signal about revenue, which is ultimately overshadowed by net losses. The problem with subsidizing rides is that public market investors aren’t able to determine what will be required for profitability, how much the cost of the ride will have to increase, and if that will impede the demand to ride share.
2. “Human Resources” Business Model is Not Profitable
Lyft and Uber have scaled their companies but it comes with the variable cost of human labor. Ideally, you want fixed costs for R&D on platforms, software, hardware and other products to create the margins that technology is known for. Lyft and Uber are mobile applications, but the business model is more of a large-cap human resources department with many variables around wages, and potentially regulations due to independent contractor classifications. (There was a recent $20 million settlement due to the misclassification of drivers in California).



