
This article was originally published on Forbes on Jun 24, 2022,01:43am EDTForbes on Jun 24, 2022,01:43am EDT
Netflix’s stock is down a staggering 71% year-to-date. The stock’s fall from grace includes dropping its FAANG-status as the company’s market cap has decreased from $300 billion to $75 billion. This was partly due to the company reporting it lost subscribers for the first time since 2011, with a loss of 200,000 subscribers in the most recent quarter. The company also forecast a decline of 2 million paid subscribers for the second quarter.
The earnings report caused the stock to immediately lose 35% of its value. Bill Ackman sold his Netflix shares for a loss of $450 million in three months, with some goading him for his decision while others congratulated Pershing Capital for being bold and walking away from a losing position.
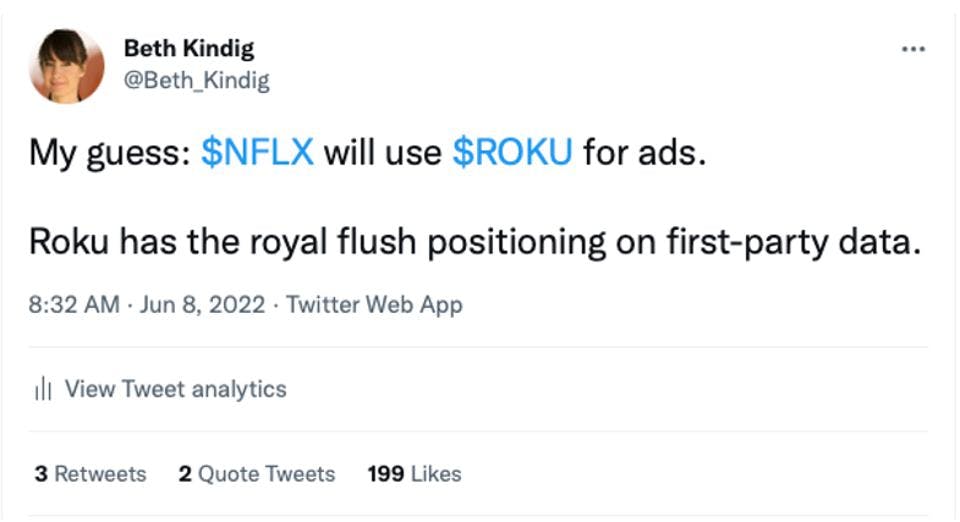
Meanwhile, our focus was elsewhere. In our Netflix coverage following its earnings report, we had stated “we can’t help but salivate” over which ad platform Netflix might choose to power ads to hundreds of millions of viewers. Primarily, this is because we have consistently discussed why the trend of CTV ads has plenty of runway even during an epic market selloff.
The key point is this: the global juggernaut in media is essentially stating that CTV ads are the future for streaming.
Below, we discuss why a new perspective is needed as the 200,000-miss last quarter and the 2 million miss this quarter pales in comparison to the 100 million viewers who are sharing passwords that Netflix intends to monetize. In other words, I would argue the day that Netflix’s stock price dropped 35% was consequently one of the most important days in the company’s history in terms of its chances for a boost in revenue and a renewed uptrend. Patience, though, will be required, as Netflix has work to do (minimum one to two years for full global roll-out). Yet the path to adding more subscribers is finally clear for Netflix and will pay off long-term especially during times of inflation or muted consumer confidence as it drives down household costs across fragmented subscriptions.
Netflix’s Q1 Earnings
The company reported revenue of $7.9 billion, up 10%. Excluding FX headwinds, the revenue growth in the quarter was 14%. The company guided for 10% growth in the upcoming quarter for $8.05 billion in revenue. Net cash from operations was up from $777 million to $923 million.
Netflix has maintained a healthy operating margin above 20% for most quarters and EPS beat estimates at $3.53 compared to $3.75 EPS a year ago. However, the issue with Netflix has been the lumpy free cash flow since the company began producing original content with the majority of the company’s history being deep in the red on cash flow. The recent quarter was positive $802 million, yet the company still holds gross debt of $14.6 billion on the balance sheet and net debt of $8.6 billion.
Netflix reported a subscriber miss of 200,000, yet excluding Russia, the company had net adds of 500,000 as Russia contributed to a miss of 700,000. Regardless, it’s the upcoming quarter that has the market concerned as Netflix is guiding for a loss of 2 million subscribers.
Notably, Netflix has moved towards staggered releases of hits such as Stranger Things, which could reduce churn and help renew subscriber strength.
Netflix Entering the Ad-Supported Market
We had written an editorial a year ago on Forbes called the Crucial Difference between Netflix and Roku Stock. At the time, we pointed out that: “we believe first-party data for connected TV ads is a significant trend moving into 2021 and an important distinction from subscription-video on demand (SVOD) […] Ad-Video on Demand (AVOD) has an approximate ten-year runway as the trend began taking shape when Roku launched its ad platform in late 2018/early 2019. There were AVOD players in the space before this, but the budgets were negligible.”
During the most recent earnings call, Netflix’s management team discussed the company’s plan to introduce ad-supported content:
“And one way to increase the price spread is advertising on low-end plans and to have lower prices with advertising. And those who have followed Netflix know that I've been against the complexity of advertising and a big fan of the simplicity of subscription.And those who have followed Netflix know that I've been against the complexity of advertising and a big fan of the simplicity of subscription.
But as much I'm a fan of that, I'm a bigger fan of consumer choice. And allowing consumers who would like to have a lower price and are advertising-tolerant get what they want makes a lot of sense. So that's something we're looking at now. We're trying to figure out over the next year or two. But think of us as quite open to offering even lower prices with advertising as a consumer choice.”And allowing consumers who would like to have a lower price and are advertising-tolerant get what they want makes a lot of sense. So that's something we're looking at now. We're trying to figure out over the next year or two. But think of us as quite open to offering even lower prices with advertising as a consumer choice.”