
Will Roku miss earnings? I believe Roku will miss earnings at times, but for the big picture, Roku is at the center of an important trend in advertising and this will make for decent returns now and sizable returns in the future. I also don’t play the earnings game often with stocks as my analysis does not change monthly or quarterly. My conviction on Roku is high and can withstand trade war news or a fledgling quarter, which is normal for smaller companies on the edge of incipient trends.
What Investors Got Wrong With Roku
The first thing Wall Street got wrong with Roku is that investors thought Roku was a hardware player. Although it is clear now that the ad platform is what will drive the profits, this wasn’t evident in the financials for a few earnings reports. My three pieces of analysis in 2018 were the opposite; I made my readers aware the ad platform was where the growth potential was.
The second thing Wall Street gets wrong is assuming Google or Amazon can dominate over-the-top television because they are Big Tech and smaller companies don’t have a chance. Google struggles here and recently raised the prices on YouTube television to $49, which for the most part, negates the purpose of cord-cutting when you add a few subscriptions like Netflix or HBO Go, and end up at the monthly cost of cable. Amazon is pushing into ads for OTT, however, there will be privacy regulations to face as the data powering those ads is being brokered without consent from e-commerce and Prime purchases. You can ask Facebook how that is going for them.
Roku has all of the pieces to the stack. The hardware is a razor-razor blade model that locks in their ad-supported platform. They’re OTT-only, and this prevents privacy issues for the data they collect from the device (this is why Apple is always in the clear with privacy issues – data stay s on the device).
Also Read : Prediction: Here’s Why Roku Will Be The Next Tech Darling
Analyst Expectations Low for Q1 2019
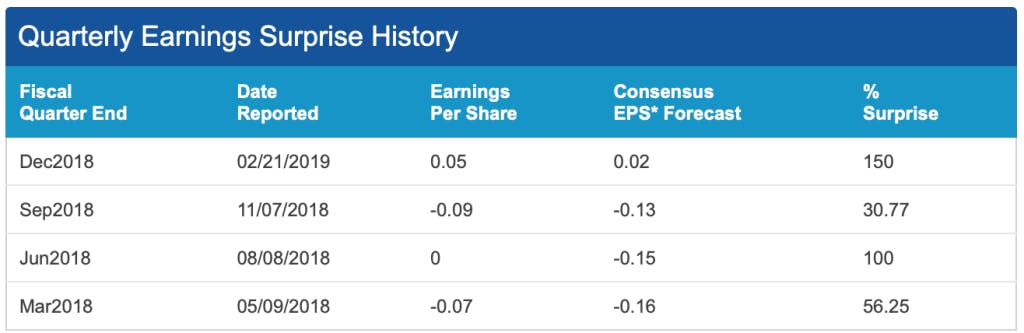
Interestingly, the consensus EPS forecast for Roku is negative $0.24 compared to negative $0.07 same quarter last year with analyst expectations of declining growth. Meanwhile, Roku had posted EPS of $0.05 last quarter. Here’s a screenshot of Roku’s earnings per share vs. consensus:
TradeDesk is also a Connected TV advertising player and reports on May 9th with analysts expecting declining growth from the previous quarter with estimates at $0.07 per share.
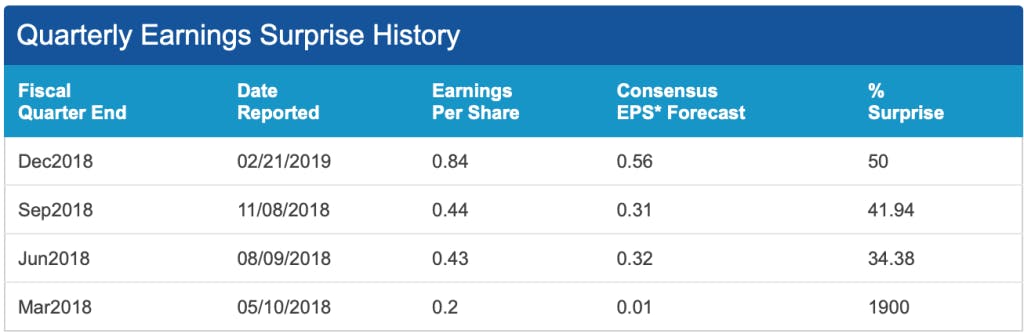
With that said, advertising is driving record profits for many companies who have already reported this quarter, such as Facebook and Twitter. This is why I’m surprised (and don’t necessarily agree with) the low analyst expectations for both Roku and TradeDesk as these expectations of -$0.24 for Roku and $0.07 for TradeDesk are some of the lowest in these stocks’ earnings histories (1+ year or more).
Also Read : Roku Q3 Earnings: Choppy But Unshakeable Long-Term
My Opinion “Long on Roku Even if They Miss Q1 Earnings”
That was my headline last May in 2018 even though Roku did not miss Q1 2018 earnings. My stance on this stock remains the same. Roku is a core holding of mine because of the mega trend towards Connected TV advertising. To put it simply, and as I wrote before Q1 2018 earnings were reported, Roku beating or missing earnings is not my focus for a long strategy based on an important trend. I fully expect tech companies to miss earnings from time to time (this creates better buying opportunities). This won’t change my conviction that Connected TV advertising is on an important upward trajectory.
Here’s some more information on the Connected TV market:
“Two of the big trends in digital media aren’t compatible: The drive to enforce viewability standards and the shift to mobile, particularly apps.” – Digiday


