According to Fubo’s recent earnings call, a free-to-play app is scheduled to launch in Q3 and a sports betting app is scheduled to launch in Q4. As we stated over the past two quarters, owning a live sports audience will convert for a lower customer acquisition cost and better lifetime value on both free-to-play fantasy and sports betting compared to the competing sports betting companies who must find media partners. Fubo management refers to this as a flywheel, and we agree there is substantial potential for a flywheel effect specifically due to the enthusiasm of sports fans.
Below, we review the company’s record-breaking audience growth, the much-debated gross margins, the likelihood that Fubo will have to raise money (and when this might occur), plus what we hope to see in Q3 from the company.
Perfect 10.000 on Audience Growth
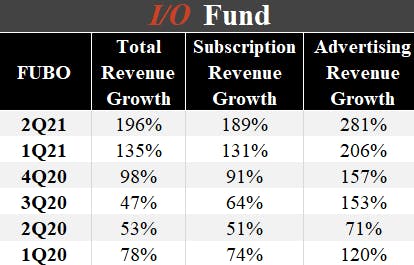
We had made the point that short sellers were exploiting the one-time event of live sports being canceled last year. The results of a live sports comeback are seen clearly in Fubo’s results with 196% growth year-over-year in revenue to $130.9 million, beating analyst estimates by $9.46 million. Subscription revenue grew by 189% YoY to $114.4 million and advertising revenue grew by 281% YoY to $16.5 million.
The most important number was the sequential growth, as Fubo certainly had tailwinds from low Covid comps. In this case, sequential revenue grew QoQ by 9%. This is key because Q2 is a seasonally low quarter for sports. My first guess was that this was due to the NBA playoffs. However, according to management’s earnings call, it was due to “engagement reach[ing] record highs as we added exclusive sports streaming rights with CONMEBOL and began beta testing predictive, free-to-play gaming integrated into our streaming platform ahead of our expected launch this fall.”
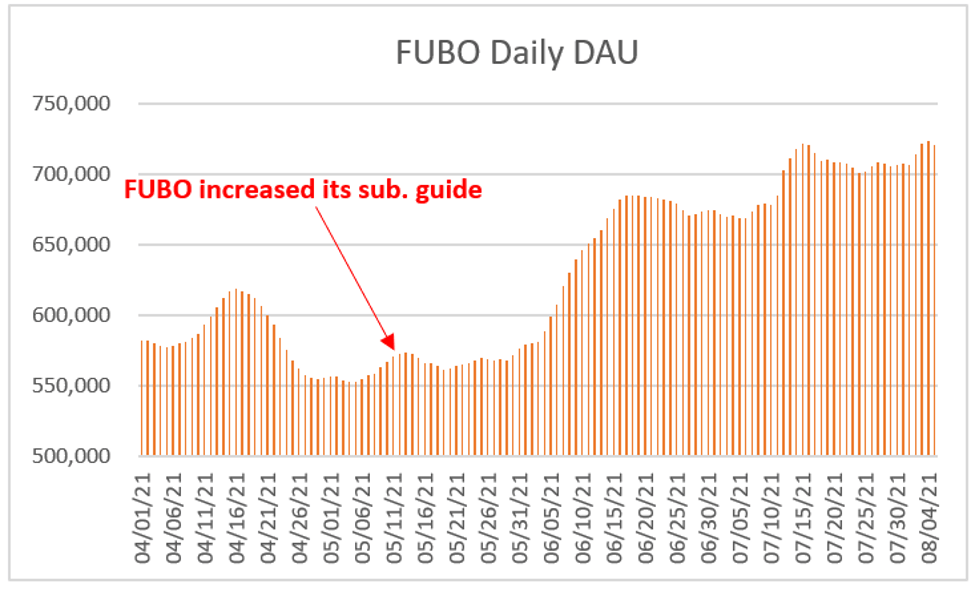
Going into Q3, we had published Apptopia data showing that the company was already illustrating strong downloads and DAU growth, likely from the Olympics. The return of sports events is a major boost for the company’s year-over-year top line growth, yet the sequential strength is where Fubo provides a glimpse of a more sustainable trajectory. The management now expects the fiscal year 2021 revenue from $560 to $570 million, which represents an increase of 116% at the mid-point. Previously, it had estimated revenue to be $520 to $530 million.
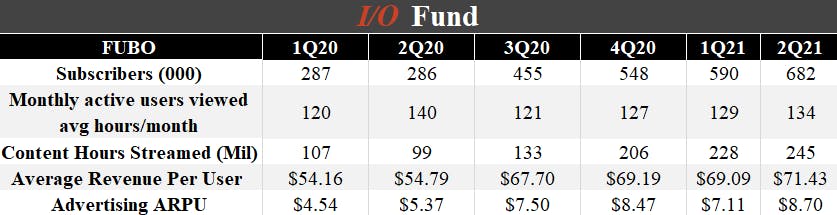
The monthly average revenue per user (ARPU) increased by 30% to $71.43; this was one of the key drivers for the increase in margins. The adjusted contribution margin came in at 8.3%, up from -4.4% in the same period last year. This is a step in the right direction, although there’s more work to be done on profitability before we see institutional interest pick up.
Fubo is in a high-growth phase. It’s not uncommon for a rapidly growing company to show losses; however, we want to see a deceleration of these losses as the company scales. Fubo’s gross losses shrunk from $4 million in Q1 to $2 million in the recent quarter. Considering that their gross losses were $18 million in the year-ago quarter.
It’s also important to point out that Fubo’s cash balance of $400 million supports about 9 quarters of operations ($406 million in cash / $47 million in Q2 adjusted EBITDA). Therefore, it’s reasonable to expect the company may raise money in the near term, which can dilute shareholders. As an investor, I am not too concerned about this (Tesla did it many times), although my preference would be that Fubo raises cash in Q1 or Q2 after the launch of its betting app so the market can understand and assess the company’s full potential.
Source: Fubo Investor Relations
As seen above, the advertising revenue growth was the best ad revenue quarter in the company’s history. Advertising ARPU grew by 62% YoY to $8.70, up 22% on a QoQ basis. The company has a goal to double the advertising revenue this year.
My main contention is that as long the company can grow its audience, the market will reward it in the long-term. Our previous analysis was focused on the microtrend of live sports OTT and we think these users are stickier than Wall Street realizes.
Source: Fubo Investor Relations
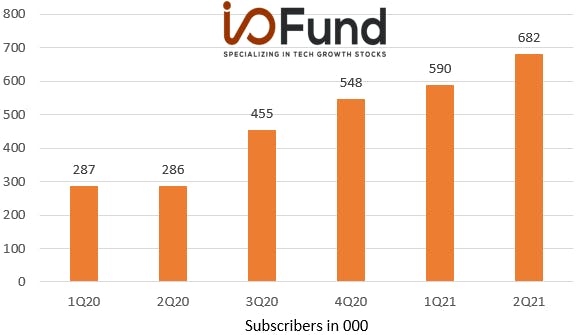
The company has successfully been able to increase its paid subscribers. The customers continued to prefer fuboTV over legacy pay TV services due to the unique customer experience, innovative product experience, and bundled wide premium content. The company added 91,291 net subscribers in the recent quarter bringing the total to 681,721. This beat the analysts’ estimate of 602,000 and the management guidance of 600,000 to 605,000.
The company also increased the full-year subscriber guidance to a range of 910,000 to 920,000, from previous guidance of 830,000 to 850,000.
It’s crucial to not only grow the audience but also retain them. The company has been able to improve the churn rate by 203 basis points year-over-year. The company’s investment in subscriber intelligence and insights helps to lower the churn rate. Management points towards its first-party data for reaching household income above $85,000 and mainly males. This can help the company reach its target of $35 CPMs with current CPMs in the low $20s.
Fubo users streamed over 245 million hours which is an increase of 148%. The company’s monthly active users (MAUs) watched 134 hours per month on average, demonstrating strong customer engagement – we hope this engagement translates well for the free-to-play and sports betting app.