Svod

Roku Q3 Earnings: Choppy But Unshakeable Long-Term

Written by

Beth Kindig

Founder, CEO and Lead Technology Analyst

Published: November 8, 2019

Last Updated: November 8, 2019

Roku is a company that has proven nearly every bearish prediction wrong with consistent revenue growth despite being surrounded by steep competition and tech heavyweights in over-the-top media.

Roku investors that have been long since its IPO have lived through three fifty-percent drawdowns. Therefore, the reaction to earnings this quarter was unlikely to phase anyone who has followed this stock for any length of time.

I encouraged my readers to not be phased by market reactions when Roku was priced at $30, when it was priced at $60, and when it was priced again at $30. During that sell-off, I said the company would become a tech darling and reach $100 in stock price in two years, which was bold to predict 200% returns. Of course, the company went on to reach 350% returns in a short time span of about one year.

Also Read : Update on $ROKU – Will Roku Miss Earnings?

A version of this article appeared in MarketWatch on November 6th. MarketWatch on November 6th.

Roku Earnings Report Review

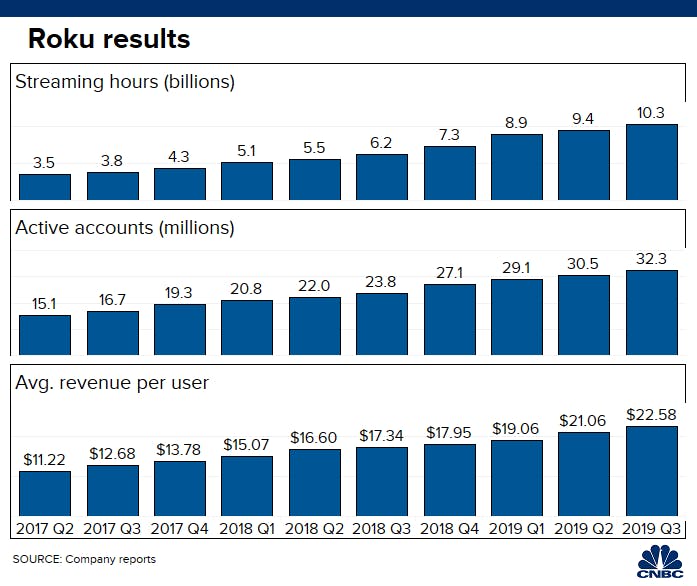
The market received Roku earnings report on Wednesday after the market closed. Streaming hours passed 10 billion hours in the third quarter, while active accounts increased to more than 32.3 million. The most impressive number in the Roku quarterly earnings was the average revenue per user, which increased to $22.58. This number has more than doubled since the second quarter of 2017.

The Roku earnings report showed that quarterly revenue increased to more than $261 million. Platform revenue grew by 79% while ad revenue more than doubled. This was a 50% YoY growth and was above the consensus estimates of $256.9 million. The company lost 22 cents a share, which was 6 cents above the consensus estimates of 28 cents a share.

Overall, the company beat the consensus estimates, raised guidance, reported strong user growth, and increased ARPU.

However, Roku has double-digit negative EPS and will for some time. Roku financial statements show that EPS is declining QoQ. Its consensus EPS forecast of -$0.28 compared to -$0.09 in the year ago quarter. Annual EPS won’t improve either, per analyst consensus, with -$0.50 ending in fiscal year December 2019 and -$0.43 ending in fiscal December 2020.

Also Read : Here’s Why Roku Will Be The Next Tech Darling
Source: CNBC

We’ve already seen a few companies get crushed by the market if they have a small miss, which is the paradox for growing tech companies who are often penalized by the market by foregoing earnings to capture peak growth, which in turn, becomes rewarded by the market once it materializes into earnings. In other words, if Roku misses anytime in the next couple of years, it’ll be with EPS rather than revenue. The market, which is confused by the many OTT streaming services and hardware players, will penalize Roku. This most certainly will not be the last time the stock sees double-digit pullbacks.

I also foresee the market abandoning Roku and many other solid tech stocks that aren’t profitable yet during the inevitable value rotations. Keep in mind, investors also did this with Netflix, Google, Apple, Microsoft and Amazon during 2009.

Misunderstood Competition is an Edge

As is always the case, the market has a record of underestimating small companies that are battling with other big companies like Apple, Disney, Google, and Comcast. This is why Roku still remains one of the most volatile stocks in the market. This also proves the affinity investors have towards brands rather than technology. Yet, it is the latter that drives growth in new markets.

The nuances in strategy and technology are terribly important to understand in the crowded OTT space as it helps to have conviction when a stock drops 50% or more, yet then goes on to be the best performing stock of the 712 stocks with a market capitalization over $10 billion in 2019.

Let’s break down what I mean by Roku having very little direct competition.

SVOD vs. Connected TV Ads

Roku does not compete with Disney+, Netflix, or HBO Go because these are subscription services. Subscription video on demand (SVOD) is in a category of its own as the opportunity Roku is capitalizing on is Connected TV ads (CTV Ads). Advertisers are paying a premium for CTV ads, which is Roku’s market. The distinction between markets is important, and one that Wall Street missed when discounting Roku as a long-term opportunity by labeling it a hardware company for its first couple of years on the market.

Beth Kindig, founder and lead tech analyst of I/O Fund

Get Our Free Weekly Stock Newsletter

Get weekly stock insights, market analysis, and technology updates straight to your inbox.

  • Weekly stock insights
  • Market analysis
  • Technology updates

Roku directly competes with Amazon and Hulu, as they compete for Connected TV ad dollars. However, as the market is well aware, data is king as it allows for better targeting. Hulu has to barter data as it’s a single application without a platform or hardware (i.e., it shares and connects third-party data, including with Facebook). Third-party data is always weaker targeting than first-party data and could be subject to privacy issues.

Razor-Razor Blade Model

Discounting the hardware and taking a loss is an excellent strategy to maintain a moat on data for advertising. Both Amazon and Roku own the hardware, and at current prices, the hardware likely causes negative or very thin margins. This is similar to the razor-razor blade model, where you discount the razor to sell the razor blades for life.

This positions Amazon and Roku for first-party data across OTT applications. Anything data related is subject to privacy issues and anti-trust issues. This is at the core of the controversy with Facebook and Google.

Roku is again set apart here, as the company only does OTT. The company does not share the data beyond the OTT player it owns. Amazon, however, is collecting data in a way that could come under anti-trust scrutiny as they take e-commerce data and broker this on the OTT player, which is anti-competitive with other ad exchanges.

Amazon is well aware of this, and is being proactive rather than reactive by opening up its demand-side platform to other DSPs, such as The Trade Desk, which was announced in July of this year. On a side note, Facebook learn from Amazon’s playbook as reputational damage is hard to shake.

Roku, however, does not need to worry about this as data never leaves the OTT hardware that they own, where they have a first-party relationship.

Valuation:

Connected TV ads are ballooning because they combine audience data with the viewability and completion rates of linear television. Roku’s valuation at 14 price-to-sales seems high at first, yet the one-year forward price-to-sales is trading at 9.3 due to the forward growth opportunity in Connected TV ads. Roku earnings estimates for 2020 and 2021 are $-0.29 and $0.6178 respectively. Therefore, the market may still be lukewarm with knee jerk reactions throughout 2020.

For example, last November, video-first SSP Beachfront reported that ad requests for CTV had increased 1,640% from November of 2017. While this is only one company’s growth in a single segment, the opportunity is so ripe, it’s hard to quantify. More astonishing is that Connected TV ads surpassed mobile last year for capturing the largest number of impressions and video completion rates.

Roku’s revenue growth will be exciting; however, the company is not likely to be profitable until 2021. In the third quarter Roku income statement report showed that revenue grew by almost 60%. This was almost double that of Netflix and triple that of Google.

Traditional metrics show that Roku is not a cheap company to own. Its forward EV to EBITDA ratio of 393, which reflects the lack of profitability. It’s not surprising the stock is trading in the range of $127-$131 following earnings, which was former support.

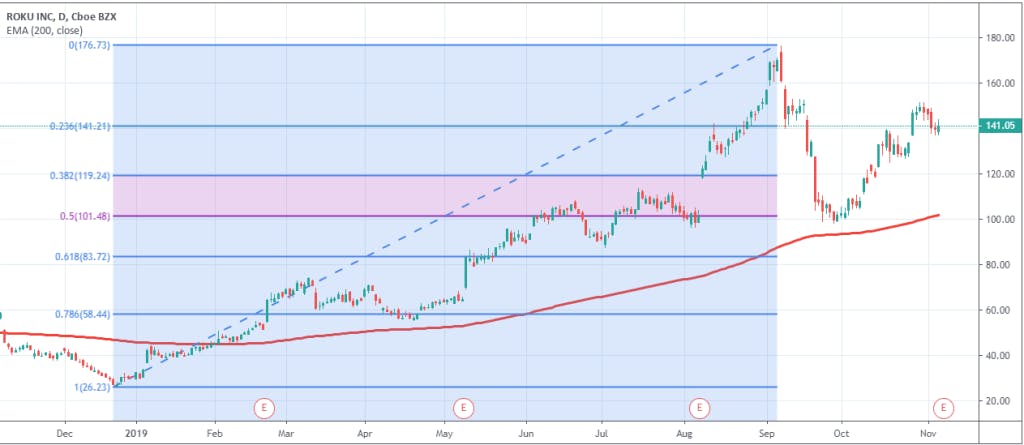
Depending on macro trends, we could see Roku trade around $100 again as this is an important psychological level, as shown below. It is also along the 50% Fibonacci Retracement level and along the 200-day exponential moving average. Long-term, I see Roku as one of the most promising tech stocks on the market and have provided projections to my premium subscribers. 

Also Read : Roku’s Stock Price

Knox Ridley, technical analyst, will be covering Roku in-depth with technicals next week. He has guided many successful entries on this stock for our premium members, including entries lower than $100.our premium members, including entries lower than $100.

A version of this analysis appeared in MarketWatch prior to earnings on November 6th, 2019.A version of this analysis appeared in MarketWatch prior to earnings on November MarketWatch prior to earnings on November 6th, 2019. It has been updated and lengthened post-earnings.

About the author

Beth Kindig

Beth Kindig

Profile

Beth Kindig is the Founder, CEO and Lead Technology Analyst at I/O Fund, with more than 15 years of experience covering private and public technology companies. Known for her early Nvidia research beginning in 2018 and bold, high-conviction calls on emerging technology trends, Beth also manages I/O Fund's audited technology portfolio, which has returned 326% since May 2020, or 29.2% annualized. She is a regular guest on Fox Business and Bloomberg and has appeared on CNBC.

Curation

Expand your knowledge

View all posts
Beyond Hyperscalers: Here’s the Next $1 Trillion AI Infrastructure Opportunity
AI STOCKS

Beyond Hyperscalers: Here’s the Next $1 Trillion AI Infrastructure Opportunity

Since 2022, Big Tech capex has been the clearest barometer of AI demand. But the market’s reaction to Google’s latest earnings shows investors are questioning how long that spending can last. While the market frets over hyperscalers’ cash flows, a second wave of AI infrastructure spending has quietly emerged, driven by enterprises and neocloud customers.

AI STOCKSOCT 30, 2026
Google’s $250 Billion AI Chip Opportunity Takes Aim at Nvidia
AI PLATFORMS

Google’s $250 Billion AI Chip Opportunity Takes Aim at Nvidia

In April, there was a major shift in the AI accelerator market, and for once, it didn’t come from Nvidia. Six months later, merchant TPUs are moving from announcement to commercial execution, with Google recognizing its first revenue from TPU systems in Q2 (from a small base). Last quarter, Cloud revenue growth accelerated to 82% for $24.8 billion, compared to $22.5 billion expected. In addition, new details around the TPU 8t show that Google’s threat to Nvidia is not limited to inference. At the time, we pointed out that Google may be one of Nvidia’s strongest AI challengers, as Big Tech is closest to the problems that accelerators must solve. The problem that Google is prioritizing is lower cost per token, with token economics becoming a predominant concern as AI spending is pushing Big Tech’s free cash flows into the red. Below, we discuss two reasons why Google’s AI story is about to change, not from advancements in AI software, but by going after one of the most profitable hardware businesses the tech industry has ever seen.

AI PLATFORMSOCT 23, 2026
AI Debt Nears $500 Billion in 2026: What It Means for Nvidia, Oracle, CoreWeave and AI Stocks
AI STOCKS

AI Debt Nears $500 Billion in 2026: What It Means for Nvidia, Oracle, CoreWeave and AI Stocks

AI-related debt reached $466 billion through September 2026, more than four times last year’s pace. We break down who is borrowing, the three ways new AI chip deals are being structured, and where interest costs land across Nvidia, Oracle, CoreWeave, Broadcom and Big Tech.

AI STOCKSOCT 23, 2026