

As Apple’s stock price powers to new highs, returning over 60% YTD and touting the highest market cap in history, now might be a good time for investors to reflect as Apple trades at resistance. With upwards of $260 billion in revenue, a profit margin of 22%, Apple is a cash-generating machine. It produces around $50-$60 billion in free cash flow annually, with reserves of over $100 billion. It is extremely kind to shareholders, with one of the largest buyback programs on the Street. In fact, Apple has spent around $120 billion in stock buybacks since the beginning of 2018, and kicks out a dividend. Apple is, without question, one of the greatest businesses the world has ever seen.
However, there are times where great businesses do not always make great stocks at times. If we look at the current valuations, Apple’s stock price is trading with a P/S of 4.5, a P/E ratio of around 25 and a price to free cash flow of 20, as of the writing of this report. While these valuations are relatively mild compared to some of the valuations being shopped around in the tech industry, for a company with a market cap of $1.3 Trillion, these valuations suggest future growth in order to justify current prices. It is here, with their future growth prospects that I see caution.
Apple’s Stock Price is Up While Revenue is Down
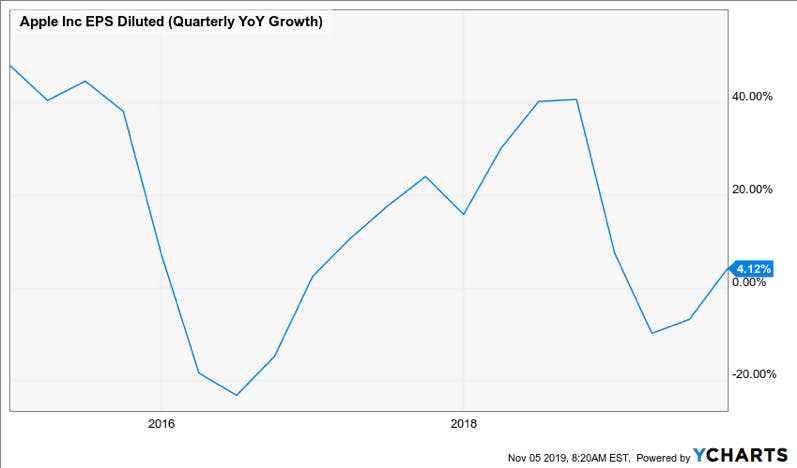
In 2019, the company had revenue of $260 billion, down from $265 billion in the previous year. Analysts originally expected the company’s revenue to grow to $274 billion, or 5.3% this fiscal year, and around $294 billion or 7% in the following fiscal year. This will be slightly below the 7.2% growth that is expected among information technology stocks.
In the latest quarter, its growth rate was just 1.8%, significantly lower than what other FAANG companies reported. Facebook revenue grew by 28% while Amazon rose by 23%. Netflix and Google had revenue growth of 31% and 20%, respectively. Even Cisco grew by almost 5%. And for further comparison, the US economy expanded by 1.9%.
Apple’s poor growth would have tanked any technology stock, yet Apple’s stock price is up 60%. Though I believe Apple has the cash as well as the capability to pull numerous pivots in its future, the loss in revenue will likely accelerate before these pivots can manifest, which will compress margins, and thus affect current valuations.
iPhone Saturation – Will it Affect Stock Price?
If we dig deeper into their latest revenue report, we discover that smartphone sales declined YoY by 15%. Saturation is an inevitable phenomenon for revolutionary inventions. For example, Utilities and wireless phone coverage were once considered hyper growth sectors at one point in time, but the inevitable saturation took hold, leading these companies to now be considered defensive value plays. Saturation appears to be taking hold in the smartphone market, which is why we are seeing a deceleration in smartphone sales YoY; with an expected 2% fewer sales per year going forward.
Furthermore, with saturation, we see manufacturers start to slash prices to capture fewer units sold. This quarter, Apple reported that iPhone sales declined by 9% since the previous year and that they are also reducing the price of their new iPhone 11. Both news items point to the reality of market saturation.
The iPhone is arguably the greatest tech driver in history, as well as Apple’s primary source of revenue. So, Apple will have to cover the losses with their other products to make up the difference. This is where I see the inconsistency between the stock’s valuations and their current offerings.
Services
Apple’s services generate revenue through various subscription fees. These fees come from several well-known Apple services, including iCloud, iTunes, Apple Music and various types of apps.
Although these services grew by 18% this last quarter, the total revenue generated was only 37% the size of iPhone sales. This level of growth is simply not enough to cover decreasing revenues from Apple’s iPhone sales.
Furthermore, there are also concerns in the service sector. The problem is that the services that Apple offers have relatively lower margins than the iPhone. A good example of this is Apple Music. Apple doesn’t disclose Apple Music’s gross margins, but going by Spotify’s own margins, we have every reason to believe that Apple is similar. Spotify’s gross margin is just 26%, which is smaller than Apple’s iPhone net profit margin. It’s important to note that the services segment of Apple is tied to the iPhone and may experience slower growth as the smartphone market continues to saturate.
Apple +
There’s also a lot of hype around Apple TV+’s potential at filling the growth gap. According to the Wall Street Journal, Apple is spending more than $6 billion on new content, and it’s only likely to go up as the streaming war continues.
At current prices for the service, it’s impossible for Apple to make a profit even with a hundred million subscribers. Apple can still be a contender in this crowded space, but it will likely take time, and be more of a cash drain than a generator in the short-term. Meanwhile, smartphone saturation is only going to continue, which means that Apple TV+ will not be able to solve Apple’s current revenue problems.
Apple Pay
Apple Pay is another service that Tim Cook talks about repeatedly. During the latest earnings call, he revealed that the service had surpassed PayPal in terms of volume of transactions. The service is also expanding into various markets. Additionally, Cook also praised Apple Card, a new product developed in collaboration with Goldman Sachs that promises to expand Apple’s revenue.