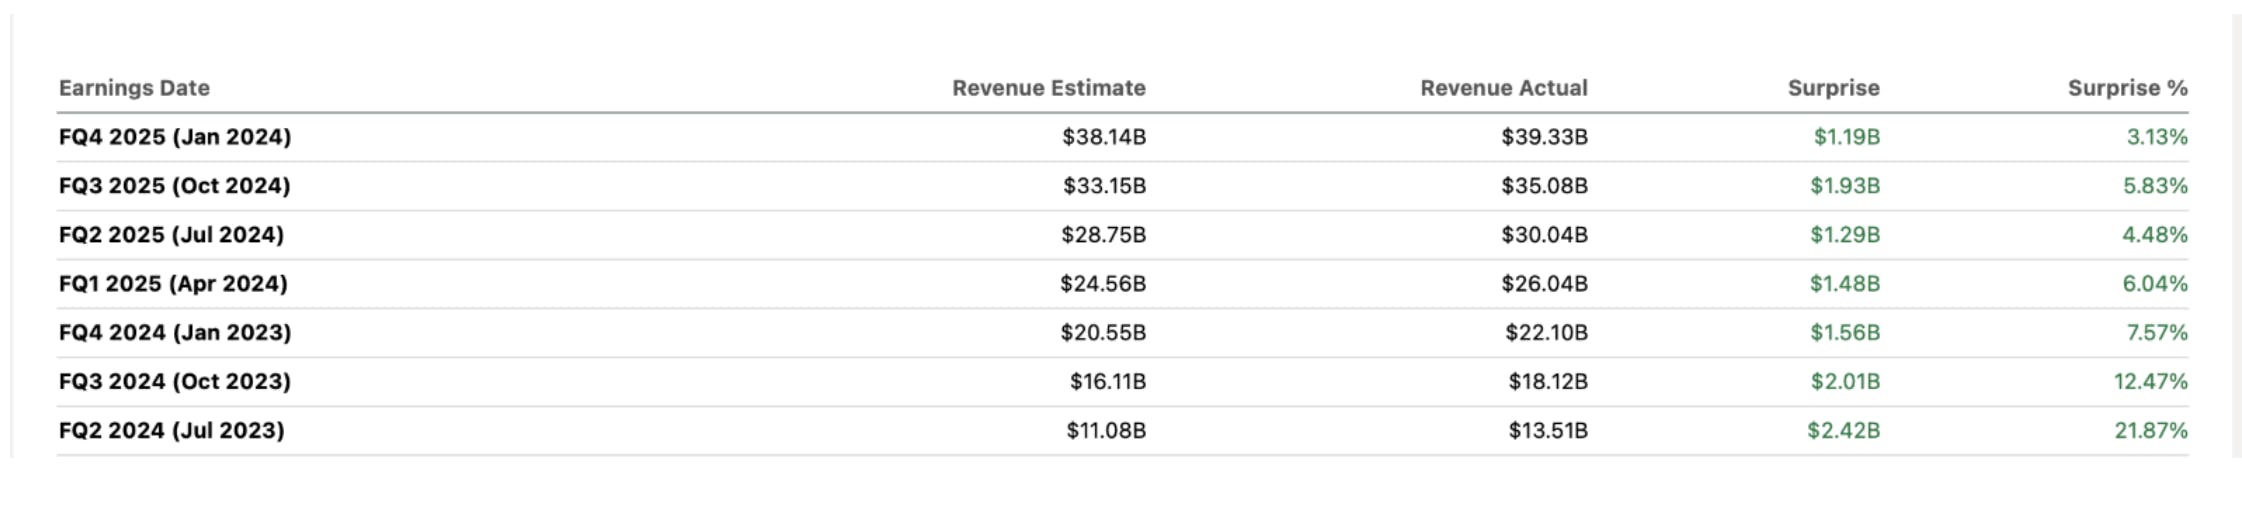

When you’re Babe Ruth, the crowd expects to see a homerun. Hit a single or a double and the fans go home disappointed. Nvidia has continued to report exceptional earnings results, yet Nvidia stock is competing with itself at this point.
Next week, Nvidia will report fiscal Q1 earnings, and the market has become accustomed to the company reporting a string of homeruns and grand slams. While Q1 results will be propped up by China stockpiling the H20s, the outlook for Q2 is the choppiest the company has faced in two years. This is because Nvidia has a narrower path than usual to impress investors as the Hopper generation demand is waning while Blackwell is (finally) shipping but not at the levels originally expected.
Last quarter, I published the analysis: “Nvidia Suppliers Send Mixed Signals for Delays on GB200 Systems – What it Means for Nvidia Stock.” which stated “Given market jitters around DeepSeek, which turned out to be a non-issue, something more material related to the GB200s, such as growth slowing below expectations at the start of the new fiscal year, could send the stock below $100 — which we would see as a buying opportunity […] ultimately, my firm trimmed our Nvidia position (to a 10% allocation) and will happily buy lower should the assumptions in this analysis materialize. Nvidia remains the stock of the decade; however, stock returns – and product launches — are not perfectly linear.” –February 2025
That analysis played out. We were able to buy Nvidia at $87, issuing a real-time trade alert that has returned 53% on that tranche since early April. We also added several key Nvidia suppliers that have moved sharply higher.
With a strong seven-year track record on this name, I felt it was important to share my perspective as Nvidia Week kicks off on Wall Street.
H20 Export Ban Will Result in $5.5B Inventory Loss and Cost $15B in Revenue
China has dominated the headlines over the past quarter and exactly how Nvidia plans to overcome geopolitical tensions will be a primary focus in the upcoming call. Export controls have been in place for years, hence the H800 and the H20 GPU variants, which were designed to be less powerful GPUs to comply with export restrictions. Yet, the license restrictions were changed in April, resulting in a $5.5 billion inventory loss for Nvidia. More recently, Jensen Huang clarified it would be $15 billion in revenue stating the inventory will have to be discarded.
Here is a brief summary of the USA-China GPU licensing restrictions:
- In 2022, the Biden administration placed export controls on the A100s and H100s due to bandwidth, requiring the bandwidth to be lowered to 400GBps This led to the A800s and H800s.
- In October of 2023, performance requirements were accounted for in the export controls, limiting sales of Nvidia’s A800, H800, L40, L40S and RTX 4090 chips. This led to Nvidia creating the H20 GPUs.
- In April of 2025, the Trump administration has effectively banned the H20s by denying the export license. This is on the grounds that H20s can be used in supercomputers and offers 20% faster inference than the H100s.
While the H20 has reduced compute performance compared to the H100s — including fewer Tensor Cores and lower FP8/FP16 throughput — it retains high-speed interconnect capabilities through its support for NVLink and PCIe Gen4, and features 96GB of HBM3 memory with 4.0 TB/s of memory bandwidth. The 96GB of HBM3 exceeds the H100s, which is large enough for LLM models to run in memory and lower costs. The higher HBM3 also translates to the H20 offering fast communication when clustered with other GPUs for a multi-GPU system supercomputer.
Furthermore, although the H20 performs at roughly 50% of the H100s, it has a power advantage at 400 watts compared to the H100s 700 watts. Partially due to the lower power, while maintaining high-speed bandwidth for inference, means the H20s have remained attractive to Chinese firms especially in the wake of DeepSeek’s R-1 release.
Selling chips to China for use in supercomputers has been prohibited since 2022. Meanwhile, many industry experts believe Chinese firms were stockpiling the H20s to build a large supercomputer. The Institute for Progress, a nonpartisan group, wrote a long-form explanation of the loopholes that were being used, stating: “The United States is about to make another strategic mistake: Allowing three Chinese firms to receive over $16 billion in orders for NVIDIA H20 chips, amounting to over 1.3 million chips. This order is over six times the size of Colossus, the largest compute cluster in the world. It would more than double China’s entire existing stock of H20 chips. If these chips are delivered, they will dramatically increase Chinese firms’ ability to develop frontier AI models and deploy them at scale.”
As far as when the stockpiling began, semiconductor Insights analyst, Claus Aasholm, noted back in December that “The downgraded H20 system, which passes the embargo rules for China, is doing incredibly well. With 50% quarter-over-quarter growth, it is currently Nvidia’s most successful product. The H100 business “only” grew 25% QoQ.”
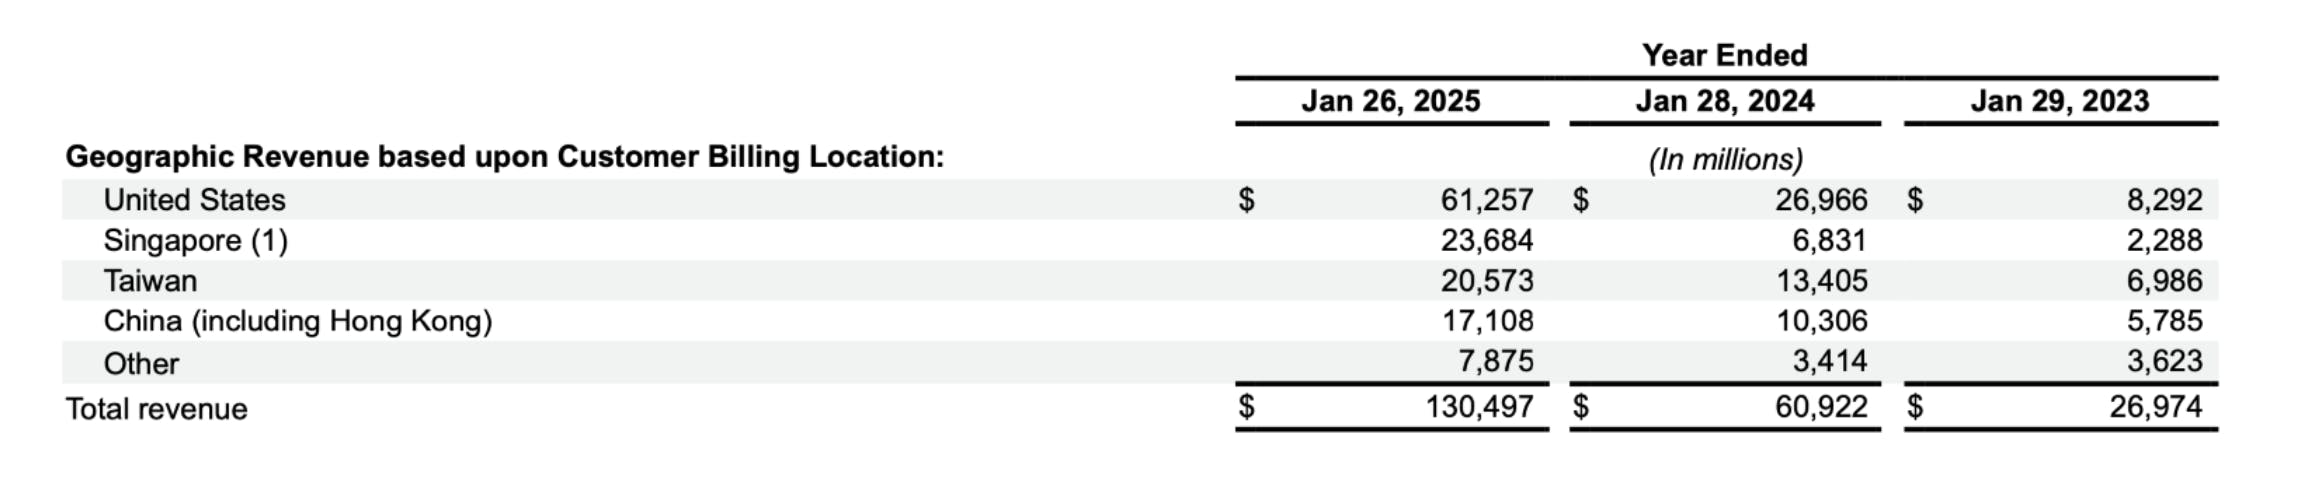
According to Reuters, analysts had forecast a total of $12 billion in H20 sales for Nvidia’s fiscal year ending in January. However, China revenue for the year was significantly higher at $17.1 billion.
However, this pales in comparison to what Q1 and Q2 were about to report in terms of China revenue.
Nvidia Q1 Earnings Preview: Loss of China Revenue Will Sting
In Q1, Chinese tech companies such as Alibaba, ByteDance and Tencent were hurrying to place H20 orders. The Information reported that Chinese Big Tech companies had placed $16 billion worth of H20 chips in the first three months of the year.
This would represent a sudden surge of roughly 3X growth given previous quarters peaked at $5.5 billion:
Nvidia’s China Revenue:
- Q1 2025 ending April 2024: $2.49 billion
- Q2 2025 ending July 2024: $3.67 billion
- Q3 2025 ending October 2024: $5.42 billion
- Q4 FY25 ending Jan 2025: $5.52 billion
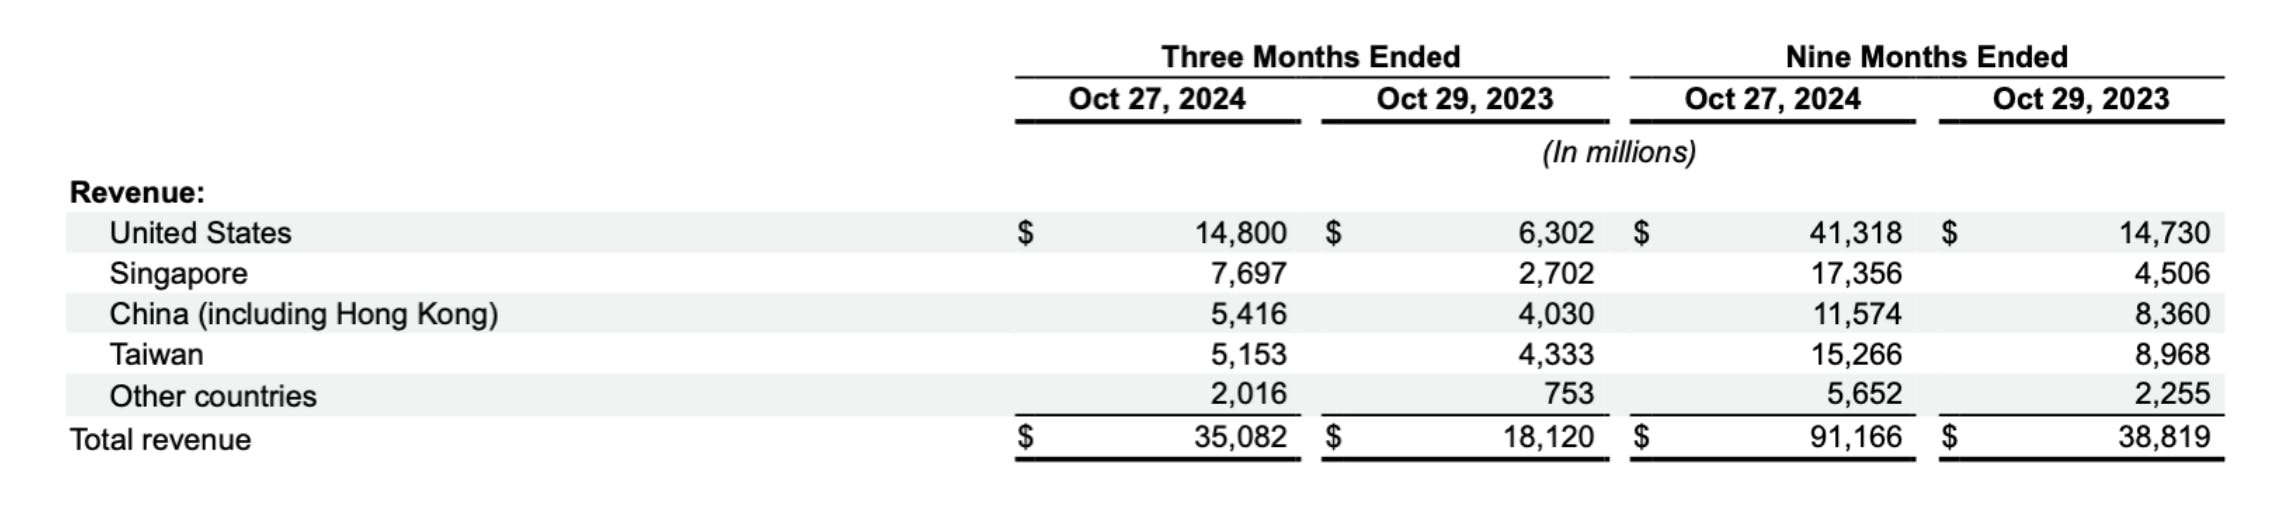
When Nvidia stated they would see a $5.5 billion inventory charge in Q1, it was suggesting a very high monthly run rate given the export restrictions were only in effect for the remaining three weeks of Q1. According to the SEC filing “First quarter results are expected to include up to approximately $5.5 billion of charges associated with H20 products for inventory, purchase commitments, and related reserves.”