
This article was originally published on Forbes on Apr 7, 2022,11:53pm EDTForbes on Apr 7, 2022,11:53pm EDT
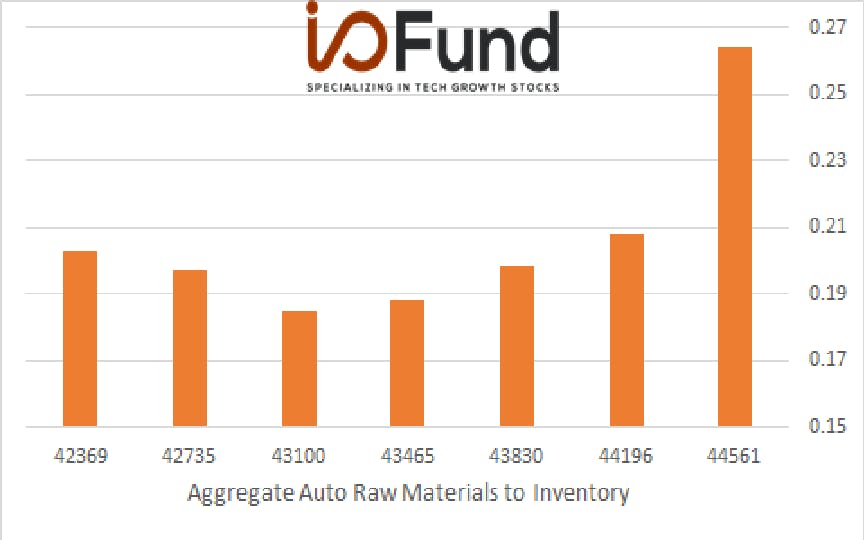
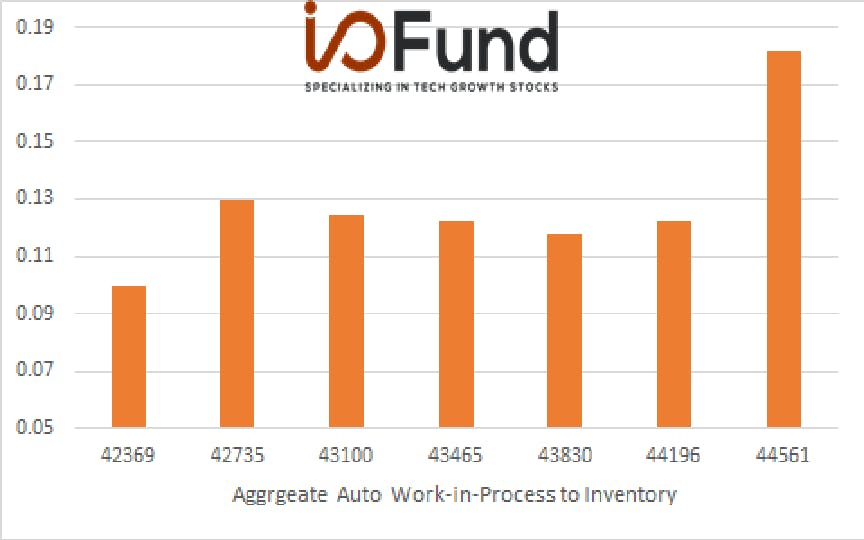
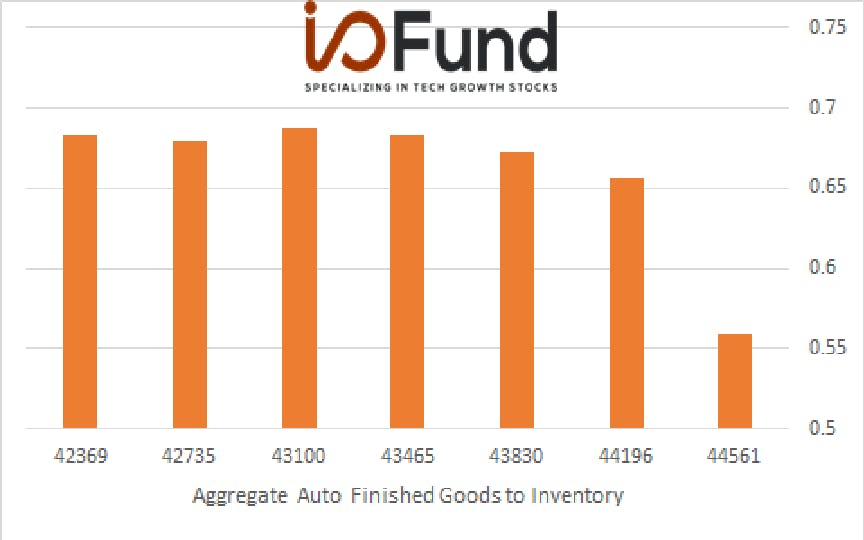
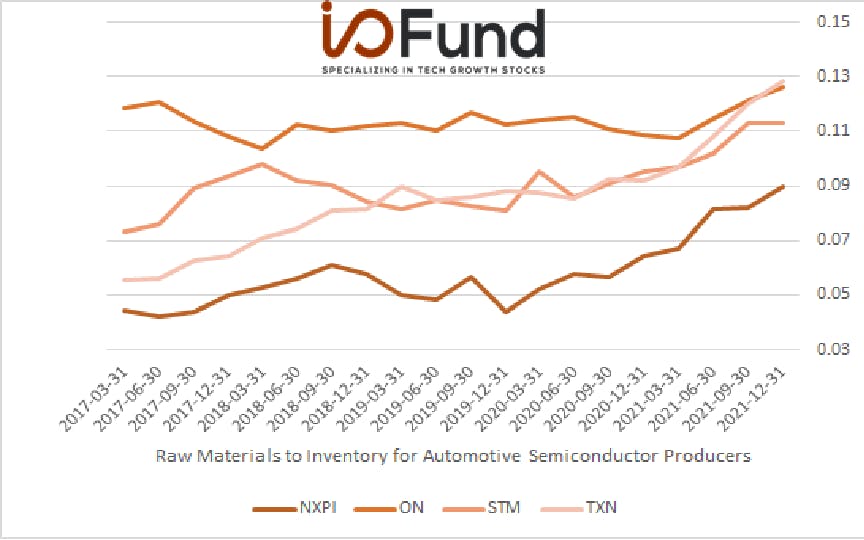
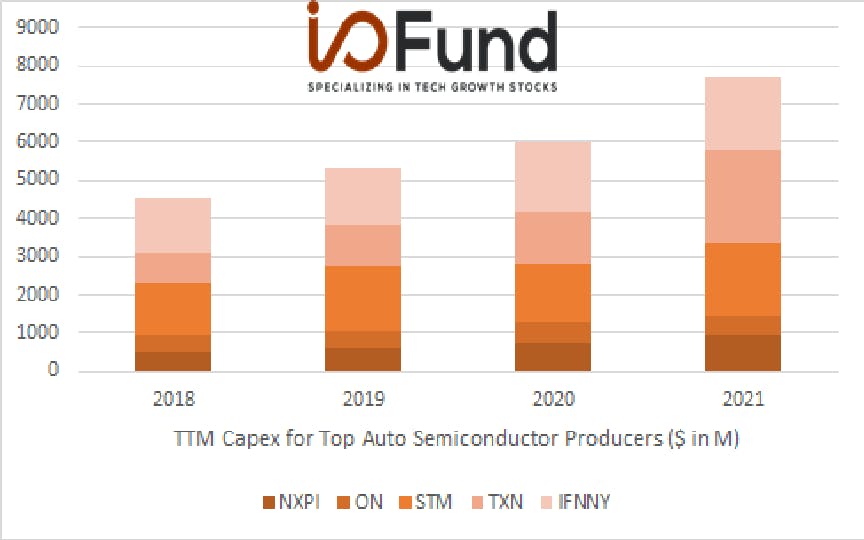
Last week, we discussed signs of improvement at key automotive semiconductor suppliers and why this was affecting ad-tech stocks. Supply chain issues are causing a ripple effect due to automotive being a significant category of ad spend and due to low inventory, advertising budgets are being slashed. As stated in last week’s analysis, our expectation is that supply issues will ease by Q3 causing both automotive and ad-tech to rebound.
Specifically, it’s the extremes of seeing a $300 billion drawdown in inventories in Q2 2020 followed by the largest increase on record of inventory levels in Q4 2021. We believe this sharp rebound helps highlight that production is catching back up with demand.
Supply Chain Impact to Roku Stock and Ad-tech Going Forward
Below, we discuss why Roku stock could be set to rebound when supply chain issues begin to ease due to extreme oversold conditions based on transient headwinds. We also discuss more in depth the supply chain rebound we are forecasting for some time around the second half of 2022.
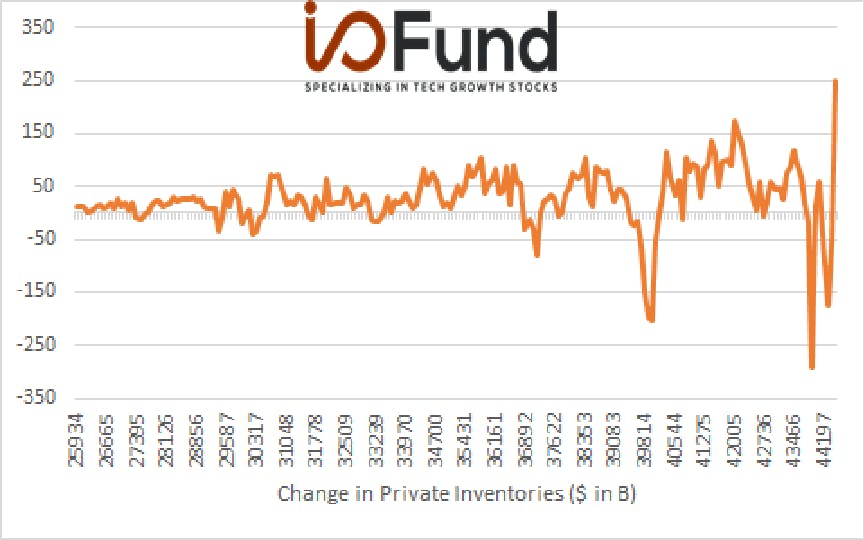
Source: U.S. Bureau of Economic Analysis (I/O Fund)
While supply chain constraints are expected to remain tight in 2022, there are numerous signs that the bottom is in. For instance, aggregate inventories rebounded strongly in Q4 2021 and have made up most of the decline from production halts during Q2 2020. Moreover, inventories relative to aggregate sales are at multi-year highs. The rebound in aggregate inventories suggests that supply chain constraints are normalizing for the broader economy.
Connected-TV (CTV) is particularly exposed to automotive advertising budgets, and a rebound in automotive inventories will be a tailwind for CTV ad-tech companies such as Roku. Automotive ad spend was just 15% of its pre-pandemic levels, largely due to the shortage of automotive inventories.
During the Q4 earnings call (02/17/22), Roku’s management explained how automotive was ‘soft’ during the quarter, yet they expect this to be a temporary trend. Roku CFO Steve Louden made a good point during the Q4 call, stating that automotive manufacturers are much stronger today than they were at the start of the pandemic, meaning that these brands have increased capacity to market their brands going forward.
For instance, if the top two automotive ad spenders (Volkswagen and Toyota) grow their topline by the midpoint of their respective guides and if their sales and marketing margins normalize to pre-pandemic levels, then aggregate ad spending could rise by about ~25% YoY in 2022, up from the ~6% YoY rise in 2021. Rising ad spend from these two leading manufacturers will likely spur marketing investments from peers.
Despite lower growth in Q1, Roku reiterated full year 2022 growth in the mid-30s. Going into the report, analysts were expecting 36% annual growth. The ad platform missed analyst expectations at $703 million compared to $732 million expected.
EBITDA was a miss with company guiding for $55 million compared to the consensus for $79 million in the upcoming Q1 quarter. The company plans to spend $1 billion on operations, which translates to investments in headcount, The Roku Channel (which is producing originals), and the Roku TV program (which means growing operating system market share).
The $1 billion in expenses is not overly concerning although it’s certainly an adjustment in expectations as the Street may have believed that Roku’s earnings were quickly scaling, but this was impacted by a slowdown in expenses during covid, and now those expenses need to ramp in the upcoming year to remain competitive.
Sign up for I/O Fund's free newsletter with gains of up to 403% - Click hereSign up for I/O Fund's free newsletter with gains of up to 403% - Click hereClick here
I/O Fund Financial Analyst Bradley Cipriano stated in a research note to our clients that Netflix's operating expenses ramped nearly $1 billion YoY when it passed $3 billion in revenues in 2011, which Roku is nearing. Viewed differently, the expected revenue growth in FY2022 of $830 million will be accompanied by a $1 billion rise in expenses, meaning that each $1 of expenses will drive just $0.76 of revenue, which is the lowest value in Roku's history. This suggests that growth is much more expensive than in prior years.
However, this is likely due to the slowdown in investments made during 2020 and 2021, and the three-year average for the above metric is 1.08x (including FY2022), meaning that each $1 of expenses resulted in $1.08 in revenues. This is above the prior three-year average of 1.04x (2019-2017), highlighting that over a longer time frame, Roku is in fact demonstrating leverage, albeit it is lumpy. FY2021 and FY2022 also includes the Player gross loss headwind that wasn't the case in prior years, and adjusting for this, the three-year average would be even higher. The takeaway is that the rise in expenses seems in-line with historical trends once we account for COVID.
The lower EPS this year is a headwind to the company's valuation, but it is expected to be profitable in FY2023. The company should be cashflow positive in FY2022 and with $2.1 billion in cash on balance, likely should not need to dilute shareholders despite the losses. There is also some leverage to improve earnings as there were $82m in one-time expenses during the most recent year.
If we widen our view, we will see that 2020 was the first year Roku was EBITDA positive and the company is expected to remain EBITDA positive this year. Most importantly, Roku has leverage with a gross profit of $1.4 billion and they are choosing to spend for top line growth.
Overall, Roku is a more complex product story because the strategy is to conquer from many angles. It’s an ad exchange, it’s a content channel, it’s an operating system and it’s a hardware player. It also owns the best first-party data available on CTV ads and I tend to stick with the data in terms of ad-tech. So, that’s primarily the reason we own Roku and continue to own Roku.
Regarding Roku’s recent price action, we look for dislocations within the markets and we believe transitory supply chain issues have caused the dislocation seen below in Roku’s valuation and its forward estimates. Most of tech has seen a dislocation between January-March, although Roku’s dislocation is particularly steep.
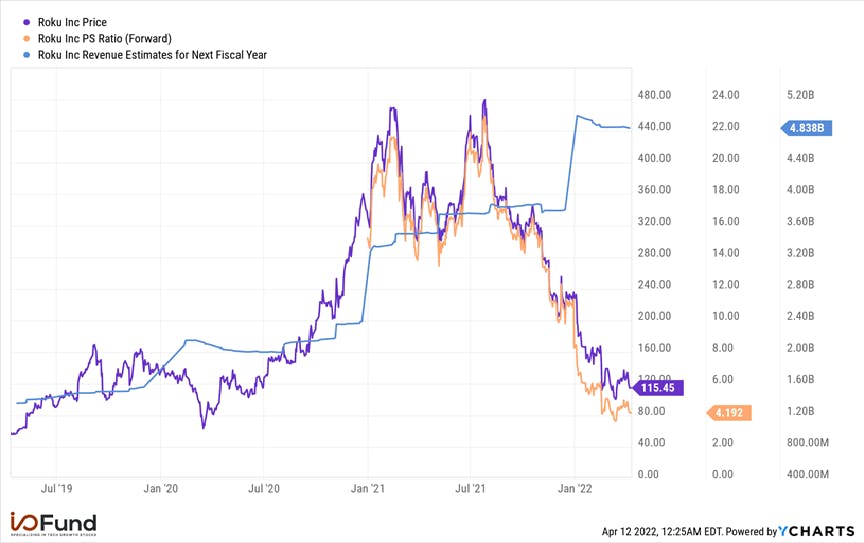
Regarding Roku’s recent price action, we look for dislocations within the markets and we believe transitory supply chain issues have caused the dislocation seen below in Roku’s valuation and its forward estimates. Most of tech has seen a dislocation between January-March, although Roku’s dislocation is particularly steep. (I/O Fund)
What is most striking about the divergence above is that the current selloff has provided a much cheaper stock than during the pandemic when many businesses were shut down entirely and ad budgets halted.
Despite strong growth estimates in the second half of the year, the forward PS on Roku reached 4x, which we consider to be extreme to the downside. We took this opportunity to begin building up Roku and other key ad-tech allocations. We also believe that Q4 2021 will likely represent a ‘bottom’ in automotive supply constraints, and that ad spend from automotive manufacturers will rebound going forward as supply chain constraints begin to ease.