
This article was originally published on Forbes on Dec 3, 2020,11:03pm EST
Google Cloud certainly has the technical chops and engineering talent to compete with Microsoft Azure and Amazon’s AWS when it comes to cloud infrastructure, edge computing – and especially inferencing/training for machine learning models. However, Google may lack focus due to Search and YouTube being the main revenue drivers. This is seen from the company’s inability to ignite revenue growth in the cloud segment during a year when digital transformation has been accelerated by up to six years due to work-from-home orders.
In this analysis, we discuss why Google (Alphabet) may have missed a critical window this year for the infrastructure piece. We also analyze how Microsoft directed all of its efforts to successfully close the wide lead by AWS. Lastly, we look at how all three companies will bring the battle to the edge in an effort to maintain market share in this secular and fiercely competitive category.
Cloud IaaS Overview:
The three leading hyperscalers in the United States have diverse origins. Amazon found itself serendipitously holding server space year-round that it could rent out and was first to market by a wide lead. Amazon continues to release customization tools and cloud services for developers at a fast clip and this past week was no exception.
Microsoft’s roots in enterprise created a direct path to upsell on-premise and become the leader in hybrid. The majority of the Fortune 500 is on Azure as they want seamless security and APIs regardless of the environment.
Google is one of the largest cloud customers in the world due to its search engine and mass-scale consumer apps, and therefore, is often first to create cloud services and architectures internally that later lead to widespread adoption, such as Kubernetes. Machine learning is another piece where Google was one of the first to require ML inference for mass-scale models.
Despite all three having very talented teams of engineers and various areas of strength, we see AWS maintain its lead and Microsoft Azure firmly hold the second-place spot. Keep in mind that Azure launched one year after Google Cloud yet has 3X the market share and is growing at a higher percentage.
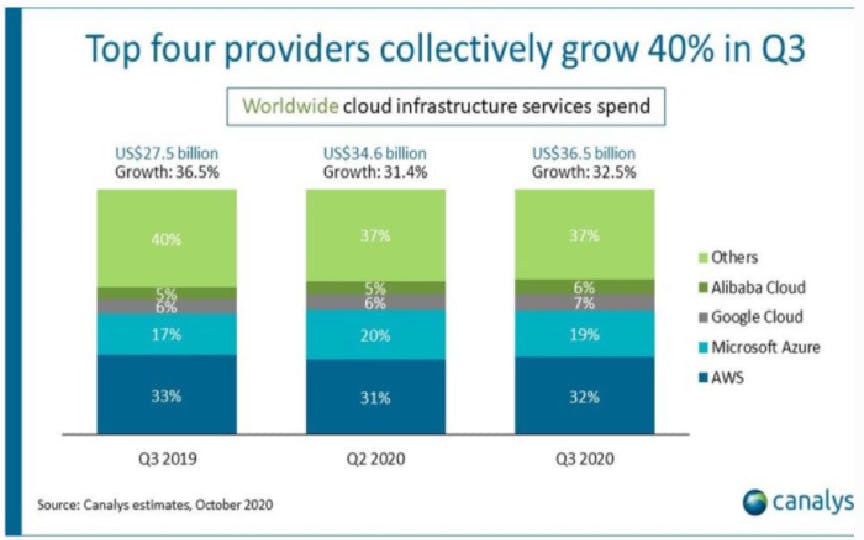
CANALYS
Google Cloud grew two percentage points from 5% to 7% since 2018 while Azure grew four percentage points from 15% to 19% in the same period. In the past year, Google Cloud saw a 1% gain compared to Azure’s 2% gain, according to Canalys.
Azure is under Intelligent Cloud but the company does break down the growth rate which was 48%. Although Google Cloud Is not specifically broken down, the Google Cloud segment grew 45% year-over-year compared to Microsoft Azure up 48% year-over-year.
Amazon Web Services is growing at 29%, which is substantial considering the law of large numbers. In the past two quarters, Google Cloud reported 43% year-over-year growth and 52% in the quarter before that. Microsoft has seen a slightly less deceleration from 51% and this is down from the 80%-range almost two years ago.
The key thing here is that when Microsoft held the percentage of market share that GCP currently holds, Azure was growing in the 80-90% range. This is the range we should be seeing from Google Cloud if the company expects to catch up to Azure.
Sign up for I/O Fund's free newsletter with gains of up to 403% - Click hereSign up for I/O Fund's free newsletter with gains of up to 403% - Click hereClick here
In 2020, the term “digital transformation” has become a buzzword with cloud companies seeing up to six years of acceleration. Nvidia is a bellwether for this with triple-digit growth in the data center segment in both Q2 and Q3. Despite this catalyst, Google has lagged the category in Q2 and Q3 in terms of both growth and percentage share of market. If there were any year that Google Cloud could pull ahead, it should have been this year.
Alphabet has emphasized that GCP is a priority and the company will be “aggressively investing” in the necessary capex. However, the window of opportunity was wide open this year and aggressive investments would ideally have been allocated during the years of 2017-2018 to stave off Azure’s high-growth years with 80-90%.
Google is Capable but Lacks Focus
There is no argument that Alphabet is an innovator within cloud and a leader in its own right. Across public, private and hybrid cloud, containers are used by 84% of companies and 78% of those are managed on Kubernetes – which has risen in popularity along with cloud-native apps, microservices architectures and an increase in APIs. Kubernetes was first created by Google engineers as the company ran everything in containers internally and this was powered by an internal platform called Borg which generated up to 2 billion container deployments a week. This led to automated orchestration rather than manual and also forced a new architecture away from monolithic as server-side changes were required.
Kubernetes also helps with scaling as it allows for scaling of the container that needs more resources instead of the entire application. Microservices dates back to Unix, while Kubernetes, the automation piece around containers, is what Google engineers invented before releasing it to the Cloud Native Foundation for widespread adoption.
Just as Google was one of the first to need automated orchestration for containerization of cloud-native apps, the company was also one of the first to require low-power machine learning workloads. The compute intensive workloads were running on Nvidia’s GPUs for both training and inferencing until Google made their own processing unit called Tensorflow (TPUs) to perform the workload at a lower cost and higher performance.
Performance between TPUs and GPUs is often debated depending on the current release (A100 versus fourth-generation TPUs is the current battle). However, the TPU does have an undisputed better performance per watt for power-constrained applications. Notably, some of this comes with the territory of being an ASIC, which is designed to do one specific application very well whereas GPUs can be programmed as a more general-purpose accelerator. In this case, the benchmarks where TPUs compete are object detection, image classification, natural language processing and machine translation – all areas where Google’s product portfolio of Search, YouTube, AI assistants, and Google Maps, for example, excels.
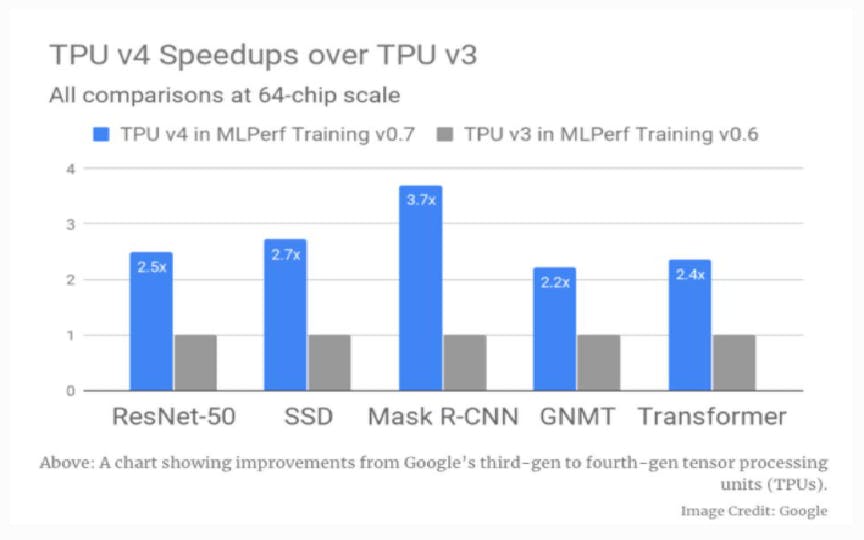
Notably, TPUs are used internally at Google to help drive down the costs and capex of its own AI and ML portfolio and they are also available to users of Google’s AI cloud services. For example, eBay adopted TPUs to build a machine learning solution that could recognize millions of product images.
Unless Google releases an internal technology as open-source, it won’t be adopted by the competitors. This is where Nvidia’s agnosticism becomes a positive as it’s universally used by Amazon, Microsoft, Google —- and Alibaba, Baidu, Tencent, IBM and Oracle. Meanwhile, TPUs create vendor lock in which most companies want to avoid in order to get the best capabilities across multiple cloud operators (i.e. multi-cloud). eBay is the exception here as the company needs Google-level object detection and image classification.
In a similar vein of Google being early to the company’s internal requirements, BigQuery is also a superior data warehouse system that competes with Snowflake (I cover Snowflake with an in-depth analysis here). BigQuery has a serverless feature that makes it easier to begin using the data warehouse as the serverless feature removes the need for manual scaling and performance tuning. Dremel is the query engine for BigQuery.
BigQuery has a strong following with nearly twice the number of companies as Snowflake and is growing around 40%. Due to AWS being a first mover and having a large cloud IaaS market share, Redshift has the biggest market presence but growth is nearly flat at 6.5%.
Point being, Google has important areas of strength and first-hand experience – whether it’s in data analytics, machine learning/inference or cloud-native applications at scale. Google’s search engine and other applications are often the first globally to challenge current architectures and inferencing capabilities.
However, as we see in the contrast between Google and Microsoft in the most recent earnings calls, Google has a hard time prioritizing cloud over the bigger revenue drivers. Meanwhile, Microsoft has a no holds barred approach with one, singular focus: Azure.
Q3 Earnings Calls
The most recent earnings calls from both Microsoft and Google could not have carried more contrast. Google focused primarily on search and YouTube while adding towards the last half of the call that GCP is where the majority of their investments and new hires were directed. Notably, one analyst wondered if the capex investments would eat at margins and produce enough returns.
Microsoft, on the other hand, held an hour-long call that was nearly all-Azure including what the company is doing right now to capture more market share, a laundry list of large enterprises coming on board and strategic partnerships to strengthen its second place standing. The company’s beginning, middle and end was Azure and cloud services.
Here is a preview of how the two opened:
Thanks for joining us today. This quarter, our performance was consistent with the broader online environment. It's also testament to the investment we've made to improve search and deliver a highly relevant experience that people turn to for help in moments big and small. We saw an improvement in advertiser spend across all geographies, and most of verticals, with the world accelerating its transition to online and digital services. In Q3, we also saw strength in Google Cloud, Play and YouTube subscriptions.
This is the third quarter we are reporting earnings during the COVID-19 pandemic. Access to information has never been more important. This year, including this quarter showed how valuable Google's founding Product Search has been to people. And importantly, our products and investments are making a real difference as businesses work [indiscernible] and get back on their feet. Whether it's finding the latest information on COVID-19 cases in their area, which local businesses are open, or what online courses will help them prepare for new jobs, people continue to turn to Google search.