
Google parent Alphabet’s results have further renewed optimism in the stock market as the company beat analysts’ revenue estimates by 4.9% and EPS by 13%. It was led by the growth in advertising and cloud revenues. Advertising revenue grew by 33% to $61.24 billion. The company also announced the 20-for-1 stock split.
On the other hand, Facebook’s results disappointed as it missed analysts' EPS estimates by 4% and only managed to beat revenue estimates by 0.7%. The revenue outlook for the next quarter also disappointed the Street since it only expects revenue to grow in the range of 3-11% YoY. Revenue in Q4 grew by 20% to $33.67 billion. We have stayed away from the stock due to the various privacy issues and failed efforts to enter new markets like stable coins and dating. Not to mention the Cambridge Analytical data scandal.
Snap Inc. reported on February 3rd and results came in relatively stronger than Meta’s. Snap guided for sales to grow 36% YoY next quarter, well above Meta’s guide for 7% YoY growth at the mid-point. The large disparity between Snap and Meta’s forward guide highlights that Apple’s changes to iOS will have varying degrees of impacts on companies in the ad-tech space. The stock is up 59% after hours following the positive report while Facebook is down 28% following its report.
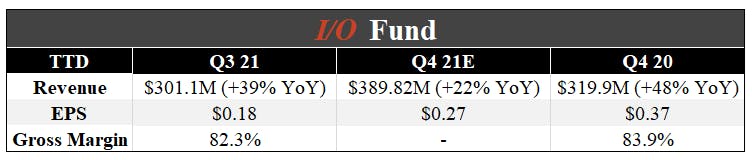
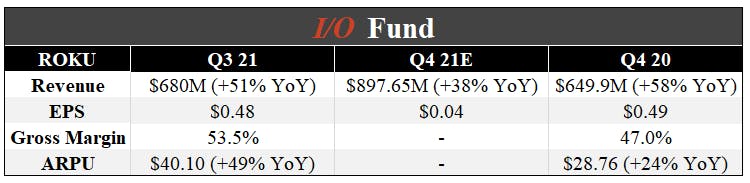
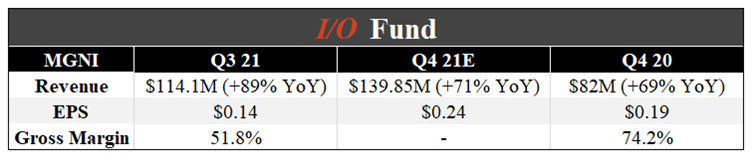
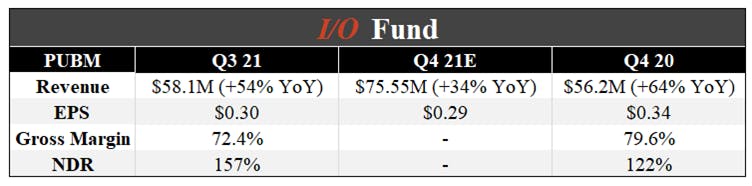
In this earnings preview, we cover Digital Turbine, Twitter, HubSpot, Trade Desk, Roku, Magnite, and PubMatic. To understand valuations across the Ad-Tech companies and how the sector is positioned moving into earnings, please reference our analysis, “I/O Fund’s Ad-Tech Q4 2021 Earnings Overview.”
Digital Turbine – Earnings on February 08th
Source: YCharts, Earnings Reports, and I/O Fund
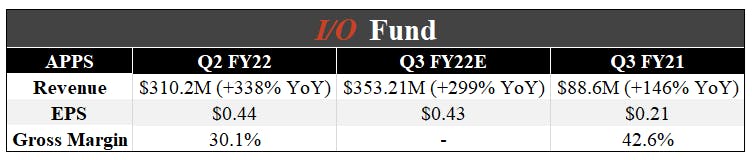
The company’s revenue grew 338% YoY to $310.2 million. However, the company’s results include AdColony and Fyber results which were acquired earlier this year. For better comparison, the management provides pro forma revenue growth i.e. 63% YoY. The analyst’s consensus estimates suggest revenue to grow 299% to $353.21 million in the next quarter.
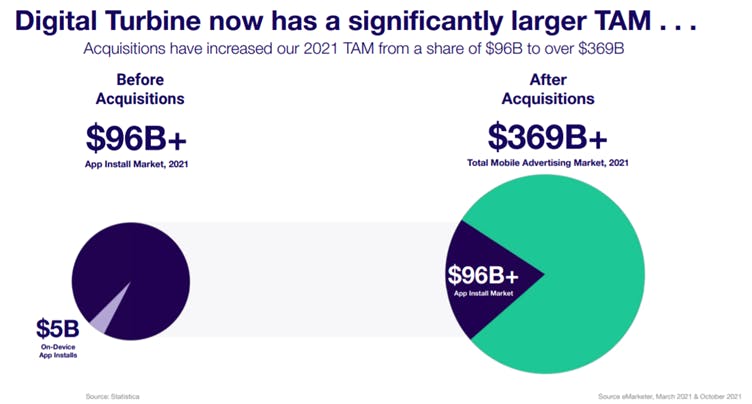
The management believes that the company’s current Total Addressable Market has significantly increased from about $96 billion to about $369 billion due to the various acquisitions.
Source: Analyst Day Presentation
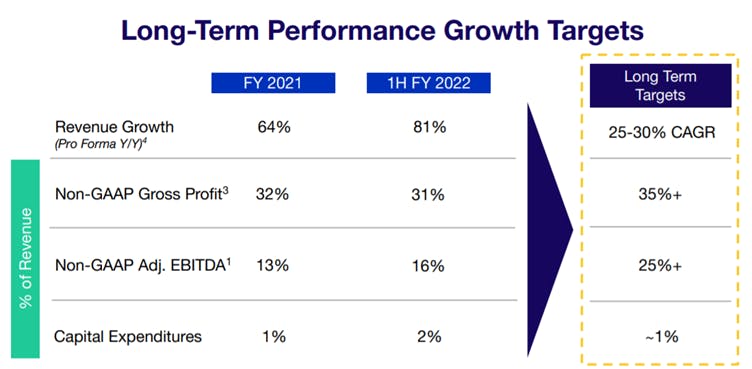
The company expects organic revenue to grow 25-30% in the long term.
Source: Analyst Day Presentation
Macquarie analyst Tim Nollen has an outperform rating and a price target of $80. He is bullish on the company due to “Industry and macro tailwinds (secular growth in mobile gaming and digital ads, alongside lower app store fees); an expansion into brand advertising (a $400 billion-plus total addressable market); upside to current estimates; and the attractive valuation.”
Roth Capital Partners analyst Darren Aftahi has a price target of $90. He is positive on the +25% revenue growth, the SingleTap feature, and also on the company’s various partnerships. “Therefore, not only can [Digital Turbine] expand its wallet share on existing devices, it can capture additional upside and long-tail revenues on new devices as well, especially with market expansion outside the U.S. given various partnerships with Samsung, Telefonica and others.”
Please note that the I/O Fund may or may not agree with the above financial analysts, yet we objectively report what the Street is saying. You may view our previous analysis of the company below:
Q3 Stock Earnings Preview - What to Expect for 7 Ad Tech Stocks
Ad Tech Stock Earnings - What to Expect for Q3 2021 Earnings
Twitter Inc – Earnings on February 10th
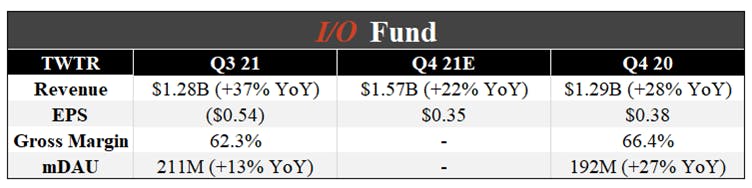
mDAU: Monetizable Daily Active Usage
Source: YCharts, Earnings Reports, and I/O Fund
The company’s revenue grew 37% in Q3 and the consensus forecast suggests revenue to grow 22% to $1.57 billion in the next quarter. It will be the first earnings call for the new CEO, Parag Agrawal. In the Barclays Tech Conference, he mentioned his priorities include smooth transition to all the stakeholders and improving the execution to deliver great products and results.
Truist analyst Youssef Squali has a buy rating and a $50 price target. He believes, “The company's Q4 revenue growth should decelerate sequentially to 22% from 37% in Q3, reflecting tough Y/Y comps, and normalization from peak engagement on the platform due to COVID.” However, he still expects over 20% growth, led by healthy ad budgets, new monetization tools, and mDAU growth.
Mizuho analyst James Lee lowered the company’s price target to $56 from $70. He has a neutral rating on the stock. In his view, “While the management changes are necessary to enable Twitter to accelerate the development, introduction, and update of its products, it could take time for the new strategy to take shape for users and revenues to reach the company's long term targets.”
Read our previous article on the company below:
I/O Fund’s Interview with CoinDesk: Why Square’s Name Change to Block is Defensive
Social Media Projected to Lead Global Ad Spend in 2021
HubSpot Inc – Earnings on February 10th
Source: YCharts, Earnings Reports, and I/O Fund
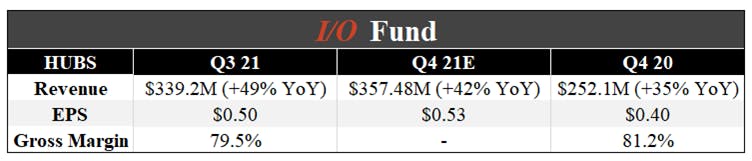
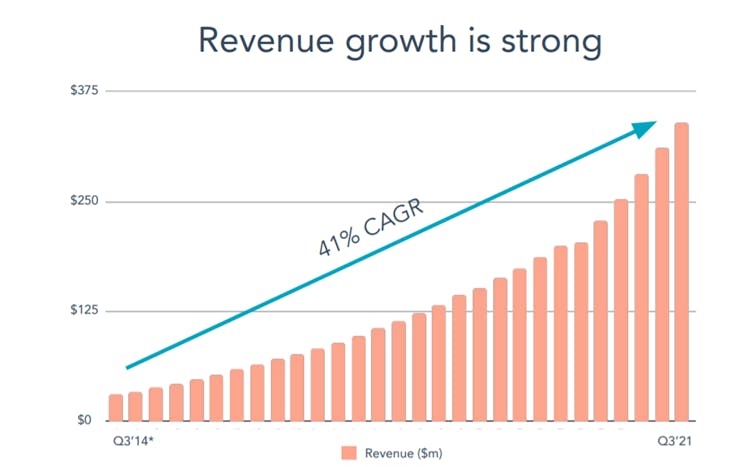
HubSpot’s Q3 revenue grew 49% to $339.2 million. The company’s total number of customers increased 34% to 128,144. The consensus analysts’ estimates suggest revenue to grow 42% in the next quarter. The company’s revenue growth has been good since it grew at a compound annual growth rate of 41% from its IPO in October 2014 till Q3 2021.
Source: Investor Presentation
Mizuho analyst Siti Panigrahi has lowered the company’s price target to $500 from $790 and has a buy rating on the stock. In his view, “Software-as-a-service momentum has stalled thus far in 2022 amid concerns over rising interest rates.” However, the analyst does not see any deterioration of fundamentals despite the market sell-off. On the other hand, Barclays has also lowered the price target to $550 from $800.
Goldman Sachs analyst Gabriel Borges has a buy rating and a $953 price target. The analyst notes that the company responded positively during the early days of the Covid-19 pandemic. He points out that the company lowered the starter package price and introduced a freemium product, which led to the increase of the customers. Over a period of time, he sees a potential for its customers to move to a higher-priced plan.