
The statement that Nvidia stock could reach a $20 trillion market cap by 2030 will trigger plenty of emotion — it sounds fantastical, full of hype, or like a prediction made far too early in the AI cycle. Yet what I offer you below is a data-driven, fundamentally grounded case for how Nvidia can realistically reach a $20 trillion valuation by 2030.
When it comes to Nvidia’s AI story, I’ve offered the earliest and most consistent analysis, covering the company’s AI trajectory earlier than anyone on record. For instance, I told my premium stock research members in September of 2019 that Nvidia would become one of the world’s most valuable companies when it was only a $110 billion valuation (it’s now up 40X). I also publicly stated that Nvidia would surpass Apple when Nvidia had just one-fifth of Apple’s market cap — $550 billion versus $2.5 trillion — writing: “The conclusion to my analysis is the same as the introduction, which is that I believe Nvidia is capable of outperforming all five FAAMG stocks and will surpass even Apple’s valuation in the next five years.” Fast forward and Nvidia stock is up 8X since that analysis.
Last year, when Nvidia stock was valued at $3 trillion, I projected the stock would reach $10 trillion market cap by 2030 — a forecast that no longer looks aggressive now that the stock has briefly broken above $5 trillion. Today, with an even clearer view into the company’s product cadence, software moat, and AI systems dominance, my new, updated thesis is that Nvidia’s stock is on track to reach a $20 trillion market cap by 2030.
This is supported by Nvidia’s aggressive 1-year product roadmap, an impenetrable software ecosystem through CUDA, and its evolution into a full-stack AI systems provider. When these elements are modeled together — alongside the rapid expansion in global AI infrastructure capex — the path to $20 trillion becomes less sensational and more a reflection of compounding fundamentals.
Nvidia’s Data Center Needs to Grow at 36% CAGR to Reach $20T Market Cap
To get down to brass tacks, Nvidia will have to grow its data center segment at a 36% CAGR to reach a $20 trillion market cap if we assume its 5-year median sales valuation of 25 forward PS remains intact. This will put the company’s data center revenue at a run rate in the mid-$900 billion range.
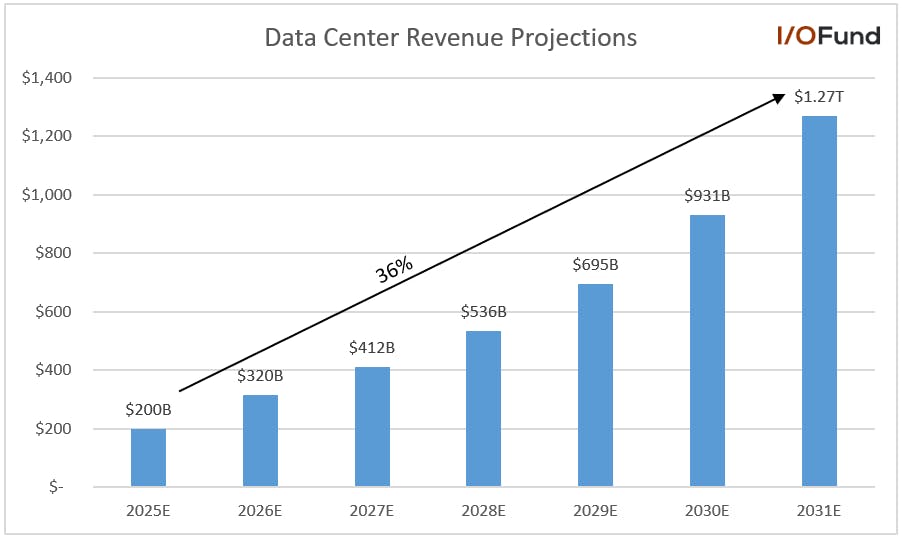
Pictured above: Nvidia stock could see a $20 trillion market cap by 2030 based on a 36% CAGR in its data center segment
About eighteen months ago, I highlighted the importance of Nvidia reaching a $50 billion data center segment by year-end in the article, Here's Why Nvidia Stock Will Reach $10 Trillion Market Cap By 2030, stating:
In my analysis last month on the Blackwell architecture, I made the argument these estimates are too low and that my firm expects we will see a $200 billion data center segment by end of CY2025 propelled forward by the B100, B200 and GB200, including the following points: “Taiwan Semi’s CoWos capacity, which is essential for Blackwell’s architecture, is estimated to rise to 40,000 units/month by the end of 2024, which is more than a 150% YoY increase from ~15,000 units/month at the end of 2023. Applied Materials has boosted its forecast for HBM packaging revenue from a prior view for 4X growth to 6X growth this year.”
The data center segment for Nvidia of $320 billion by 2027 would result in 260% growth for Nvidia’s DC from where it stands today and up 120% from DC revenue estimates for end of CY2025.”
It’s highly probable that Nvidia will blow past the $50 billion data center segment mark this evening - one quarter earlier than my original prediction - which puts the company on the path for a $75 billion segment in Q4 of next year. Tracking these milestones is crucial as it helps support that Nvidia is well on its way to reaching my firm’s brand-new updated estimate for a $230 billion data center quarter by Q4 of 2030 or $930 billion for the full year.
Industry analysts have AI accelerators growing at 31.5% CAGR through 2033 with McKinsey putting out a prediction for $7 trillion in AI infrastructure spend through 2030 with $5.2 trillion going toward building data centers for AI workloads. Dr. Lisa Su and Jean Hsu echoed McKinsey’s projections, stating the AI data center market could be worth $1 trillion by 2030, referring to the addressable market of AI accelerators where AMD competes.
mid
Regardless of which way you dice it, industry estimates point toward AI spend exceeding current expectations. For example, Dr. Su originally had predicted a $500 billion market by 2028. Her updated forecast assumes 35% growth over the next three to five years – the same growth rate required for Nvidia to reach the assumptions underpinning my thesis for a $20 trillion market-cap scenario.
McKinsey’s $5.2 trillion AI infrastructure forecast implies roughly $1.5 trillion in annual AI spending by 2030. Under this framework, our assumptions are slightly on the aggressive side, as they imply Nvidia captures about 60% of total AI capex. Back-of-the-napkin math suggests Nvidia is currently capturing closer to 50% of AI spend, given today’s $405 billion capex run rate and Nvidia’s data center segment set to surpass a $200 billion run rate in this evening’s report.
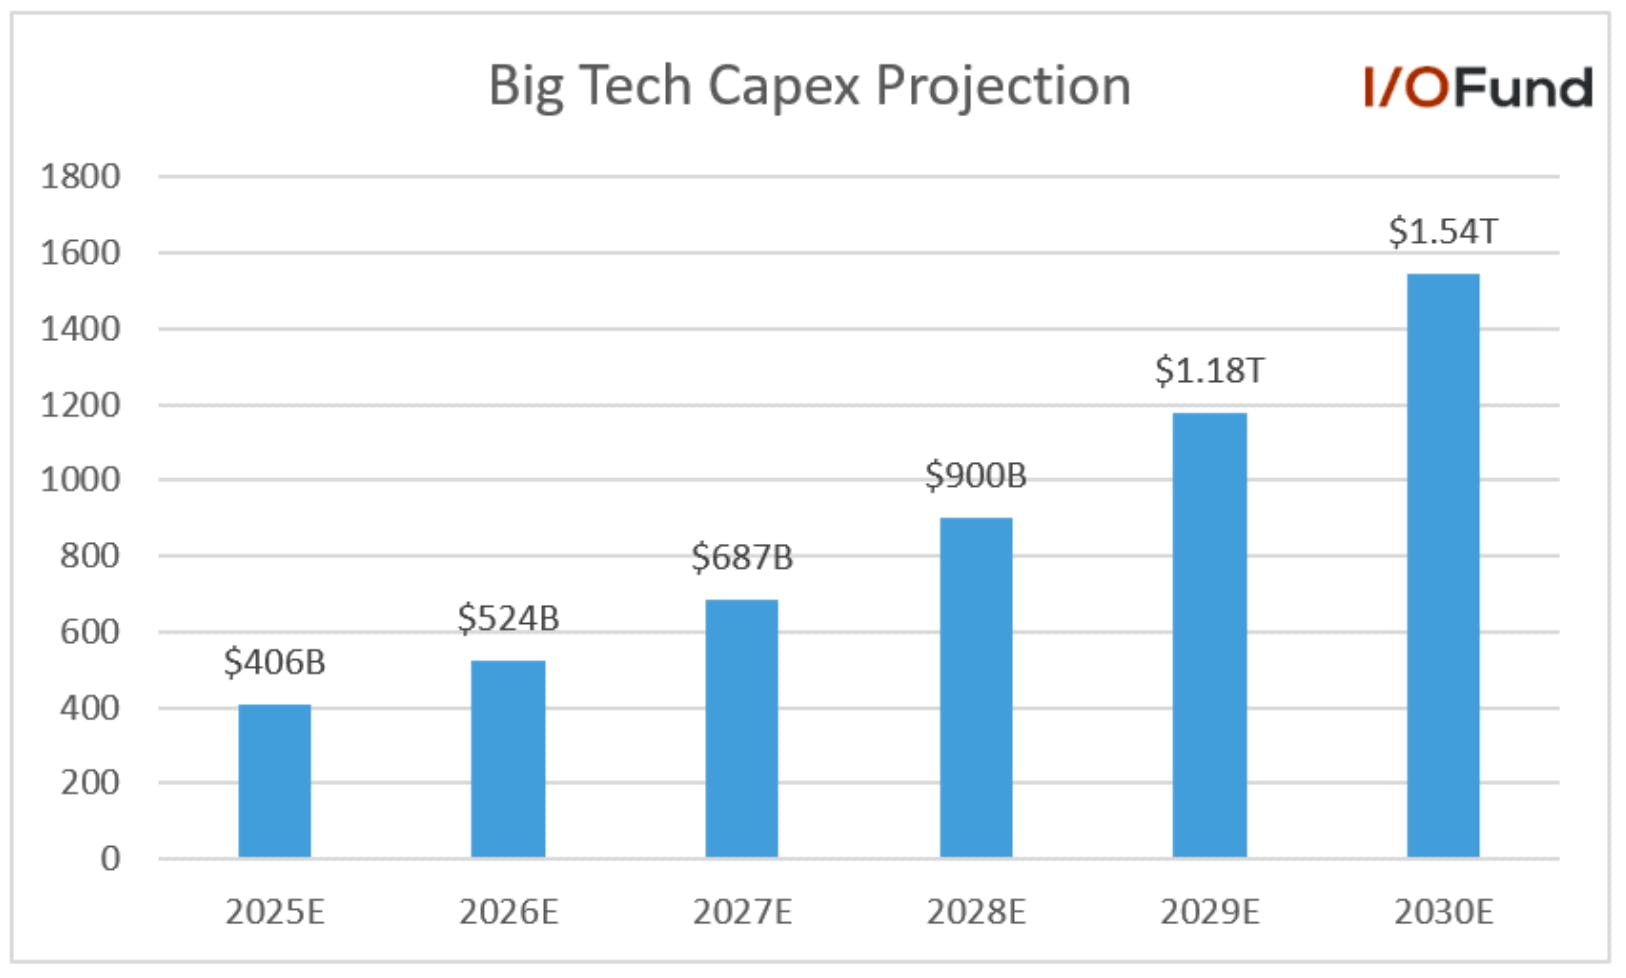
Pictured above: Big Tech AI Capex expected to surge from $406B in 2025 to over $1.5 trillion by 2030, reflecting the massive growth in the AI data center market.
Offense is the Best Defense: Nvidia’s Rapid Product Road Map
The saying goes “the best offense is the best defense” and Nvidia is fully applying this philosophy by leading with its design prowess to ensure custom silicon cannot replace its lead in AI systems. There will certainly be a market for custom silicon as it excels at application specific workloads, which is attractive to Big Tech companies that can use custom silicon to optimize their recommendation engines, run inference at scale and optimize specific internal models. However, custom silicon cannot compete with GPUs and Nvidia’s CUDA software platform on general workloads, which excels at running every model, every framework and every new architecture.
The key reason that Nvidia can reach a $20 trillion market cap by 2030 is because the company is moving its GPU generation cadence to a rapid 12-18 month cycle compared to custom silicon, which is typically on a 3-5 year cycle. Even for Nvidia, the goal of releasing a new GPU generation every year was once unthinkable. Yet this offensive measure will be transformative, turning what was once a cyclical revenue profile into a consistent and compounding growth trajectory.
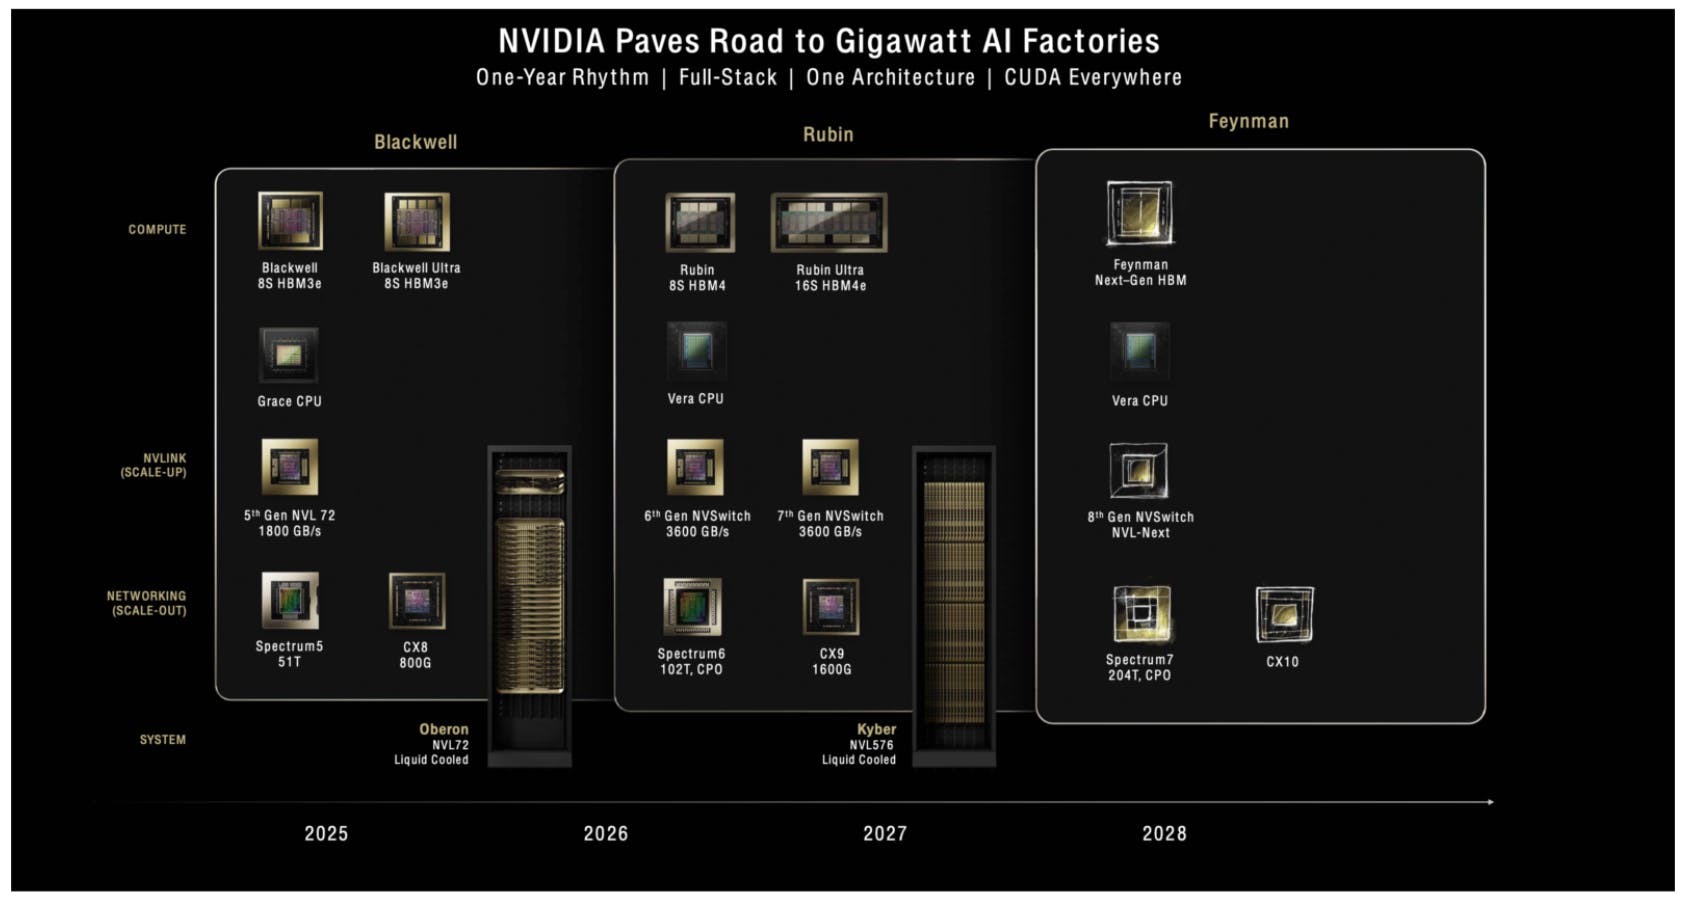
Source: Nvidia GTC Conference, March 2025 Last March, Nvidia revealed their plans for a 1-year product cadence, a key element to the I/O Fund’s thesis that Nvidia can reach $20 trillion market cap by 2030.
At this point, Nvidia is competing with itself with Blackwell offering 208 billion transistors compared to Hoppers 80 billion transistors. By combining 72 GPUs, the Blackwell systems offer 30X to 40X faster inference and are up to 2.5X faster on training. The memory capacity has increased to 192GB of HBM3e for Blackwell and 288GB for Blackwell Ultra. Energy efficiency is also improved by 25X. The 30X improvement in running AI reasoning models is primarily from leveraging FP4 format and fifth-generation NVLink at rack scale level. Blackwell arrived in H1 of 2025 and Blackwell Ultra is shipping now in H2 2025.
Vera Rubin increases the number of GPUs to 144, up from 72 GPUs, for 3.3X higher performance. Vera Rubin doubles the FP4 performance from 20 petaflops to 50 petaflops. The new architecture will offer HBM4 memory and sixth-generation NVLink. Rubin Ultra takes rack-scale to a new level with 576 GPUs compared to Rubin’s 144, with more details to be released in the coming months. Vera Rubin is expected to arrive in H2 2026 with Rubin Ultra in H2 2027.
From there, Feynman is expected to bring to market Gigawatt AI factories, which would be up about 8X from today’s peak cluster size of 150 MW (the largest cluster right now is Colossus at 150MW with plans to expand to 300MW soon). Feynman is expected to arrive in 2028.
5X Hopper: Jensen Huang Reveals $500 Billion Blackwell and Rubin Revenue Visibility
Nvidia laid out an eye-opening stat at the company’s GTC October conference, with CEO Jensen Huang revealing the company has visibility into an astonishing $500 billion in cumulative Blackwell and Rubin revenue through the end of 2026. This is ~5X the lifetime revenue of its Hopper GPUs from 2023 through 2025 which stood at $100 billion.
Huang’s projection calls for 20 million GPU shipments, with 30% of that, or 6 million, having already been shipped; however, considering both generations have two GPUs per chip, in reality, this corresponds to 10 million chip shipments with 3 million already shipped. Huang’s forecast also excludes China but is expected to include attached networking equipment such as Nvidia’s InfiniBand and NVLink.
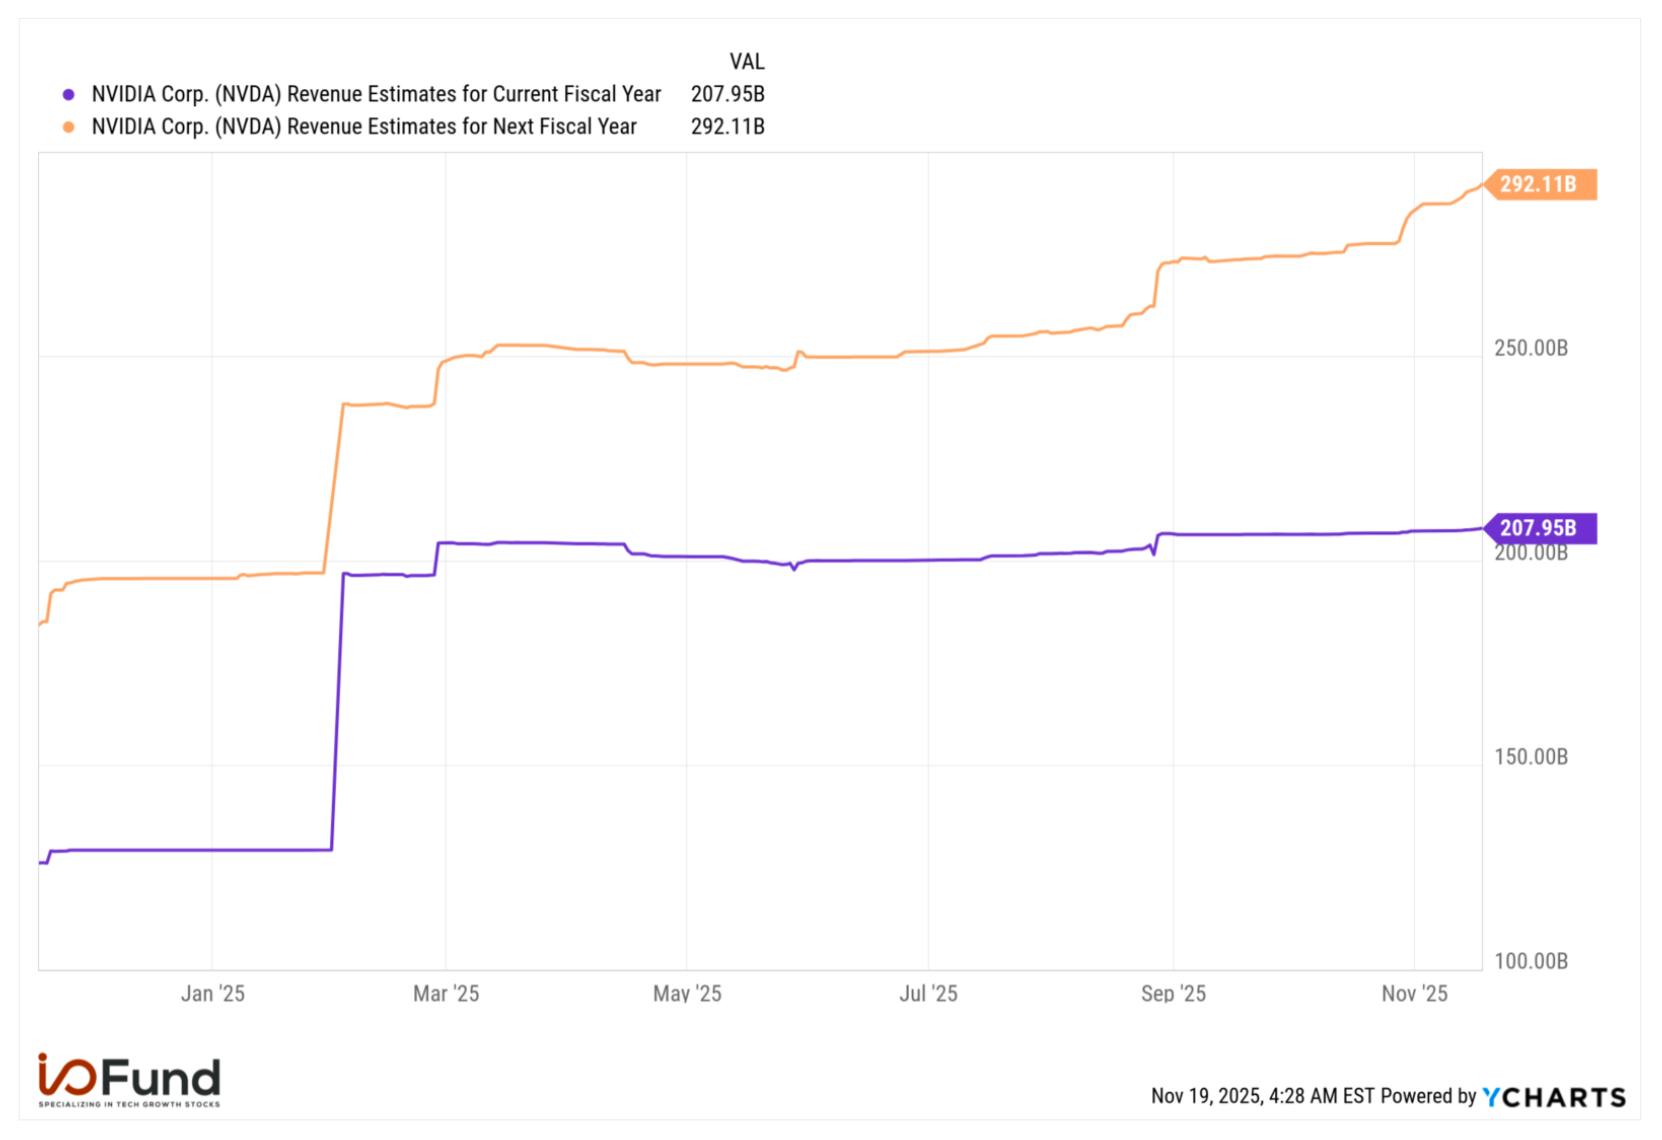
Reading between the lines on Huang’s comments suggests strong upside to Nvidia’s data center revenue through 2026. Over the prior three quarters heading into fiscal Q3’s report, Blackwell revenue has totaled approximately $63 billion. Including Networking over that time frame, total revenue would rise to $78 billion, still a fraction of the total overall opportunity management is projecting. Thus, if we assume that Blackwell and Rubin ramp over the next five quarters, fiscal 2027 data center revenue could be nearly $320 billion, versus estimates for around $270 billion.
This forecast is supported by the accelerated progression in GPU cluster sizes, scaling quickly from 10K clusters just two years ago to hundreds of thousands over the next few years. The first 10K Hopper GPU clusters came online in 2023 and 2024, before scaling 10X to 100K clusters by year-end 2024. Blackwell is picking up where Hopper left off, with clusters expanding from 100K to the hundreds of thousands through 2026 and 2027, such as for Microsoft’s new Fairwater data centers and xAI’s Colossus 2. This scale out of 8-10X growth to reach 1 million GPU clusters over the next few years underpins millions of GPU shipments over the coming quarters.