
This article was originally published on Forbes on May 24, 2023, 07:45 am EDTForbes on May 24, 2023, 07:45 am EDT
My coverage on Nvidia as an AI leader began in 2018 (yes, really – five years ago). Since then, I’ve covered the AI microtrend for this specific stock 27 times on my research site, which is the equivalent of a novel.
I’ve also gone on record to say that Nvidia will surpass the valuation of Apple. That particular analysis compared the impact that AI will have to mobile, with AI adding $15 trillion to GDP compared to mobile’s $4.4 trillion. Mobile brought us three FAANGs: Apple, Google and Facebook. It has been my stance for years that AI will bring us a new set of FAANGs, one of which will be Nvidia.
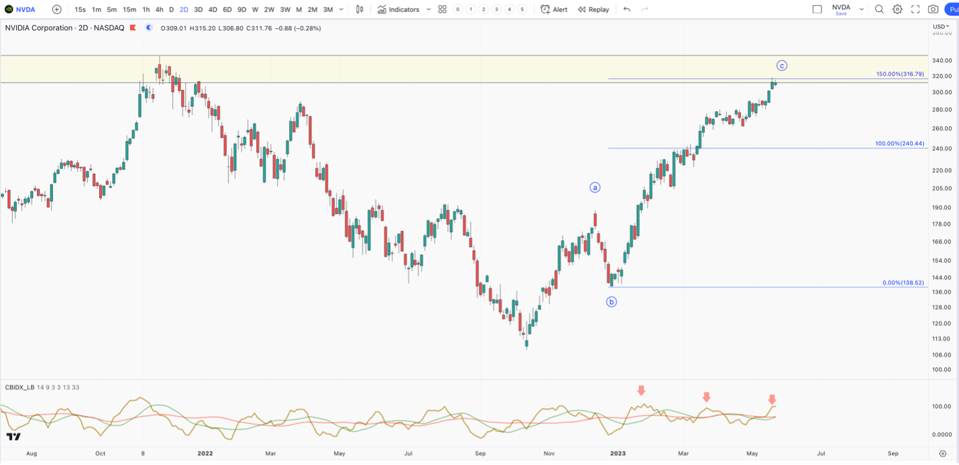
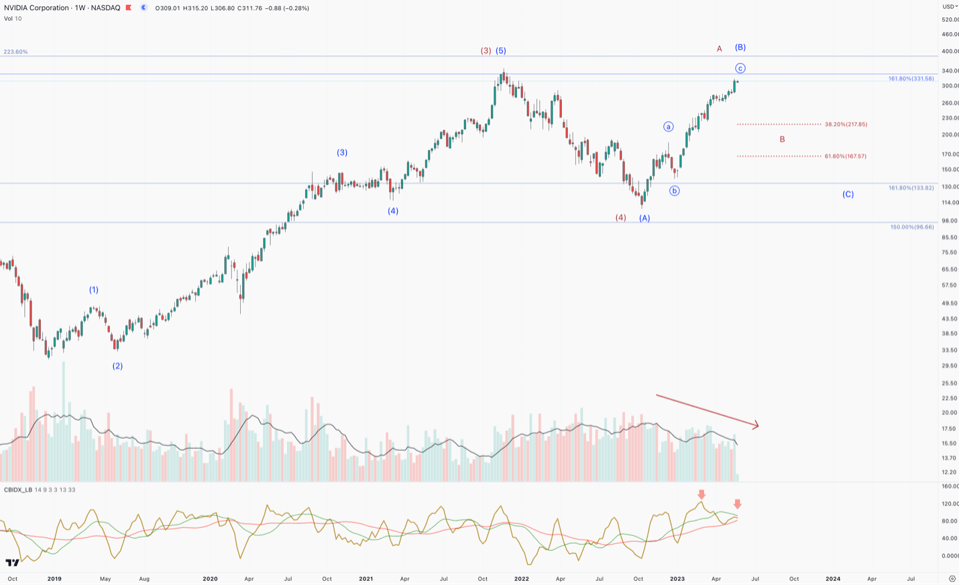
However, now is not the best time to buy the stock. Rather than flatly tell you that while offering no way forward, I want to continue providing value to my readers by discussing when my firm plans to buy the stock again.
But also, we should discuss why the market is rallying on this company specifically. Good investors must do both – understand what makes a company stand out while being patient on price.
AI is Not a Buzzword for Nvidia
Short sellers mistakenly believe that AI is a buzzword for Nvidia. This is true for many stocks, but not for the leader in parallel processing.
Here is what I wrote five years ago on the topic:
Nvidia is already the universal platform for development, but this won’t become obvious until innovation in artificial intelligence matures. Developers are programming the future of artificial intelligence applications on Nvidia because GPUs are easier and more flexible than customized TPU chips from Google or FPGA chips used by Microsoft [from Xilinx]. Meanwhile, Intel’s CPU chips will struggle to compete as artificial intelligence applications and machine learning inferencing move to the cloud. Intel is trying to catch-up but Nvidia continues to release more powerful GPUs – and cloud providers such as Amazon, Microsoft and Google cannot risk losing the competitive advantage that comes with Nvidia’s technology.Nvidia is already the universal platform for development, but this won’t become obvious until innovation in artificial intelligence matures. Developers are programming the future of artificial intelligence applications on Nvidia because GPUs are easier and more flexible than customized TPU chips from Google or FPGA chips used by Microsoft [from Xilinx]. Meanwhile, Intel’s CPU chips will struggle to compete as artificial intelligence applications and machine learning inferencing move to the cloud. Intel is trying to catch-up but Nvidia continues to release more powerful GPUs – and cloud providers such as Amazon, Microsoft and Google cannot risk losing the competitive advantage that comes with Nvidia’s technology.
The Turing T4 GPU from Nvidia should start to show up in earnings soon, and the real-time ray-tracing RTX chips will keep gaming revenue strong when there is more adoption in 6-12 months. Nvidia is a company that has reported big earnings beats, with average upside potential of 33.35 percent to estimates in the last four quarters. Data center revenue stands at 24% and is rapidly growing. When artificial intelligence matures, you can expect data center revenue to be Nvidia’s top revenue segment. Despite the corrections we’ve seen in the technology sector, and with Nvidia stock specifically, investors who remain patient will have a sizeable return in the future.”When artificial intelligence matures, you can expect data center revenue to be Nvidia’s top revenue segment. Despite the corrections we’ve seen in the technology sector, and with Nvidia stock specifically, investors who remain patient will have a sizeable return in the future.”
-Free Newsletter and Seeking Alpha, November 2018 with AI Thesis repeated again in April of 2019Free Newsletter and Seeking Alpha, November 2018 with AI Thesis repeated again in April of 2019
When I wrote that, Nvidia was considered a gaming stock with high-risk exposure to crypto. What is astonishing is that the company was still considered a gaming stock with high-risk exposure to crypto a mere seven months ago.
You may recall, the stock was down 60% last year after a $2.5 billion miss on gaming, and the market was pricing in a long recovery due to Ethereum’s merge to Proof of Stake (PoS). The bears believed the Merge would flood the market with mining GPUs and Nvidia would be unable to overcome this setback.
At the time, there was no mention of Nvidia’s AI lead despite the H100 GPU being released the very next month! despite the H100 GPU being released the very next month! Instead, the market had investors believing that Ethereum, with only 200 million users, which is a smaller user base than Snap or Pinterest, could tank the GPU-juggernaut on the eve of the company’s largest release to-date: the H100 GPU.
The reason I’m emphasizing this is because my firm has worked hard to be a quality resource on tech stocks. Often times there is a major disconnect between the market’s pricing and a tech company’s positioning. There is no greater evidence of this than when Nvidia was down 60% seven months ago yet is the top performing stock in the S&P 500 today.
Sign up for I/O Fund's free newsletter with gains of up to 221% - Click hereClick here
Why the Market is Bulled Up on Nvidia
I want to take the opportunity to explain why Nvidia has the ability to arrive at a valuation that is 3X higher than its peers and in some cases 12X higher.
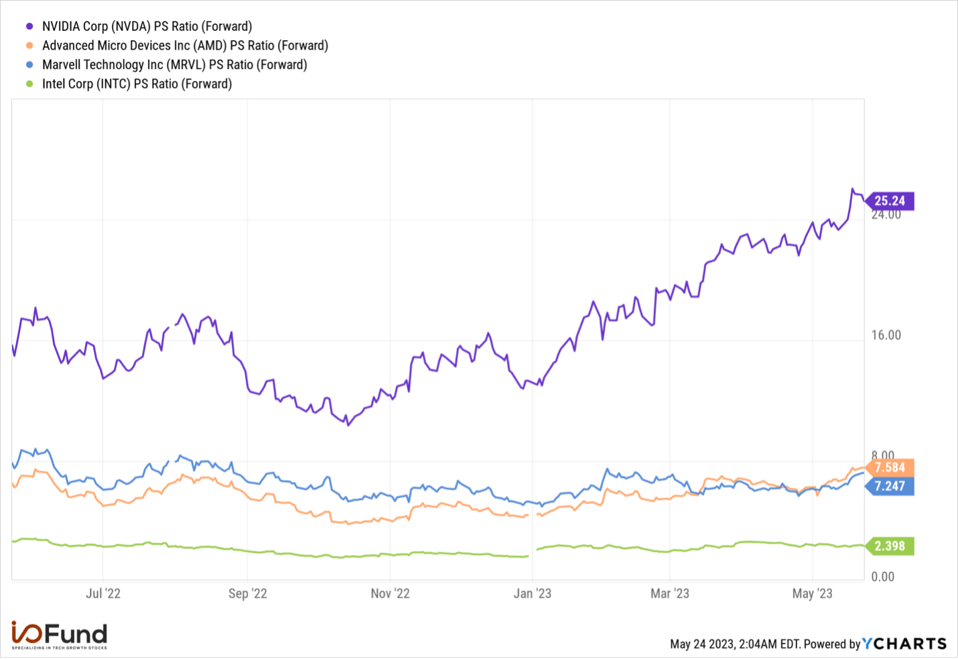
Source: YCHARTS
I’m not defending this valuation, rather I want to explain how it’s possible that smart money continues to buy up here.
The H100 is a Turning Point from Hardware to Software
“The Hopper architecture is ramping and it’s yet again going to disrupt the GPU and AI accelerator market. I’ve written quite a bit about Nvidia […] however, I will keep it simple by saying the A100 GPU is what led the company’s gains since Q2 2020 and the Hopper H100 GPU is what will lead the company’s gains for the next two years.” -Premium Site August 2022, following Nvidia’s $2.5 billion revenue miss.Premium Site August 2022, following Nvidia’s $2.5 billion revenue miss.
Note: the information below is a bit technical, so I’ve bolded the key points for a quick read.
For context, the A100 GPU was a monumental release for Nvidia as the Ampere architecture unified training and inference onto a single chip, whereas in the past Nvidia’s GPUs were mainly used for training.
The result is a 20x performance boost from a multi-instance GPU that allows many GPUs to look like one GPU. The A100 offered the largest leap in performance to date over the past 8 generations. One year later, the Ampere architecture had become the best-selling GPU architecture in the company’s history.
The A100 was special but it’s the H100 that is Nvidia’s iPhone moment. The reason is quite simple – it’s the release that will help Nvidia breakout from hardware and put the company firmly on the map for AI software.
Hardware has allowed Nvidia to become a $700B market cap company, but it is the recurring revenue from AI software that will propel Nvidia into a market cap worth trillions.
You know this story well: the relationship between a hardware company leveraging their position to capture the lion’s share of software —- because that’s exactly what Apple did. My contention is that the iPhone was successful because of the moat iOS developers created, and the additional flywheel from the App Store. I discussed this more in a webinar “The New Kings of Tech”
The H100 delivers 9X more throughput in AI training, and 16X to 30X more inference performance. The company also states in HPC application-specific workloads, the H100 is 7X faster. The goal of the H100 was not only to add more transistors and make the H100 faster, but to also offer function-specific optimizations. This is achieved through the transformer engine.
The transformer engine is one of the key aspects of the H100. Transformers are becoming one of the most popular neural-network models by applying self-attention to detect how data elements in a series influence and depend on one another.
Prior to transformer models, labeled datasets had to be used to train neural networks. Transformer models eliminate this need by finding patterns between elements mathematically, which substantially opens up what datasets can be used and how quickly. Transformers are partial to the parallel processing that GPUs offer.
The Hopper architecture aims to answer one of the bigger challenges facing superfast compute, which is that moving data into traditional servers overloads the CPU and system memory and becomes bottlenecked by PCI-Express.
By improving the bandwidth issue, Nvidia’s goal is to create more demand for their DGX Pod and SuperPod Systems, which in turn, will create more demand for their software.
The DGX SuperPods scale into a super-GPU capable of 768 terabytes per second. To compare, the entire internet requires 100 terabytes per second. This results in 1 exaflop of FP8 AI performance that runs trillions of parameters. FP8 is most commonly used for inference yet may be used for training in the future due to boosting throughput.
Whereas traditional workloads required many connections exchanging small amounts of data, the workloads of the future will require data to be shared quickly between GPUs and storage. This is accomplished by bypassing the CPU and sending data directly to the GPU while using the network hardware to move the data.
This is ideal for enterprise use cases where people are more likely to use Ethernet while AI and HPC workloads continue to use the Quantum-2 based off Mellanox’s InfiniBand.
Not only will Nvidia begin to monetize through software on the DGX systems but accessibility will improve through CSPs, or cloud service providers. This is an attempt to democratize AI development while driving software sales. On a trailing 4-quarter basis, cloud service providers drove 40% of data center revenue. This is important as cloud service providers will help move DGX Cloud along and AI-as-a-service.
Nvidia’s TAM of $600 Billion is Easily and Quickly Achievable
“The conclusion to my analysis is the same as the introduction, which is that I believe Nvidia is capable of out-performing all five FAAMG stocks and will surpass even Apple’s valuation in the next five years.” – Forbes and Free Newsletter, August 2021Forbes and Free Newsletter, August 2021