
This article was originally published on Forbes on Sep 23, 2022,04:33pm EDTForbes on Sep 23, 2022,04:33pm EDT
Nvidia had a big week with GTC 2022 and management is clearly ready to rumble against any excess inventory from crypto mining. The negative catalyst from crypto mining and Nvidia's price action is eerily similar to Q4 2018/Q1 2019 —- yet the company is not the same company it was four years ago. This is apparent by Nvidia flexing some major product muscle by timing it's best-ever gaming release and it's best-ever AI chip to hit the market in October.
We draw important parallels (pun intended) between the last crypto mining selloff and this selloff with key reasons as to why this time the stock's comeback will be quicker.
Nvidia stock has been in the clutches of a steep drawdown after the company has faced nearly every headwind imaginable: United States-China tensions, supply chain disruptions spanning many components, tough comps on the data center, tough comps on gaming, and a less-than-rosy macro environment.
The most impactful headwind, however, was Ethereum’s merge to Proof of Stake (PoS), which ultimately lowers demand for gaming GPUs. This contributed to a $2.5 billion cumulative miss in revenue driven by the gaming segment.
Nvidia’s stock performance in 2018 and 2022 feels eerily similar as the stock sold off 54% in 2018 specifically because of a gaming miss tied to crypto mining. Today, Nvidia is currently 57% YTD.
It took eighteen months for Nvidia to recover its all-time high from the Q4 2018 selloff (Sept 2018 through Feb 2020). Despite the uncanny similarity that 2018 and 2022 may have — Nvidia is actually a much stronger company today than it was four years ago.
Below, we discuss a few key reasons Nvidia stock will recover quicker this time around.
Drilling into Parallels Around the Gaming Miss
During the Q3 2018 results released in November 2018, Nvidia gave Q4 2018 revenue guidance of $2.7 billion, below the analysts’ consensus estimate of $3.4 billion. In January 2019, the company again lowered revenue guidance from $2.7 billion to $2.20 billion, which suggests a total revenue miss of $1.2 billion. Gaming revenue in Q3 2018 was $1.76 billion, up 13% YoY and down 2% QoQ. In Q4 2018, gaming revenue was $954 million, down 45% YoY and down 46% QoQ.
In the most recent quarter ending July 2022, the company missed on gaming with revenue of $2.04 billion, which is 33% lower than the year ago quarter and 44% lower sequentially. The company is expecting a further decline in gaming sequentially for Q3. According to one analyst on the call, they are modeling for a further 30% sequential decline in gaming and professional visualization offset by low to mid-single digit growth in data center and automotive. The CFO affirmed this understanding is correct.
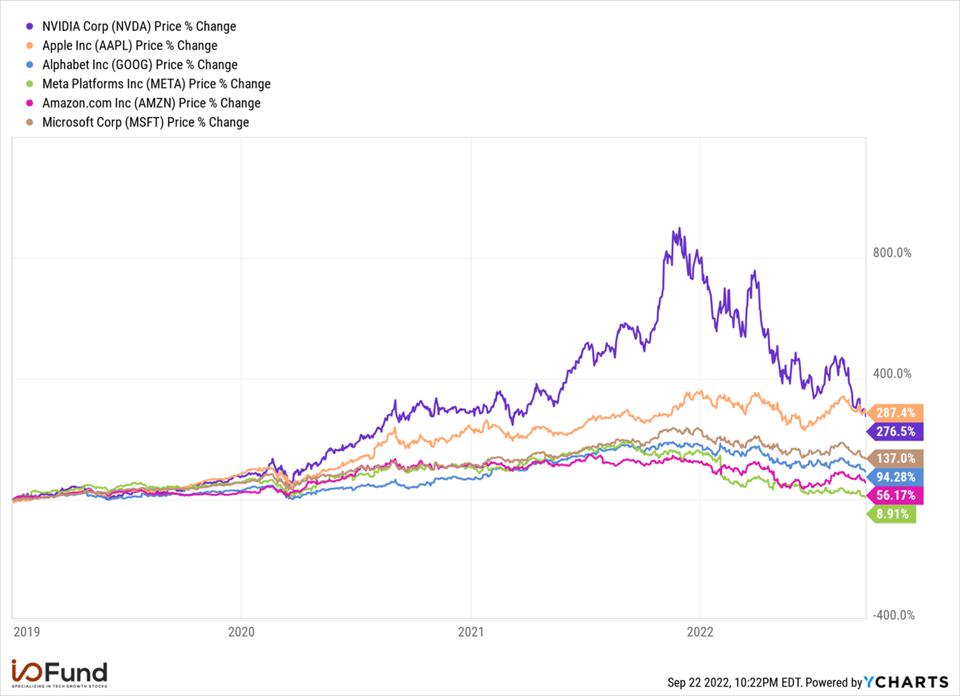
After 2018, although it took Nvidia eighteen months to reclaim its all-time highs, in 2020-2021, Nvidia would go on to stage a remarkable turnaround as the stock led tech mega cap stocks in gains. This was not simply because all tech performed well during those years – if you compare Nvidia to Meta, Amazon and Google, you’ll see something unique occurred with Nvidia that caused the stock to outpace its peers. In all cases except Apple, Nvidia doubled, tripled or quadrupled the performance of other mega cap stocks.
Source: YCHARTS
Perhaps most impressive, Nvidia is still in the lead over all mega cap stocks despite a 57% drawdown this year. It’s the company’s past performance that makes it well worth the time to answer: can Nvidia do it again?
Sign up for I/O Fund's free newsletter with gains of up to 403% - Click hereSign up for I/O Fund's free newsletter with gains of up to 403% - Click hereClick here
Nvidia’s GeForce RTX 40 Series is Perfectly Timed
Next quarter, Nvidia was expected to report $6.92 billion and the company guided for $5.9 billion. This is down from $7.10 billion in Q3 of last year. This will be a 17% decline in revenue. Due to this, analysts expect Nvidia to end fiscal year 2023 with 0.8% revenue growth, or $27.13 billion in total revenue.
It’s not only the top line valuation that is affected by this cut in guidance but it’s the bottom line, as well. In previous quarters, high average sales prices drove $2 billion to $3 billion in operating profits and net profits, whereas in the most recent quarter, the company is reporting $500 million and $656 million, respectively.
The GAAP EPS reported was $0.26 compared to $0.94 in the year ago quarter. Adjusted EPS was $0.51 versus $1.04 for the year ago quarter.
Although it’s tempting to redirect the conversation toward higher-growth segments, the $2.5 billion total miss between two quarters came from gaming and it’s prudent for investors to start here (for now) when analyzing the stock for a potential recovery.
The company stated the miss was driven by both lower units and lower average sales prices including reduced consumer demand. The company is not commenting on crypto as they state they have no visibility here as to how the GPUs are being used, however, it’s certainly contributing to the bulk of this decline.
Notably, AMD reported gaming growth of 32% to $1.7 billion which provides a better picture of reduced gaming demand minus crypto. Nvidia believes some of their weakness is also from preparation for a new product generation that will be announced this month.
Per the earnings call, there are two ways that Nvidia plans to overcome the crypto mining selloff which could produce a faster rebound than 2018.
First, Nvidia is restricting supply on its current gaming model. Per the CFO: “Across those two quarters, the Q2 of ‘23, the Q3 of ‘23, we have likely undershipped gaming to our end demand significantly.”
Following the call, we estimated for our premium members that the amount undershipped is a minimum of $1 billion. The reason behind this is to help keep prices stable and to increase demand for the RTX 40 Series.
Second, Nvidia announced its GeForce RTX 40 Series at the GTC 2022 Conference this week.
The new Ada Lovelace architecture which uses 76 billion transistors and a 4nm production process. In the keynote, the CEO stated: “Nvidia engineers worked closely with TSMC to create the 4N process optimized for GPUs. This process let us integrate 76 billion transistors and over 18,000 CUDA cores, 70% more than the Ampere generation.”
The improvement from 8nm to 4nm means more transistors on the GPU, which results in better performance as the 4nm processes data faster.
In the gaming world, this much anticipated release is expected to be 2-4X faster than the RTX 3090 Ti. The flagship AD102 GPU model will have 144 individual streaming multiprocessors (SMs) in one die compared to 84 SMs in the Ampere architecture. As stated, the AD102 will also have a 70% increase in CUDA cores over the RTX 3090 Ti.
In addition to this, Nvidia is releasing a new feature called Shader Execution Reordering (SER) which will improve ray-tracing performance by 3X with 25% faster frame rates. Rather than deliver workloads sequentially, the GPUs are able to reorder the workloads to process more workloads at once which results in more power and better performance.
Deep learning super sampling (DLSS) refers to using AI to predict the next pixel. The new DLSS 3.0 not only predicts pixels but will also use AI to predict frames. This results in “up to four times” better performance over traditional rendering.
The first release date for the RTX4090 models is October 12th with a starting price of $1,599. There is a second release date in November for the RTX4080 models with prices of $1,199 and $899. Notably, mid-range RTX 40 series will outperform the previous generation’s high end models. This is due to the Ada Lovelace architecture which offers 1,400 Tensor TFLOPs versus 320 Tensor TFLOPs which means the DLSS is superior and the high-end RTX 30 Series cannot compete with the mid range RTX 40 series.
The popularity of this release will help determine if Nvidia can stage a comeback in the gaming segment. Here is what analysts are saying:
“Morgan Stanley analyst Joseph Moore said his "biggest takeaway" from the keynote at Nvidia's GTC conference were the higher prices of gaming GPUs, which increases his conviction about the pace of gaming revenue recovery next year. Prices that are 28% higher than the baseline price from two years ago for the higher volume 4080 should drive material growth in revenue, said Moore, who sees revenues in the gaming segment rebounding from the current quarter run rate of $5.5B or so to $9.5B next year.”
“Given the channel inventory work downs in the July and October quarters, the products should be "strong demand catalysts" into 2023, Harlan Sur of Chase tells investors in a research note.”
Nvidia Continues to Build a GPU Moat with H100
In 2018, we stated in our free newsletter that Nvidia had built a moat in the GPU-powered data center. This was a bold statement as the company would go on to have negative year-over-year data center revenue in 2019. Yet, fast-forward and it’s quite clear that Nvidia is unshakeable in this segment, which has surpassed gaming as Nvidia’s most valuable segment.
I’ve written quite a bit about Nvidia, which you can reference here and also here. However, I will keep it simple by saying the A100 GPU is what led the company’s gains since Q2 2020 (detailed here) and the Hopper H100 GPU is what will lead the company’s gains for the next two yearsdetailed here) and the Hopper H100 GPU is what will lead the company’s gains for the next two years.


