
This last week, we saw Tesla take advantage of the lack of information available on autonomous vehicle technology. Unfortunately, the facts around autonomous vehicles are elusive as PR copywriters fuel journalists, who are churning out content to meet deadlines.
For starters, to get machines to respond like humans, within milliseconds, is one of the most difficult problems that technologists have aimed to solve. The truth about autonomous vehicles includes regulations, production cycles, and delays in implementation. I predicted when I wrote my analysis six months ago, that the gap between investor expectations (perception) and commercial deployments (reality) had created an autonomous vehicle bubble that would pop in 2019.
One example is Intel, which has been propped up under hope that AV is close to deployment. “How Intel Plans to Win Self-Driving Cars,” is a headline published by Motley Fool and there are dozens of more like it. Meanwhile, six days ago, Intel laid off dozens from the autonomous vehicle program in Palo Alto.
In my updated analysis, I want to dive deep into the reality around autonomous vehicles, and draw some important conclusions as to why it is impossible to deliver robotaxis in 2020. This will help investors and consumers understand a few basics around what needs to happen for full autonomy so that both constituents can make better, informed decisions. Investors should especially pay close attention because for the handful of companies who are overhyped and pushing for sky-high valuations too early, there are many more quality small cap and mid cap stocks that are underhyped and perfectly timed relative to valuation.
Truth Number One: Driver-Assisted Vehicles
We are at level 2 autonomy and all auto manufacturers are halted at this level. Tesla cannot release more advanced features than what Ford, Mercedes, or BMW have on the roads today. On that note, autonomy is a misnomer as Level 2 is considered “driver-assisted.”
Please note: I wrote about the disconnect between SAE’s AV levels and reality around commercial deployment long before it appeared in the press. My previous analysis is a must-read for anyone interested in more information on the AV bubble or AV software.
Here is an overview from my analysis published in October of 2018:
Level 0-1: No automation and driver assistance. Level 2: Partial automation. The vehicle assists with steering and accelerating functions. Level 3: Conditional automation: The vehicle controls the monitoring of environment using sensors. The driver’s attention is critical but the AV system runs the safety critical functions. Does not require human attention under 37 miles per hour Level 4: High automation: Vehicle is capable of steering, braking, and accelerating, as well as responding to events and changing lanes. Vehicle cannot determine dynamic instances such as traffic jams or merging onto the highway. Level 5: Complete automation. No human attention required. No need for pedals, brakes or a steering wheel. The AV controls all critical tasks, monitoring of the environment and identification of unique driving conditions like traffic jams.
Level 2 (where we are today) and Level 3 (where we might be in 2-3 years from now) are not considered autonomous. These levels are considered “driver-assisted.” Audi, not Tesla, was going to be the first to commercially deploy a Level 3 autonomous vehicle in January of 2019 with the Audi A8 Traffic Jam Assist, but has been delayed due to “foggy federal regulatory framework, infrastructural differences, and a lack of consumer understanding of self-driving technology.”
As of January 2019, any presentations on releasing Level 3 driver-assisted technology (again, the next level is not categorized as autonomous) would be remiss to not address the regulatory framework that is preventing deployment of Level 3 at this time. The presentation would also be remiss to not discuss why regulations would skip Level 3 and go to Level 4 – or as robotaxis would require, Level 5 commercial deployment.
Truth Number Two: AVs Heart 5G
5G was absent from Tesla’s recent presentation on autonomous vehicles, which is odd to say the least. 4G speeds are simply not fast enough for the sensors on a vehicle to react or brake in milliseconds. We need the network capacity of 5G for machines and vehicles to think as fast as humans, and to remove latency in critical moments.
On my podcast about 5G, I recently interviewed Anthony Pellegrino from a disruptive startup called Mutable, which provides edge computing for microdata centers. Microdata centers are miniature data center racks that enable faster, easier and a more cost-effective way to build and deploy applications at the network edge. Because 5G microdata centers will be more omnipresent, so to speak, and located closer to the device or vehicle, you can improve response time from 60 milliseconds to 20 milliseconds. In the case of braking for a pedestrian, these 40 milliseconds are crucial.
Pellegrino provided the following example in the podcast, “Think about Ford, if they want to do autonomous vehicles, are they going to put redundant compute literally in thousands of locations, or are they going to, when a car comes by in the neighborhood, and you’re connected to 5G, send a request across? You can just spin up an instance of these applications on demand, and use it when it’s needed … that’s very cost effective.”
At MWC in Barcelona this past year, a semi company called Einride, set up a simulator for autonomous driving that allowed attendees to demo driving an 18-wheeler from roughly 3,000 miles away. The speed was limited to 5 kilometers per hour for safety purposes andEricsson provided Einride with a 5G network for the successful simulation.
Although 5G has deployed in two cities, Chicago and Minneapolis, we will need the semi-ubiquitous presence of 5G for the commercial deployment of personal-use vehicles on public roads. For instance, one critical feature of 5G is that the signal from connected devices do not need to travel to a cellular tower first in order for vehicles to quickly send and receive information. One reason many auto companies are putting the next level of AV deployment at 2022 when many optional autonomous features will be released, is that 5G networks will be available. However, fully autonomous (without human driver) will still have serious hurdles as 5G is an urban technology rather than a rural technology – and privately owned robotaxis, without a human driver, deployed outside of urban areas is skipping many crucial levels and steps, that it should not even be discussed right now.
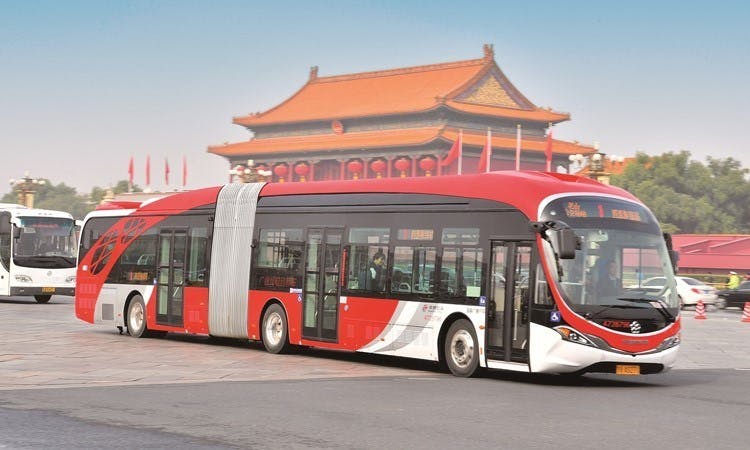
Keeping this in mind, we are more likely to see 5G-enabled autonomous transportation within urban areas for mass transportation before you or I have the ability to buy an autonomous vehicle from a dealership. China hopes to do this by 2022 through a partnership with Mobileye/Intel, Beijing Public Transport Corporation (BPTC), and Beijing Beytai.
Truth Number Three: Driverless is Prohibitively Expensive
Notably, there are vehicles that have all of the data onboard and do not need to communicate with IoT sensors or the cloud to brake or respond to obstacles. Caterpillar is currently operating driverless machinery today although these machines drive in areas where there are few unknown obstacles, such as pedestrians or bicyclists. However, self-driving with computing resources built into the machine or vehicle is prohibitively expensive today for personal vehicles and for most industries outside of the manufacturing industry or defense industry.
Historically, autonomous vehicle technology was first developed for the military to prevent deaths from roadside bombs. I spoke with Michael Fleming of Torc Robotics in a separate podcast interview, who has been developing AV software for the defense industry for over a decade, and is the software provider for the Caterpillar driverless machinery currently operated today.
Here is what Fleming said about the current state of AV software “Self-driving is a very difficult problem. It’s a very complex problem, but in reality, think of the software architecture as hundreds of different software modules all being interconnected, which is pretty incredibly complex. Now, we’ve been working in this space for over 12 years, and these complex technologies do not come together in short order. And for that reason, I think it’s important that the organizations take a slow and methodical approach to not only developing, but deploying self-driving vehicles.”