
This article was originally published on Forbes on Updated Aug 30, 2024, 08:59am EDTForbesForbes on Updated Aug 30, 2024, 08:59am EDT
Our firm extrapolated supply chain data to conclude that Blackwell is in production at TSM and SMCI last week in the analysis: Nvidia Stock: Blackwell Suppliers Shrug Off Delay. The media was making much ado about nothing (and astonishingly, still is) despite crystal clear confirmation from Nvidia’s management team that all is well.
Given these delay rumors, it was widely expected that Nvidia’s management would provide some transparency in Q2 as to the status of Blackwell. I joined ‘Making Money’ on Fox Business Network shortly before Nvidia’s report, telling host Charles Payne that “we are getting bullish signals from the supply chain,” such as TSM’s HPC growth and Super Micro’s liquid cooling growth, and that I “fully expect Nvidia’s management team to calm any concerns about the outlook for Blackwell.”
Direct liquid cooling doesn’t lie as it’s intricately linked to the Blackwell launch, implying that Blackwell would indeed ship by Q4 – and Nvidia just confirmed that (multiple times) in Q2’s release:
“Blackwell production ramp is scheduled to begin in the fourth quarter and continue into fiscal 2026. In the fourth quarter, we expect to ship several billion dollars in Blackwell revenue.”
Later in the call, Jensen Huang stated: “There were no functional changes necessary. And so we're sampling functional samples of Blackwell — Grace Blackwell in a variety of system configurations as we speak. There are something like 100 different types of Blackwell-based systems that are built that were shown at Computex. And we're enabling our ecosystem to start sampling those. The functionality of Blackwell is as it is, and we expect to start production in Q4.”
We had published for our free readers going into the print that the valuation was stretched, and it would require fiscal year revisions to create room in the valuation. As you’ll see below, we got a few revisions today, which is paramount for the stock price. Will these upward revisions be enough to sustain the price? We look at this and more below.
Q2 Revenue Beats Estimates
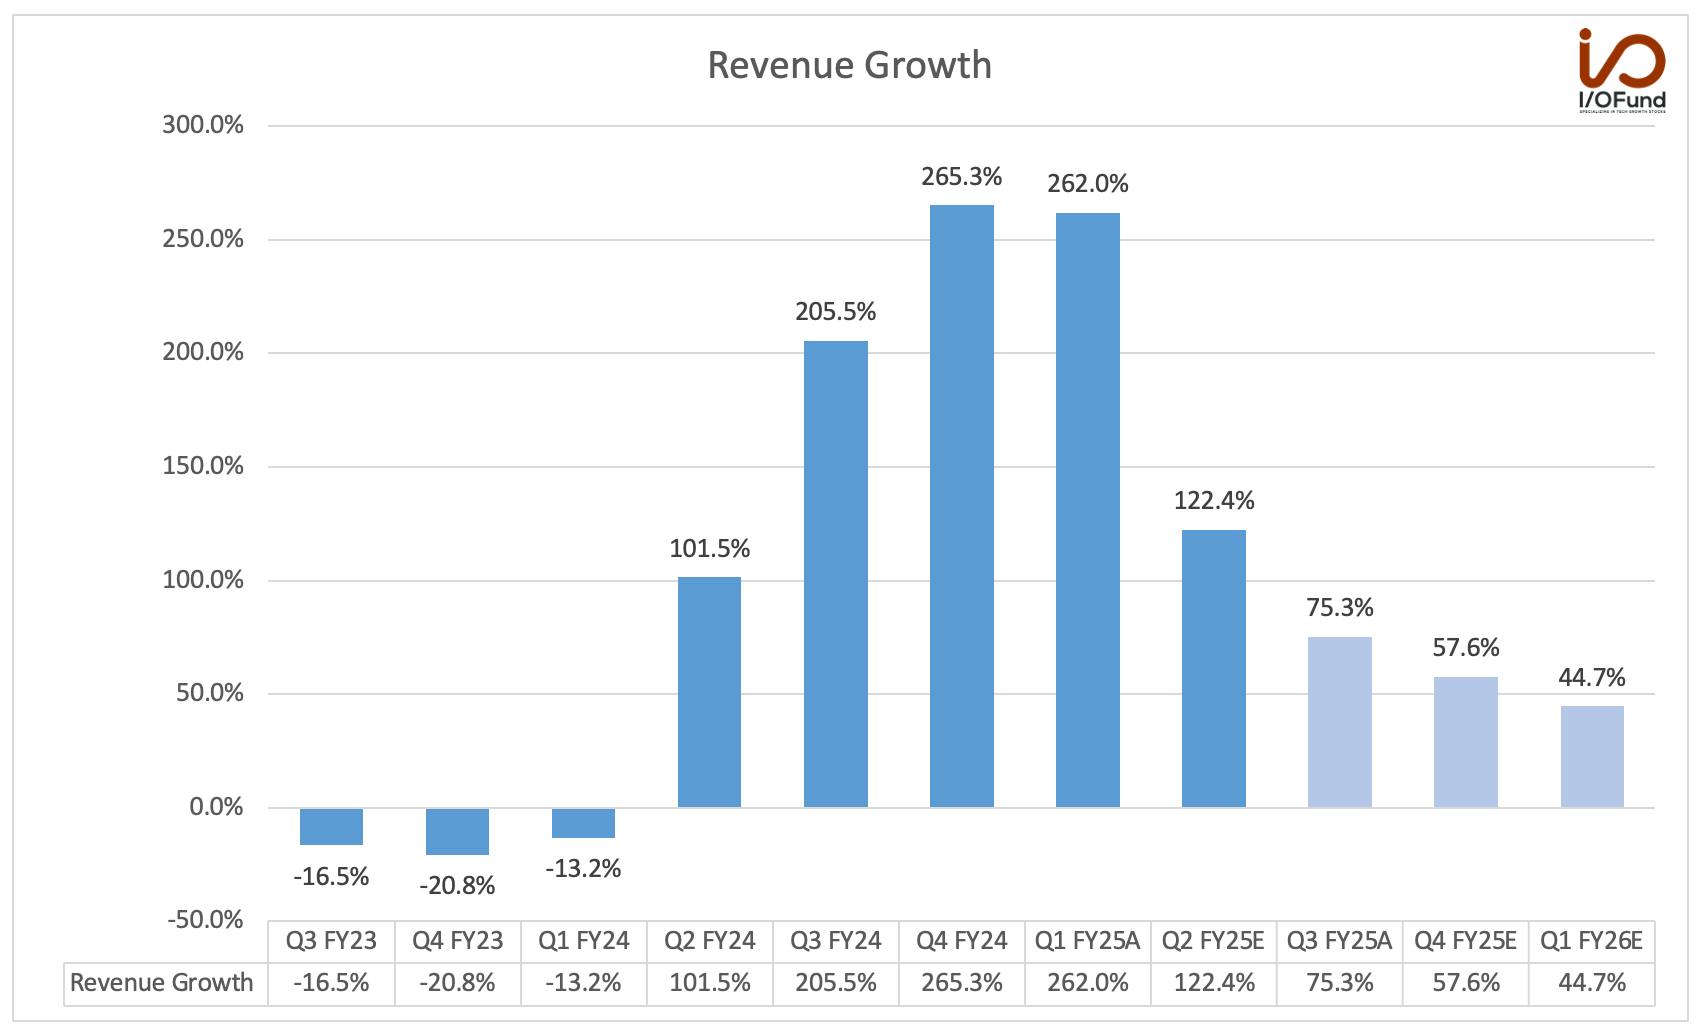
Q2’s revenue of $30.04 billion increased 122% YoY and 15% QoQ, with management pointing out that “customers continue to accelerate their Hopper architecture purchases while gearing up to adopt Blackwell.” This marked a $1.3 billion beat to the consensus estimate for $28.75 billion. It also was a deceleration from 262% YoY growth in Q1, as Nvidia is now facing tougher comps against the vertical ramp of Hopper last year. GAAP EPS of $0.67 beat estimates by $0.03, and represented YoY growth of 168% and QoQ growth of 12%.
Nvidia guided for Q3 revenue of $32.5 billion, once again above consensus estimates, though it was only $700 million higher than the $31.77 billion estimate at the midpoint. This represents growth of 79.4% YoY at midpoint, compared to the estimate for 75.3% growth next quarter. Despite this being one of the ‘smaller’ beats in recent quarters, it’s a testament to the strength of Nvidia’s demand to guide for $2.5 billion sequential growth primarily based on Hopper demand with no contribution from Blackwell.
Source: I/O Fund
Sign up for I/O Fund's free newsletter with gains of up to 2600% because of Nvidia's epic run - Click hereClick hereClick here
Data Center Strength Visible with Blackwell on Tap
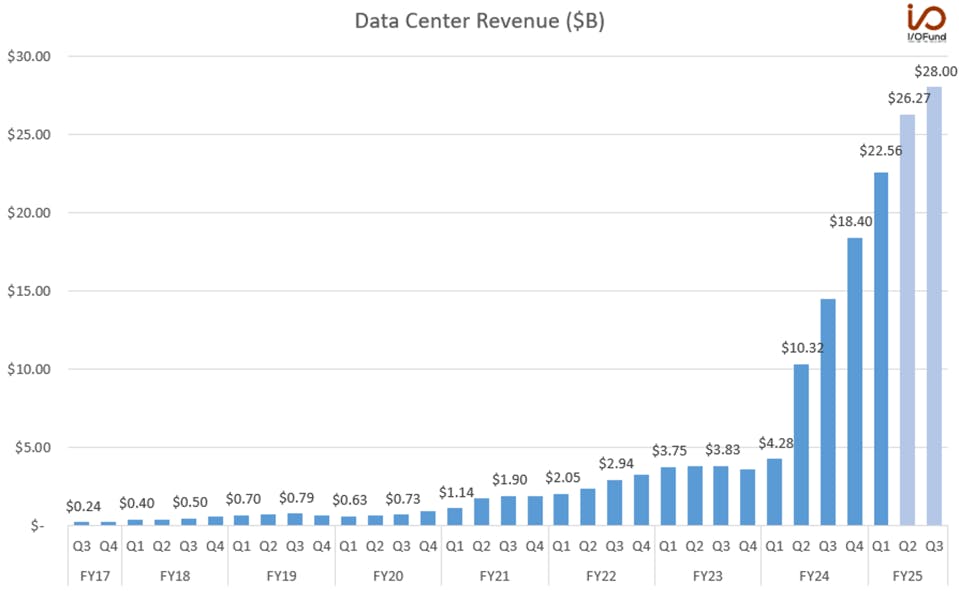
Data center revenue surpassed a $105 billion annualized run rate this quarter, up from $90 billion annualized last quarter, as Nvidia reported $26.27 billion in data center revenue, up 152% YoY and 16% QoQ. Nvidia said that “Hopper demand is strong, and shipments are expected to increase in the second half of fiscal 2025,” while Blackwell is on track to ramp in Q4 with “several” billions in revenue expected that quarter.
Notably, purchase commitments and obligations for inventory and capacity rose nearly 48% QoQ to $27.8 billion, including “new commitments for Blackwell capacity and components,” another signal that Nvidia is prepared to ramp in full-force come Q4.
In the segment, compute revenue was $22.6 billion, up 162% YoY, while networking revenue was $3.67 billion, up 114% YoY. In networking, Nvidia noted that InfiniBand and Ethernet drove growth in the quarter, and the 16% QoQ growth included “a doubling of Ethernet for AI revenue.”
Source: I/O Fund
Nvidia’s Q3 revenue guide implies data center revenue above $28 billion to $28.5 billion, which we had modeled in our pre-earnings analysis earlier this week.
Delay Concerns Cleared, But Valuation Looks Stretched
Nvidia cleared the delay concerns for Blackwell, saying that they “shipped customer samples of our Blackwell architecture in the second quarter. We executed a change to the Blackwell GPU mask to improve production yield. Blackwell production ramp is scheduled to begin in the fourth quarter and continue into fiscal 2026,” with several billion in Blackwell revenue expected in Q4. Purchase commitments reiterated that Nvidia is serious about launching on schedule, and lining up the capacity and components to launch in full-force by the end of the year.
I spoke with Yahoo Finance on Thursday morning following the report, reemphasizing that the delay concerns were “completely thrown off the table last night. … Wall Street obviously is very closely tied to estimates, and we never saw revisions downward based on the so-called delay. … Nvidia beat, and they’re saying Blackwell is basically on time,” which is “not a concern — if anything, it’s extremely bullish.”
However, I cautioned on the valuation: “When you have a high-flyer like Nvidia, you get stretched at times. Going into the print, we warned our members that this valuation is looking a little toppy. What we need is for the fiscal year estimates next year to go up, so we’re in a waiting game for analysts to revise their estimates upward, which eventually they will, but until then the valuation is stretched.”
This morning, while I was being interviewed by Yahoo, we’ve already seen analyst estimates for Nvidia’s revenue revised higher following the report: