
This article was originally published on Forbes on Updated Aug 8, 2024, 09:24pm EDT
The major theme over the past month in Big Tech and AI semiconductors has been the durability of demand: essentially, what is Big Tech’s return on more than $150 billion in capex over the last twelve months (primarily for AI infrastructure), and if the companies can generate a substantial enough return from AI products to continue catalyzing GPU demand and revenue for Nvidia.
Though Big Tech’s June quarter earnings were met mostly with rather gloomy reactions, management teams reiterated positivity on the long-term potential of generative AI products and services, and the need for continual investment in AI infrastructure.
Microsoft stands out as the clear leader with multiple different monetization pathways from generative AI, whether through Azure or GitHub Copilot, while AWS has seen growth reaccelerate as AI’s revenue contribution reaches a multi-billion-dollar run rate.
Alphabet has touted billions in AI related revenue, while Meta is seeing an in-house effect with AI playing an increasingly large role in engagement and ad delivery across Meta’s family of apps.
The Quest for ROI
Sequoia Capital recently raised an alarm on Big Tech’s massive AI investments, and whether companies will be able to realize large enough returns to justify these expenditures, calling it “AI’s $600B Question,” in a follow up to their September 2023 analysis and the $200B question. Sequoia’s analysis suggests that based on Nvidia’s annualized $150B data center run rate by Q4, the revenue required for payback on capex would be $600B, based on a 50% software margin for CSPs and 50% operating cost from GPUs.
This sparked fears as Big Tech is not yet able to convince investors or analysts that these investments will pay off. This has led to analysts pressing management over monetization and potential overinvestment in capacity in earnings calls.
Lead Tech Analyst Beth Kindig recently discussed this with Bloomberg Asia following Alphabet’s earnings, saying that investors are looking for an ROI from Big Tech in terms of quarter-over-quarter revenue accelerations from AI in the cloud, and if these accelerations are enough to justify the amount of capex spent.
Sign up for I/O Fund’s free newsletter with gains of up to 2600% because of Nvidia’s epic run – Click here.
Capex Growth Continues
We recapped Big Tech’s capex and commentary following Q1’s earnings in mid-May for our newsletter readers, saying at the time that Big Tech “will likely commit upwards of $200 billion, maybe even $210 billion, combined in capex this year, predominantly for AI infrastructure – from data center construction and expansion, to GPU procurement and custom silicon efforts and more.
It’s no wonder the four are boosting capex by more than 35% YoY, given positive outlooks on AI’s potential to drive revenue growth in the billions and how demand continues to outstrip GPU supply.”
Following the recent Q2 reports, Big Tech did, indeed, commit $210 billion to capex.
In the first half of 2024, Alphabet, Amazon, Meta and Microsoft spent nearly $104 billion in capex, up 47% YoY, with more than half of that total coming in Q2. Microsoft and Alphabet saw the largest YoY increases among the four, driving capex 78% and 91% higher for the first half of the year, respectively.
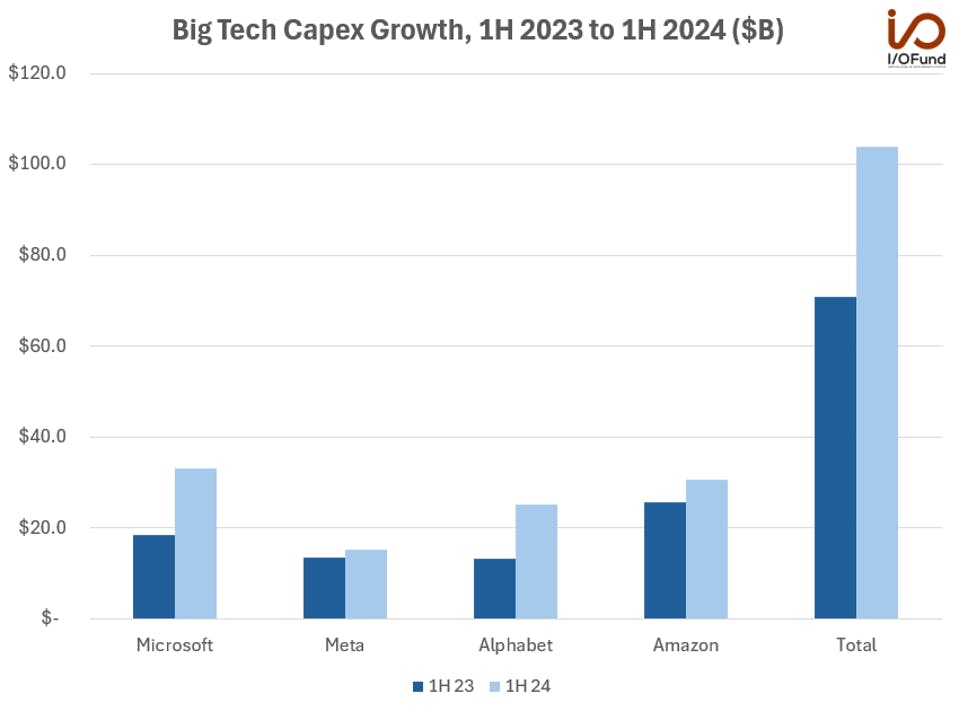
Microsoft: Capex this quarter was $19 billion, an increase of nearly 78% YoY from $7.8 billion in the year ago quarter, and a QoQ increase of almost 36% from $14 billion last quarter. Microsoft’s fiscal 2024 (ending June) capex was $55.7 billion, up nearly 75% YoY, and management is guiding for a YoY increase in capex in FY’25.
Meta: Capex was almost $8.5 billion in Q2, up more than 33% YoY and 26% QoQ. Meta’s first half capex totaled $15.2 billion, with management raising the lower-bound of their 2024 capex guidance range by $2 billion, from a prior view for $35 to $40 billion to $37 to $40 billion. This would imply ~37% YoY growth at midpoint for the full year, and indicate a significant acceleration in the back half, with more than $23 billion in capex projected at midpoint. Meta also expects “significant” capex growth in 2025 to support AI initiatives.
Alphabet: Capex totaled $13.2 billion in Q2, up 91% YoY and approximately 10% QoQ. Management said the surge in Q2 was “driven overwhelmingly by investment in our technical infrastructure with the largest component for servers followed by data centers.” For the year, management expects quarterly capex to be flat or above Q1’s $12 billion figure, implying capex of $50 billion or more.
Amazon: Capex was $16.5 billion in Q2, with Amazon the second-largest spender in the quarter after Microsoft. Amazon projected capex in the back half to be higher, suggesting 2024’s capex will come in well above $60 billion, with management saying the majority will go to support AWS infrastructure to meet high demand for both generative AI and non-generative AI services.
Big Tech’s capex is a barometer for the AI semiconductor industry, one that we closely track as we have a heavy allocation of stocks in this booming industry. Learn more about the I/O Fund’s holdings and consistent deep dive research on AI stocks, crypto and more here.
Analysts Pressing Big Tech Over ROI
Given this significant spending through 2023 and 2024, analysts are questioning whether monetization is going to match the level of investment, and grilled management teams over ROI timelines and AI capacity.
The management teams offered similar responses – which is that the predominant risk in AI is for those arrive late. Note, that it’s quite rare to have management teams from this many different companies agree (on anything really); and they are not only saying it in words, rather are showing us the seriousness of what is being stated in their budgets. Due to the sheer amount of capex, plus the unanimous agreement we are seeing across companies with $1T+ market cap on the importance of this capex, we are quoting the management teams directly.
Amazon:
Eric Sheridan (Analyst): “There’s been a theme during the last couple of weeks of earnings of the potential to over-invest as opposed to under-invest in AI as a broad theme. I’m curious, Andy, if you have a perspective on that in terms of thinking about elements of capitalizing on the theme longer term against the potential for pace or cadence of investment on AWS as a segment.”
Amazon CEO Andy Jassy: “We also are getting a lot of signals from customers on what they need. I think that it’s — the reality right now is that while we’re investing a significant amount in the AI space and in infrastructure, we would like to have more capacity than we already have today. I mean we have a lot of demand right now. And I think it’s going to be a very, very large business for us.”
Jassy also discussed the challenges in managing a business of AWS’ scale, and delivering too little or too much capacity, saying AWS understands the balance and how to manage capacity “reasonably well” to ensure AWS deploys the “right amount of capacity.”
Alphabet:
Ross Sandler (Analyst): “Just two questions on the AI CapEx. So it looks like from the outside at least, the hyperscaler industry is going from kind of an under bill situation this time last year to better meeting the demand with capacity right now to potentially being overbuilt next year if these CapEx growth rates keep up. So do you think that’s a fair characterization? And how are we thinking about the return on invested capital with this AI CapEx cycle.”
Alphabet CEO Sundar Pichai: “I think the one way I think about it is when we go through a curve like this, the risk of under-investing is dramatically greater than the risk of under-investing is dramatically greater than the risk of over-investing for us here, even in scenarios where if it turns out that we are over investing. … But I think not investing to be at the frontier, I think definitely has much more significant downside.”
Meta:
Brian Nowak (Analyst): “You have a lot of CapEx priorities from building new infrastructure for next-generation models, compute capacity. Just walk us through again on the CapEx philosophy and any guardrails you have around ensuring you generate a healthy return on invested capital for investors from all the CapEx.”
Meta CFO Susan Li: “On the ROI part of your question, I’d broadly characterize our AI investments into two buckets; core AI and Gen AI. And the two are really at different stages, as it relates to driving revenue for our businesses and our ability to measure returns. On our core AI work, we continue to take a very ROI based approach to our investment here. We are still seeing strong returns as improvements to both engagement and ad performance have translated into revenue gains and it makes sense for us to continue investing here.
Gen AI is where we are much earlier. … We don’t expect our Gen AI products to be a meaningful driver of revenue in 2024. But we do expect that they are going to open up new revenue opportunities over time that will enable us to generate a solid return off of our investment while we are also open sourcing subsequent generations of Llama. And we’ve talked about the four primary areas that we are focused here on the Gen AI opportunities to enhance the core ads business, to help us grow in business messaging, the opportunities around Meta AI, and the opportunities to grow core engagement over time.