
This article was originally published on Forbes on Aug 15, 2024, 05:09pm EDTForbes on Aug 15, 2024, 05:09pm EDT
Arm Holdings is the third-best performer of 2024 in AI-related semiconductor stocks with a 56% YTD return, behind only Nvidia and Taiwan Semiconductor. The stock is a market favorite as Arm’s heterogenous compute design has created a monopoly in mobile, primarily, yet Arm’s RISC architecture is also found in PCs, powers sensors and supercomputers. In total, over 280 billion Arm-based chips have been shipped dating back to the 1980s.
The latest Arm v9 architecture offers significant improvements in performance and efficiency, particularly for artificial intelligence (AI) applications. This has led to increased adoption by premium smartphone partners, and also with hyperscalers that are developing their own custom silicon for data center use.
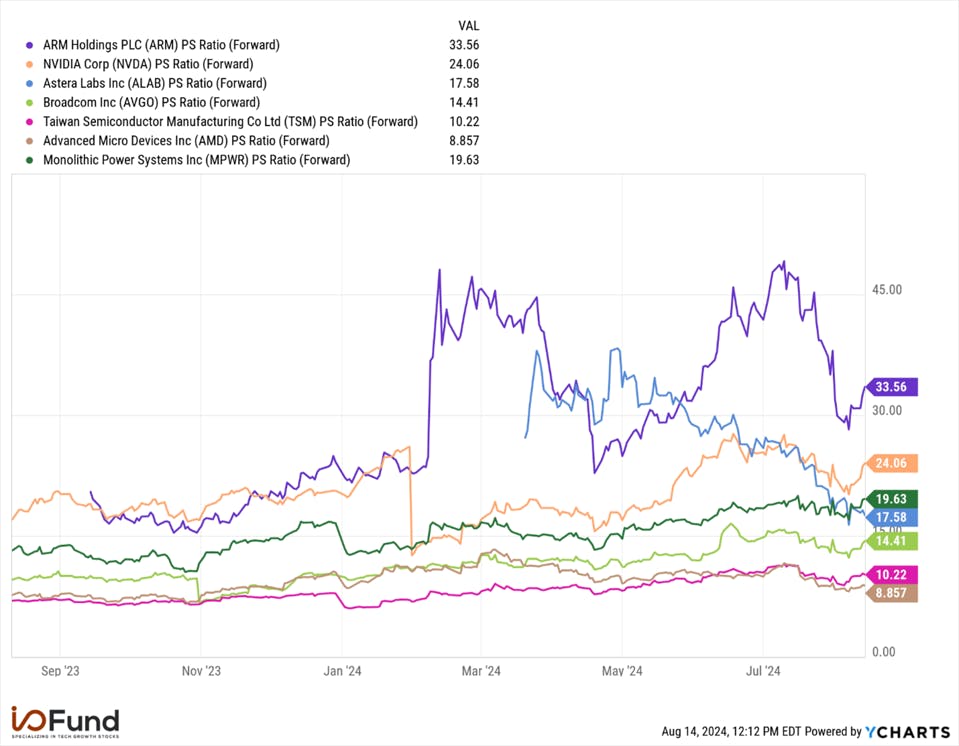
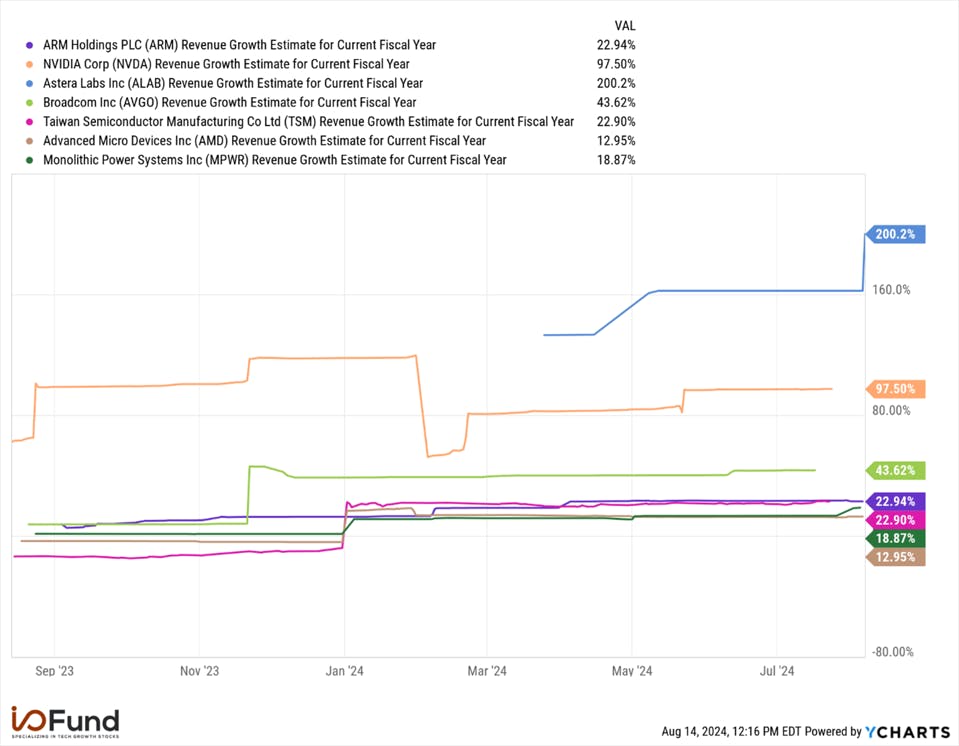
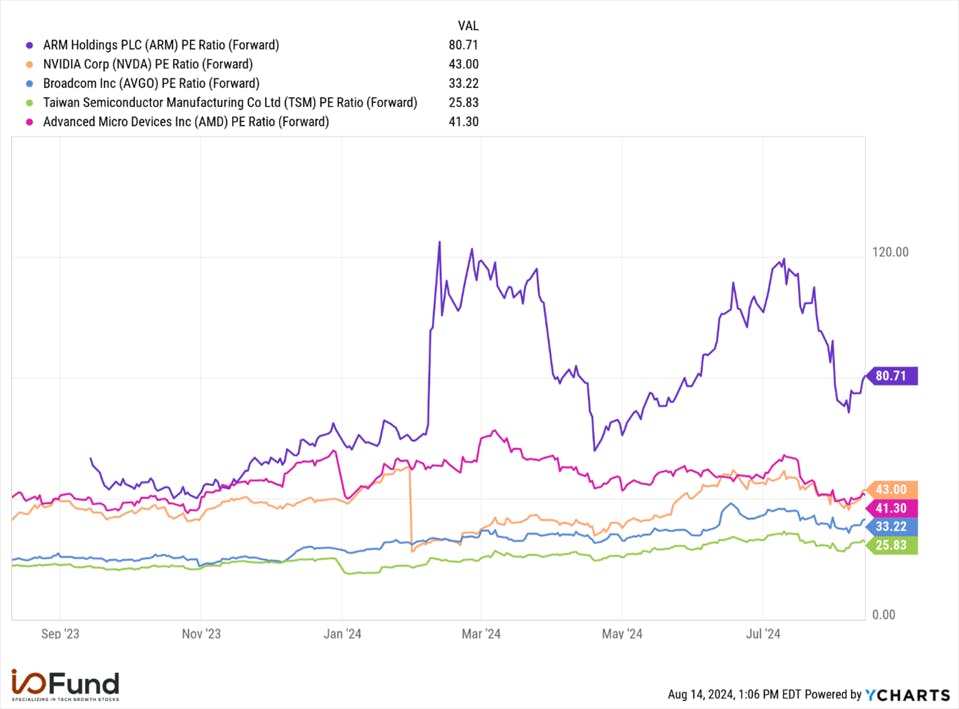
The market is excited about Arm’s v9 architecture because it commands double the royalty rate with Arm receiving a higher percentage of the chip’s selling price when a manufacturer uses v9 designs. The estimated royalty rates for v9 are around 4%, compared to Arm’s blended 1.7% royalty rates for the prior generations – however, this is simply not enough to consistently accelerate Arm’s top-line growth to justify its valuation as $70+ billion more AI chips are sold this year. So even though Arm is leveraging its established royalty and licensing model through its extensive ecosystem to drive predictable future growth and a rather defensible bottom line, apart from the cyclical doldrums of the semiconductor industry, its growth story pales in comparison to some of its key customers.
Q1 Earnings Strong, Yet Q2 and FY25 Failed to Impress
Given the string of strong beat and raises from GPU leader Nvidia over the past several quarters, the market has been setting the bar high for AI-related stocks, including Arm. Despite beating Q1 estimates, Arm failed to meet high expectations as it guided for Q2 results below consensus.
Arm reported 39% YoY growth to a record quarterly revenue of $939 million in Q1. Looking ahead to Q2, Arm projected revenue between $780 million and $830 million, for flat YoY growth at midpoint, decelerating from Q1’s 39% print. Analysts had expected Arm to guide to $813 million in revenue for Q2, for YoY growth of 1%. Given the small growth rate, a miss feels odd given the trajectory of other AI stocks.
In Q1, licensing revenue rising 72% YoY and 14% QoQ to $472 million, offsetting a more than (9%) QoQ decline in royalties. Arm said that licensing “hit a record level as the proliferation of AI everywhere is driving more companies to make broad and long-term commitments to use Arm’s power-efficient technology in their future products,” while royalty revenues are benefitting from Arm v9, which commands higher royalties per chip.
With that said, Arm expects next quarter “to be the low point of the year due to the timing of revenue recognition from licensing,” while also being one of the “highest bookings quarters of the year.” Royalty revenue is also expected to accelerate from 17% YoY to the low-20% YoY range in the quarter.
Arm’s adjusted EPS guide also came in below consensus estimates for the quarter, with Arm projecting $0.23 to $0.27 in EPS, short of the $0.28 estimate. While these may seem like thin margins for a miss, Arm’s premium valuation offers little room for error.
For FY25, Arm guided for revenue between $3.8 billion and $4.1 billion, or $3.95 billion at midpoint, falling short of the $4 billion consensus estimate. This forecast points to YoY growth of 18% to 27%. Adjusted EPS was guided between $1.45 to $1.65, which at the midpoint fell short of the consensus estimate for $1.57.
Arm also guided down for royalty revenue growth, projecting royalty revenue growth in the low 20% range, compared to the mid-20% range previously. Licensing revenue is expected to increase in the mid-20% range, with Q2 expected to be the weakest quarter and Q4 the strongest.
Our firm has been quite vocal that IPOs are not worth the risk, stating “there is no riskier proposition than an IPO that is richly valued.” The liquidity event that an IPO becomes after its lockup expiration creates high risk for tech investors as individual investors are often up against a deluge of insider selling. The fact that Arm is an overpriced IPO that is missing estimates this early is a concern. GAAP operating margin also has contracted from 18.5% to 5.4% on a TTM basis, primarily from IPO-related expenses.
Sign up for I/O Fund's free newsletter with gains of up to 2600% because of Nvidia's epic run - Click hereClick here
v9 Growth Decelerated Quickly, But Projected to Rebound
As a primary driver of royalty revenue growth, v9’s revenue is important to track as it commands double the royalty of v8, and features in “virtually all high-end data center chips” and a majority share in smartphones. For example, v9 underpins Nvidia’s Hopper series chips, Amazon’s Graviton chips, Microsoft’s Cobalt chips, and many more. Arm also sees v9’s increased adoption (and increase in royalty mix) and the ramp of CSS-based chips in the second half of the year as growth drivers.
In Q1, v9 accounted for 25% of net royalty revenue, up from 20% last quarter, and up from 15% two quarters ago. Smartphones contributed to 40% of royalty revenue in FY24 and was the first to adopt v9. Notably, the smartphone market is recovering right now — smartphone revenues grew 50% YoY despite a single digit increase in unit sales, demonstrating how increased adoption of v9 can quickly impact revenue growth.
However, on the backs of a QoQ decline in royalty revenue in Q1, v9 revenue growth has decelerated dramatically, despite increasing its mix share by 500 bp QoQ. Growth decelerated from 46% QoQ in Q4 to 14% QoQ in Q1, reaching $116.8 million.
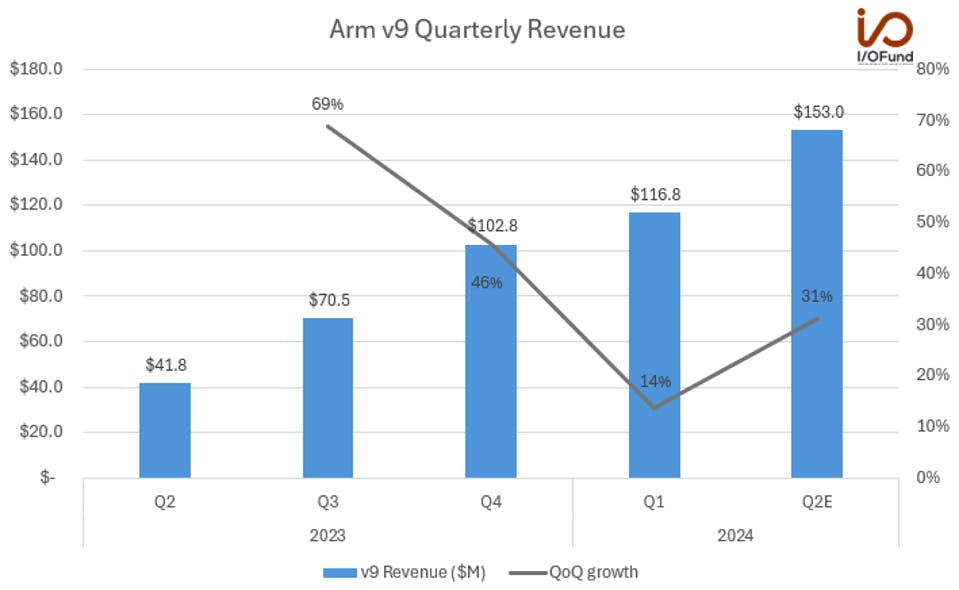
On the backs of a QoQ decline in royalty revenue in Q1, v9 revenue growth has decelerated dramatically, but is projected to rebound. Source: I/O Fund
v9 revenue growth is expected to reaccelerate to above 30% QoQ in Q2, and remain at that level in Q3 as royalty revenue returns to QoQ growth, with ~9% QoQ estimated for Q2 and ~12% QoQ for Q3. Management said it expects the 500 bp QoQ mix increase “to be the continued trajectory” moving forward, implying Q2’s mix at 30% and Q3’s at 35%. This V-shaped recovery in v9 revenues arises from this consistent increase in mix along with a return to QoQ growth around the 10% to low-teens range. As such, v9 royalties are projected to rise to ~$153 million next quarter, up 31% QoQ, a 17 percentage point acceleration.
Yet despite the reacceleration in v9 revenue growth, it still contributes only a fraction of the end-market value being added from chips built on the design. Meaning, while v9’s revenue is increasing by just $37 million QoQ, end market customers such as Nvidia are selling $2 billion more QoQ in GPUs built on v9. I’ve said this since 2021 – despite Arm’s designs powering 99% of the mobile market, or the most important AI GPUs available today, the revenue gains generated from its royalties are nowhere near the same ballpark as the growth and revenue generated by its customers.
x86 Will Make for Strong AI PC Competition
Arm dominates in the mobile market, with more than 99% market share, but in some of Arm’s smaller end markets, such as microprocessors, the company faces steeper competition from x86-based players AMD and Intel.
According to data from Mercury Research, in the microprocessor unit market, AMD gained 68 bp QoQ to 19.2% market share in Q2, while Intel gained 37 bp QoQ to reach 71.1% market share. Arm, on the other hand, saw a 105 bp QoQ decline in market share, dropping to 9.7% share.