
This article was originally published on Forbes on Aug 22, 2024,11:24pm EDT
Bulletproof Nvidia showed an unusual bout of weakness this past month following a report from The Information that Nvidia’s new AI chips are delayed. The report asserts that Nvidia’s upcoming artificial intelligence chips will be “delayed by three months or more due to design flaws,” resulting in a final flush of selling where the stock was down (-15%) in 7 days.
According to the report that was based on two anonymous sources, “if the upcoming AI chips, known as the B100, B200 and GB200, are delayed three months or more, it may prevent some customers from operating large clusters of the chips in their data centers in the first quarter of 2025, as they had planned.” This statement sent the market into a panic as it implies all three Blackwell SKUs will be delayed into the June quarter given the statement a three-month delay may prevent large clusters of Blackwell from not being operable in the first quarter.
It's strange then, to say the least, that according to two of Nvidia’s closest supply partners, there is evidence the GB200s will initially ship in Q4, and are expected to see an increase of production volume in Q1.
The third supplier provides a read-through that the fab producing the chips is not seeing any material impact. This is important as the The Information also asserts the machines fabricating Blackwell GPUs are sitting idle. Per the report: “it is highly unusual to uncover significant design flaws right before mass production. Chip designers typically work with chip makers like TSMC to conduct multiple production test runs and simulations to ensure the viability of the product and a smooth manufacturing process before taking large orders from customers. It’s also uncommon for TSMC, the world’s largest chipmaker, to halt its production lines and go back to the drawing board with a high-profile product that’s so close to mass production, according to two TSMC employees. TSMC has freed up machine capacity in anticipation of the mass production of GB200s but will have to let its machinery sit idle until the snags are fixed.”
The quote above implies the issues were entirely unforeseen, which might not be the case. My firm covers Nvidia’s management team statements quite closely since I first covered the AI thesis in 2018, and management has been quite clear that CoWoS-L packaging for Blackwell will require more time for testing than previous generations. I’ve dug up some of this commentary for you below.
Nvidia is delivering the history’s most aggressive product road map on new fab processes. This is a “move fast, break things” problem, which contrasted to strictly a design flaw, does not mean the architecture inherently has issues. Rather to contrast, the progression of this generation is testing the upper limits of manufacturing complexities. Blackwell with CoWoS-L packaging seeks to increase yields by circumventing a silicon monolithic interposer, and instead, will use an interposer with higher yields to help package the processing and memory components seamlessly together. The result will be to break ground on unprecedented performance gains for memory-intensive tasks.
These nuances matter for tech investors. Around this time, on August 2nd, my firm took the opportunity to buy our last Nvidia tranche at $105.73 in an effort to catch what we believe will be about 25% - 50% upside before price tops out.
We also look more closely at supply chain commentary, as there is one supply chain partner in particular that has reported a mysteriously high level of growth in a segment that is tied to Blackwell. We covered this for our premium members the evening of the supplier’s earnings report on August 6th when Nvidia stock was bottoming at $105.
As a reminder, we don’t make earnings calls, as many factors can affect stock price. Instead, we present quality research so that investors are fully informed to make their own decisions. From there, we take this a step further and publish every single trade we make on our research site. In finance, full transparency is rare, yet through never-ending tenacity, my firm has offered up to 3900% gains on Nvidia alone.
We continue this long-standing dedication to our readers in the analysis below.
Sign up for I/O Fund's free newsletter with gains of up to 2600% because of Nvidia's epic run - Click here
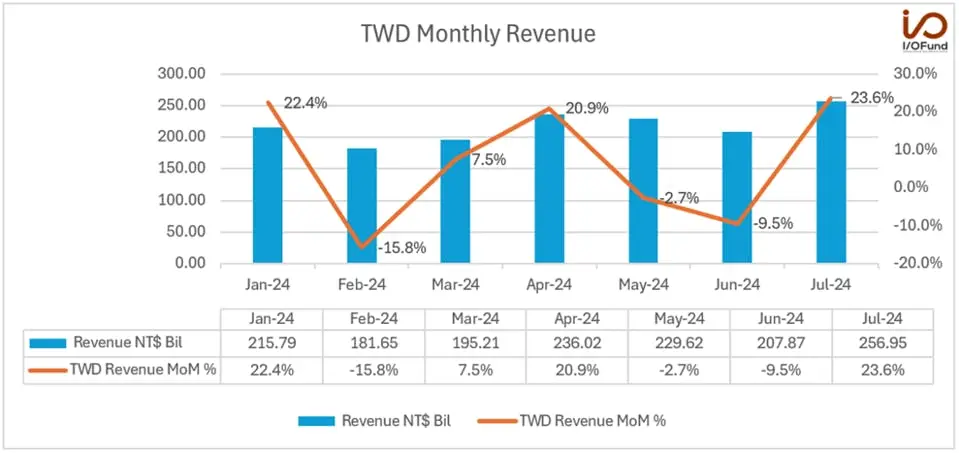
TSMC Reports 23.6% MoM Growth in July, Highest in 2024
TSMC releases monthly numbers which would reflect quickly if a highly anticipated release was causing idle machines. Instead, July monthly revenue showed a sharp acceleration from a decline in May and June to a MoM growth of 23.6% to NT$256.95 billion.
Source: I/O Fund
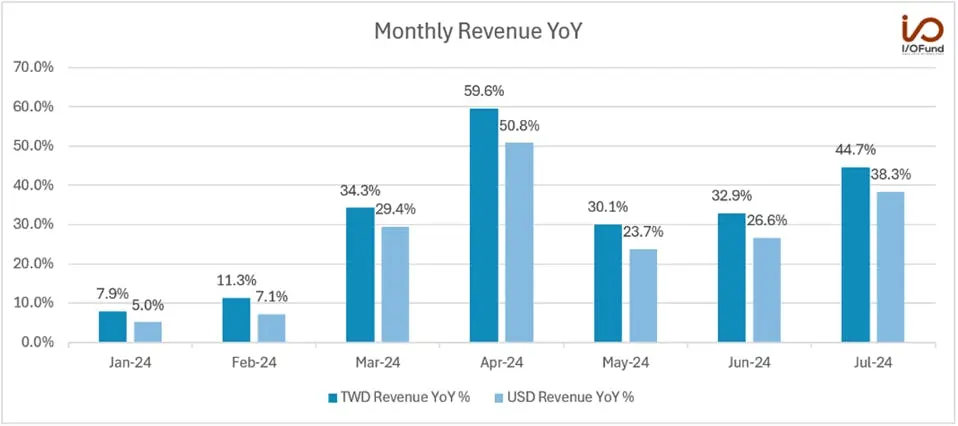
On a MoM/YoY basis, July reported the second largest growth this year:
Source: I/O Fund
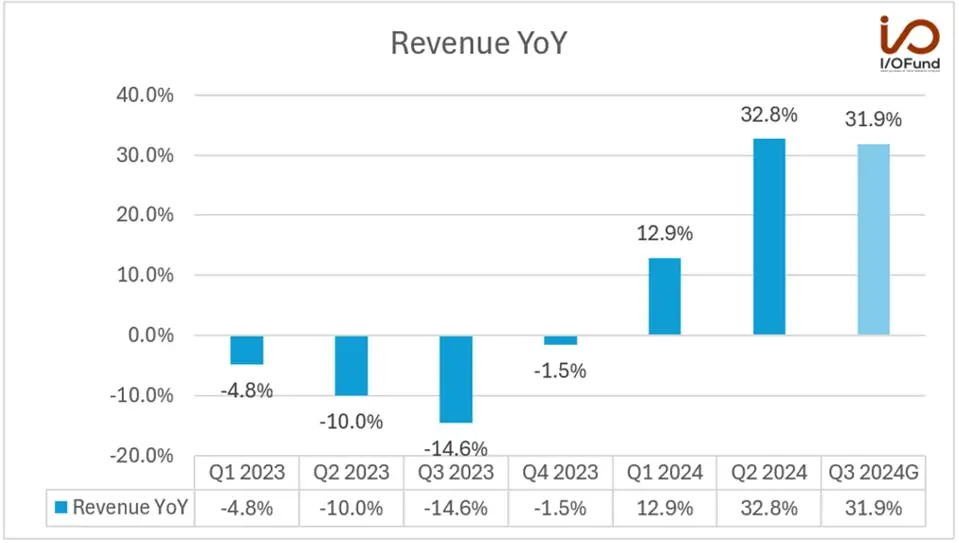
TSMC’s MoM growth can be lumpy, yet July month’s 38.3% YoY growth points to a positive start to the September quarter. The company guided for revenue of $22.4 billion to $23.2 billion, representing YoY growth of 31.9% at the midpoint.
Source: I/O Fund
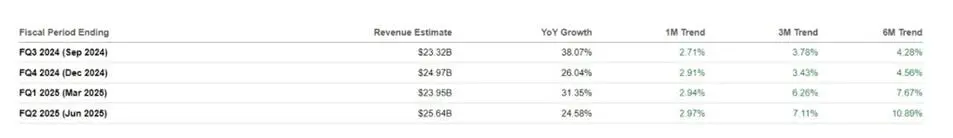
The analyst consensus estimates are trending higher, which typically, you’d see a decline in the analyst estimates on the news of a material delay. Analysts expect Q3 revenue to grow 38.1% YoY to $23.32 billion from the earlier 32.5% growth expected in mid-June and 32.1% growth expected in mid-May.
Note: The analyst estimates below differ slightly from reported figures in the company IR due to the currency conversion. However, we use the estimates below to understand the expected growth rate trend.
Source: Seeking Alpha
TSMC offered positive commentary on its business and raised the outlook when it reported its Q2 report last month. The company’s revenue grew by 32.8% YoY to $20.82 billion and beat the midpoint guide of 27.6% growth, helped by strong AI demand.
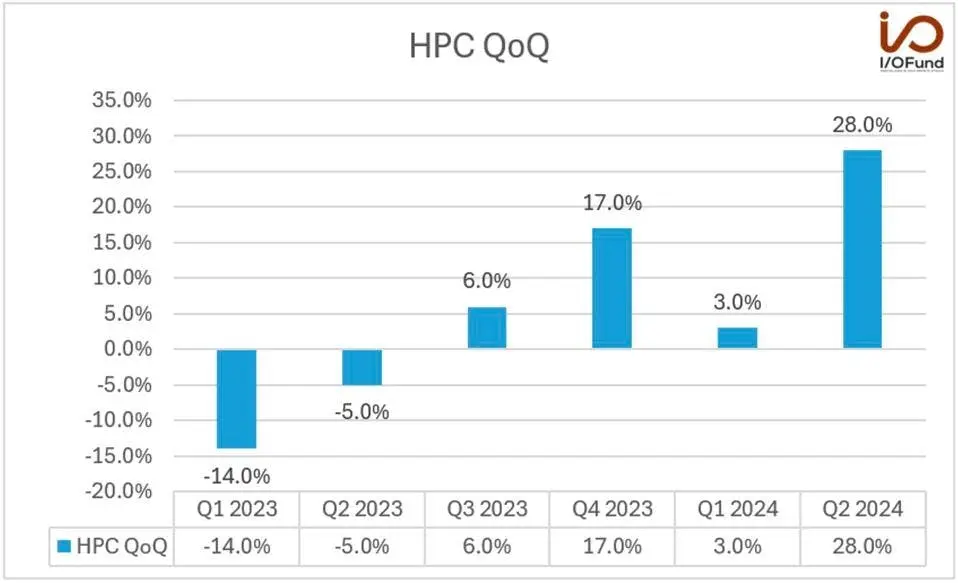
On a QoQ basis, the chipmaker’s high-performance computing (HPC) revenues rose 28% QoQ to $10.8 billion and accounted for 52% of Q2 revenue, up from 46% of revenue in Q1. HPC is above the 50% mark for the first time.
Source: I/O Fund
C.C. Wei, Chairman and CEO of the company, said in the Q2 earnings call, “Our business in the second quarter was supported by strong demand for our industry-leading 3-nanometer and 5-nanometer technologies, particularly offset by continuous smartphone seasonality.” There was a similar trend in Q1 as revenues were impacted by smartphone seasonality and offset by HPC revenue.
Wei also said that “over the past three months, we have observed strong AI and high-end smartphone related demand from our customers, as compared to three months ago, leading to increasing overall capacity utilization rate for our leading-edge 3-nanometer and 5-nanometer process technologies in the second half of 2024. Thus, we continue to expect 2024 to be a strong growth year for TSMC.”
They raised the full-year guidance to “slightly above mid-20s percent in US dollar terms” from the earlier “increase by low to mid-20% in U.S. dollar terms.” He further added, “we have such high forecasted demand from AI related business.” Given TSMC has many high-profile customers, the HPC segment alongside the CEO commentary help to differentiate the impact is coming from AI, rather than being mobile-related.
The I/O Fund built a leading AI portfolio beginning with Nvidia’s AI thesis in 2018, with up to 2,600% gains on Nvidia alone provided to our free readers. Premium members receive real-time trade alerts on NVDA and our entire portfolio, including two AI semiconductors we believe are poised for growth with allocations rivaling our NVDA holding.
TSMC’s Advanced Packaging
TSMC has limited CoWoS-L capacity to produce Blackwell chips. This is a problem all investors should get comfortable with as we head into 2025.
TSMC’s chip-on-wafer-on-substrate (CoWoS) architecture refers to the 3D stacking of memory and processors modules layer by layer to create chiplets. The architecture leverages through-silicon vias (TSVs) and micro-bumps for shorter interconnect length and reduced power consumption compared to 2D packaging.
There are three types of CoWoS architectures, which replaced multi-chip modules by scaling up the interposer area to fit multiple dies. Current CoWoS interposers are up to TSMC’s 3.3X reticle limit, with the goal of building interposers that can reach 8X the reticle limit by 2027. At the North American Technology Symposium earlier this year, TSMC stated they will reach 5.5X reticle limit by 2025 for more than a 3.5X increase in compute power.
As transistor density increases, advanced packaging solutions help to alleviate bottlenecks by increasing interconnect density, which results in higher signal speed and processing power.
- CoWoS-S: this is the most popular CoWoS architecture for GPUs already deployed, including Nvidia’s H100s, H200s and AMD’s MI300s. It uses silicon as the interposer material and is lower cost than CoWoS-R.
- CoWoS-R: connects chips with redistribution layers (RDL) wiring as the interposer material, offers InFO technology as an upgrade for HBM memory and SoC integration.
- InFO technology reduces the size of components in more powerful devices. By being Fan-Out (FO) instead of Fan-In, TSMC’s process can integrate multiple dies on top of each other with a common I/O connecting layer.
- CoWoS-L: combines multiple Si interconnects (LSI) for a reconstituted interposer (RI) that replaces the monolithic silicon interposer in CoWoS-S. By taking the benefits of CoWoS-S, CoWoS-L offers strong system performance while avoiding the yield loss from one Si interposer.
Nvidia designs offer pure ingenuity, for example, the A100s offered sparsity and the H100s offered a transformer engine. We covered the importance of the Transformer Engine for our premium site six months prior to Hopper shipping, which led to entries as low as $10.85 when factoring in the stock split. Ultimately, Nvidia’s design ingenuity combined with TSMC’s process improvements defy Moore’s Law.
Due to TSMC’s CoWoS-L requiring more complexity and precision, it was already expected the validation and testing process would be time consuming. We had stated in the analysis Nvidia Q1 Earnings Preview: Blackwell and The $200B Data Center that “the advanced CoWoS packaging that is needed to combine logic system-on-chip (SoC) with high bandwidth will take longer, and thus, it’s expected that Blackwell will be able to fully ship by Q4 this year or Q1 next year. How management guides for this will be up to them, but commentary should be fairly informative by Q3 time frame.”
Per another source, Trend Force last April: “Although NVIDIA plans to launch products such as the GB200 and B100 in the second half of this year, upstream wafer packaging will need to adopt more complex and high-precision CoWoS-L technology, making the validation and testing process time-consuming. Additionally, more time will be required to optimize the B-series for AI server systems in aspects such as network communication and cooling performance. It is anticipated that the GB200 and B100 products will not see significant production volumes until 4Q24 or 1Q25.”
From the horse’s mouth, Nvidia’s own management team, it was stated during the GTC Financial Analyst Day in March that the very first systems will ship in Q4, but to expect constraints. In a roundabout way, the CEO tells investors what to expect should this happen, which is that customers will continue to build with H100s, H200s and any other supply they can get their hands on.
Atif Malik, Citigroup:
Hi. I am Atif Malik from Citigroup. I have a question for Colette. Colette in your slides, you talked about availability for the Blackwell platform later this year. Can you be more specific? Is that the October quarter or the January quarter? And then on the supply chain, readiness for the new products is the packaging, particularly on the B200 CoWoS-L and how you are getting your supply chain ready for the new products?
Colette Kress:
Yeah, so let me let me start with your second part of the question, talking about the supply-chain readiness. That's something that we've been working well over a year getting ready for these new products coming to market. We feel so privileged to have the partners that work with us in developing out our supply chain. We've continued to work on resiliency and redundancy. But also, you're right, moving into new areas, new areas of CoWoS, new areas of memory, and just a sheer volume of components and complexity of what we're building. So that's well on its way and will be here for when we are ready to launch our products. So there is also a part of our supply chain as we talked earlier today, talking about the partners that will help us with the liquid cooling and the additional partners that will be ready in terms of building out the full of the data center. So this work is a very important part to ease the planning and the processing to put in all of our Blackwell different configurations. Going back to your first part of the question, which is when do we think we're going to come to market? Later this year, late this year, you will start to see our products come to market. Many of our customers that we have already spoken with talked about the designs, talked about the specs, have provided us their demand desires. And that has been very helpful for us to begin our supply chain work, to begin our volumes and what we're going to do. It's very true though that on the onset of the very first one coming to market, there might be constraints until we can meet some of the demand that's put in front of us. Hope that answers the question.
Jensen Huang:
Yeah, That's right. And just remember that Hopper and Blackwell, they're used for people's operations and people need to operate today. And the demand is so great for Hoppers. They — most of our customers have known about Blackwell now for some time, just so you know. Okay, so they've known about Blackwell. They've known about the schedule. They've known about the capabilities for some time. As soon as possible, we try to let people know so they can plan their data centers and notice the Hopper demand doesn't change. And the reason for that is they have an operations they have to serve. They have customers today and they have to run the business today, not next year.
—End Quote
Recently, Nvidia’s VP Ian Buck stated at BofA Financial Conf in June 2024; “So we stated recently in our earnings that Blackwell has now entered into production builds. We started our production.
The samples are now going — will go out this quarter, and we're ramping for production outs later this year. And then everything — that always looks like a hockey stick, you start small and you go pretty quick to the right. And the challenge, of course, is with every new technology transition comes — the value is so high, there's always a mix of a challenge of supply and demand. We experienced that certainly with Hopper. And there'll be similar kinds of supply/demand constraints in the on-ramp of Blackwell certainly at the end of this year and going into next year.”
Taking this full circle, let’s go back to what TSMC said in the most recent earnings call about CoWoS capacity:
Management stated in the earnings call Q&A that the supply is expected to continue to be tight next year, and they are working with OSAT (Outsourced Semiconductor Assembly and Test) partners to increase production capacity.
Gokul Hariharan:
“How do you think about supply demand balance for AI accelerator and CoWoS advanced packaging capacity? And I think in your symposium you talked about 60% CAGR, component growth for CoWoS capacity in the next four, five years. So, could you talk a little bit about how much capacity for CoWoS would you be planning to build next year as well?”
C. C. Wei:
“Gokul, I also try to reach the supply and demand balance, but I cannot today. The demand is so high, I have to work very hard to meet my customers' demand. We continue to increase, I hope sometime in 2025 or 2026 I can reach the balance. You're talking about the CAGR or those kind of increase of the CoWoS capacity. Now it's out of my mind. We continue to increase whatever, wherever, whenever I can. Okay. The supply continues to be very tight, all the way through probably 2025 and I hope it can be eased in 2026. That's today's situation.”
Gokul Hariharan:
“Any thoughts on next year capacity? Are you going to double your capacity again next year for CoWoS?”
C. C. Wei:
“The last time I said that, this year I doubled it, right? More than double. Okay. So next year, if I say double, probably I will answer your question again next year and say more than double. We are working very hard, as I said. Wherever we can, whenever we can.”
—End Quote
My notes: There were many opportunities for TSMC to report a material impact from idle machines – quarterly numbers ending in June, July monthly numbers, commentary during the earnings call from the CEO that establishes the opposite, which is that capacity is primarily the issue (rather than a dire flaw that is halting production) and the company is working hard to increase this capacity.
Earlier this month, TrendForce citing Money DJ’s report, estimated that CoWoS capacity is in short supply at 35,000 to 40,000 wafers this year. With outsourced capacity, 2025 production could be over 65,000 wafers per month.
According to the report, TSMC will assign the orders of the initial stage of CoWoS packaging, Chip on Wafer (CoW) to OSAT partner SPIL. This is the first time the company is outsourcing this process since the demand is high and previously WoS (Wafer-on-Subtrate) process was outsourced while keeping the higher margin CoW process in-house.
According to DigiTimes, the company is expected to have CoWoS production of 60,000 wafers per month in 2025 and a further increase to 70,000 to 80,000 in 2026 after the company recently acquired Innolux Fab. The 2025 production capacity would suggest a 300% increase from 15,000 at the end of 2023.
Every Thursday at 4:30 pm Eastern, the I/O Fund team holds a webinar for premium members to discuss how to navigate the broad market, as well as various stock entries and exits. We offer trade alerts plus an automated hedging signal. The I/O Fund team is one of the only audited portfolios available to individual investors. Learn more here.