
IBM released upbeat results recently as the company beat consensus analysts’ revenue estimates by $740 million and adjusted EPS by $0.06. Even though IBM is not a pure-play cloud company, it has increased its focus in the cloud segment to stay in the race. IBM’s cloud revenues increased 16% YoY in Q4 and the results brought some relief to the investors after the recent volatility in the stock market.
On the other hand, Microsoft beat analysts’ revenue estimates by 1.9% and adjusted EPS by 6.9%. Microsoft Cloud revenue grew 32% to $22.1 billion. This is a positive sign for the broader cloud market. The company’s capex has also been strong, suggesting that management believes demand is structural.
Our Cloud companies’ earnings preview includes Dynatrace, Unity Software, JFrog, DigitalOcean, UiPath, Palantir, and BigCommerce. To understand valuations across the cloud companies and how the sector is positioned moving into earnings, please reference our analysis, “I/O Fund’s Cloud Q4 2021 Earnings Overview.”
Dynatrace Inc – Earnings on February 02nd
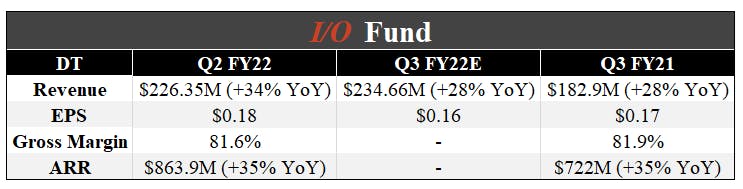
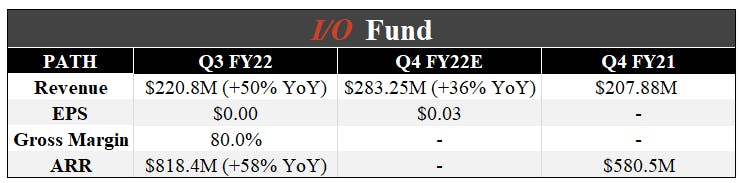
ARR: Annualized Recurring Revenue
Source: YCharts, Earnings Reports, and I/O FundYCharts, Earnings Reports, and I/O Fund
The company’s revenue in Q2 FY22 grew 34% YoY to $226.35 million. According to the analysts’ consensus estimates, revenue is expected to grow 28% YoY to $234.6 million in the next quarter. The management has been positive on the long-term growth prospects due to the digital transformation across industries. In the last earnings call, they mentioned that the near-term market expansion opportunities include the U.S. government's investments in cloud platforms.
Barclays analyst Raimo Lenschow has lowered the price target to $65 from $85. He has an Overweight rating. According to the analyst, the main question for software investors in 2022 is not around end demand, as there are "no issues there," but the correct valuation level for the space. "Are we going back to the long-term average, or should software bounce back to the more recent highs given the exciting structural growth profile? We are in the former camp,” says the analyst as he gets a bit cautious on the sector.
Jefferies analyst Brent Thill also lowered the price target to $60 from $75 and has kept the hold rating. He adjusted his targets across the app, infrastructure and security software spaces. “Software underperformed the S&P 500 by 15% in 2021 as overall valuations contracted 10%,” according to Thill, who thinks multiples in the space will continue to compress in 2022 as 80% of software names are expected to decelerate with "digital digestion" happening coming out of the pandemic.
Please note that the I/O Fund may or may not agree with the above financial analysts, yet we objectively report what the Street is saying. You may view our previous analysis of the company below:
3 Different Ways Companies Can Game Their Topline Growth Rates
Podcast with Motley Fool: I’m Bullish on These Trends for 2021
Unity Software Inc – Earnings on February 03rd
Source: YCharts, Earnings Reports, and I/O FundYCharts, Earnings Reports, and I/O Fund
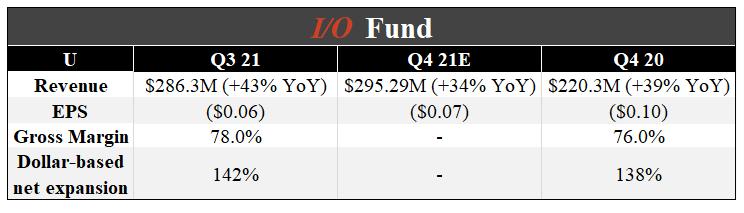
Unity’s revenue grew by 43% YoY in Q3 and is expected to grow 34% to $295.29M in the next quarter. The company recently completed the acquisition of Weta Digital. Weta is a digital visual effects company known for its work in Lord of the Rings, Avatar, and Wonder Woman. The management believes that the company’s addressable market will increase by about $10 billion from the acquisition.
Piper Sandler analyst Brent Bracelin made an interesting point that the company is an indirect beneficiary of Activision and the Microsoft deal due to its unique position as the leading 3D creator platform for gaming, movies, AR/VR, and metaverse applications. The analyst also believes that Unity can expand its footprint as a 3D creator platform in the coming year.
Stifel analyst J. Parker Lane has initiated coverage of the company with a buy rating and a price target of $190. According to the analyst, “Unity's broad set of solutions has made the company a market leader in the gaming industry and positioned its platform to address emerging use cases in other industry verticals.” Lane further adds, “Additionally, the company's continued investment in research and development, tuck-in acquisitions, and presence in gaming has helped it withstand the headwinds of IDFA and gain market share in a competitive advertising market.”
Read our previous article on the company below:
JFrog Ltd – Earnings on February 10th
Source: YCharts, Earnings Reports, and I/O FundYCharts, Earnings Reports, and I/O Fund
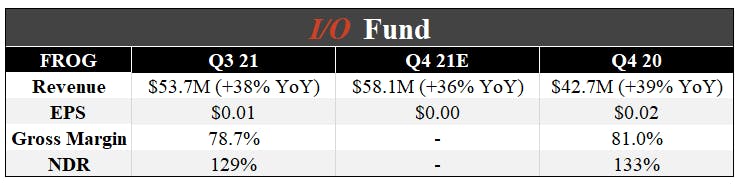
The company’s revenue grew by 38% YoY in Q3 and the consensus analysts’ estimates suggest revenue to grow 36% to $58.1 million in the next quarter. The management expects revenue in the range of $57.5 million to $58.5 million and adjusted earnings per share of break-even to $0.01. For the full year, management expects revenue in the range of $205 million to $206 million, representing a growth of 36% YoY at the mid-point.
Stifel analyst Brad Reback has a buy rating and a $45 price target. He sees the company is well positioned to sustain 30%-plus revenue growth as it leverages its "unique position within the DevSecOps workflow.” He further believes that JFrog has a growing suite of solutions to help customers build, manage, distribute, and secure their respective applications more effectively and efficiently. Sign up for I/O Fund's free newsletter with gains of up to 1100% - Click hereSign up for I/O Fund's free newsletter with gains of up to 1100% - Click hereClick here
Needham analyst Jack Andrews has a buy rating and a $71 price target. The analyst is positive on its leverage to strong macro demand trends for DevOps tools and practices, expects its key financial metrics to inflect higher. He further believes that the company is trading at a discount to the broader software companies creating a favorable risk/reward. At the time of the writing, the company was trading at 6.0x EV/Fwd revenue multiple.
Read our previous article on the company below:
Tech Growth Earnings Review for Q3 2020 - Part 2
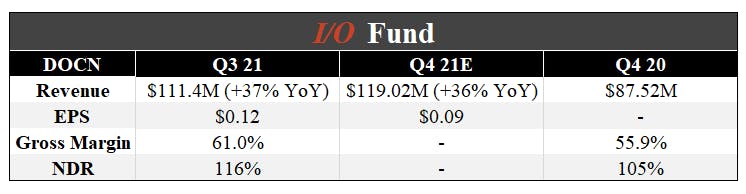
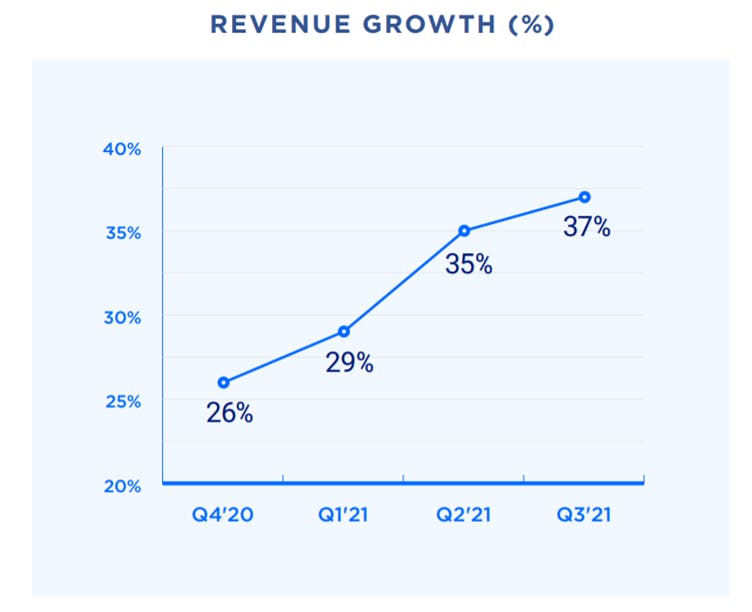
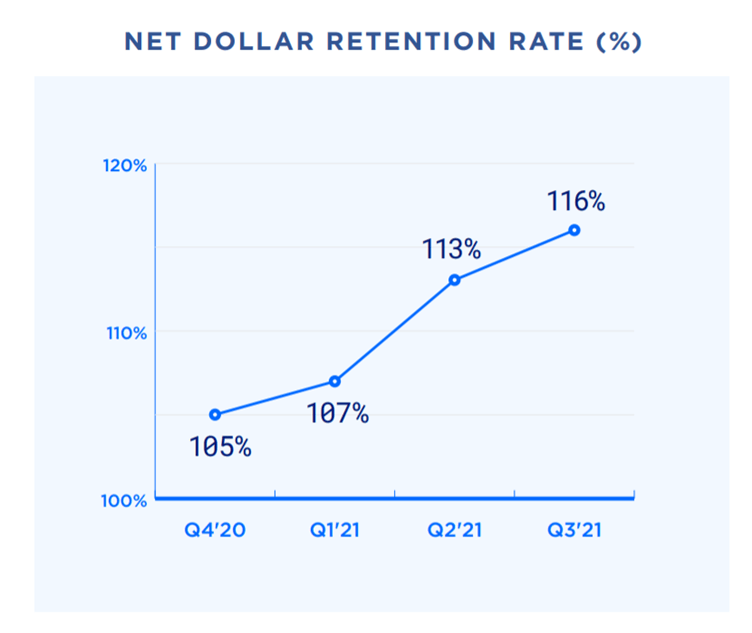
DigitalOcean Inc - Tentative Earnings date is February 15th