
This article was originally published on Forbes on Mar 23, 2023,09:56pm EDTForbes Forbes on Mar 23, 2023,09:56pm EDT
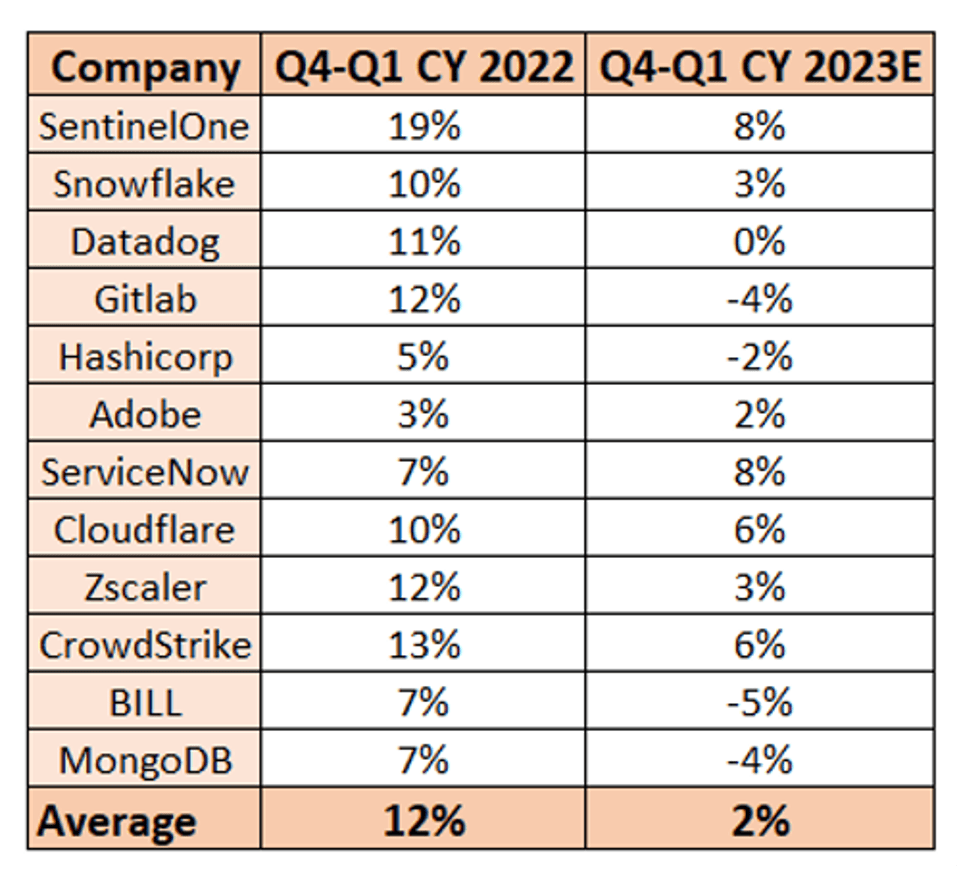
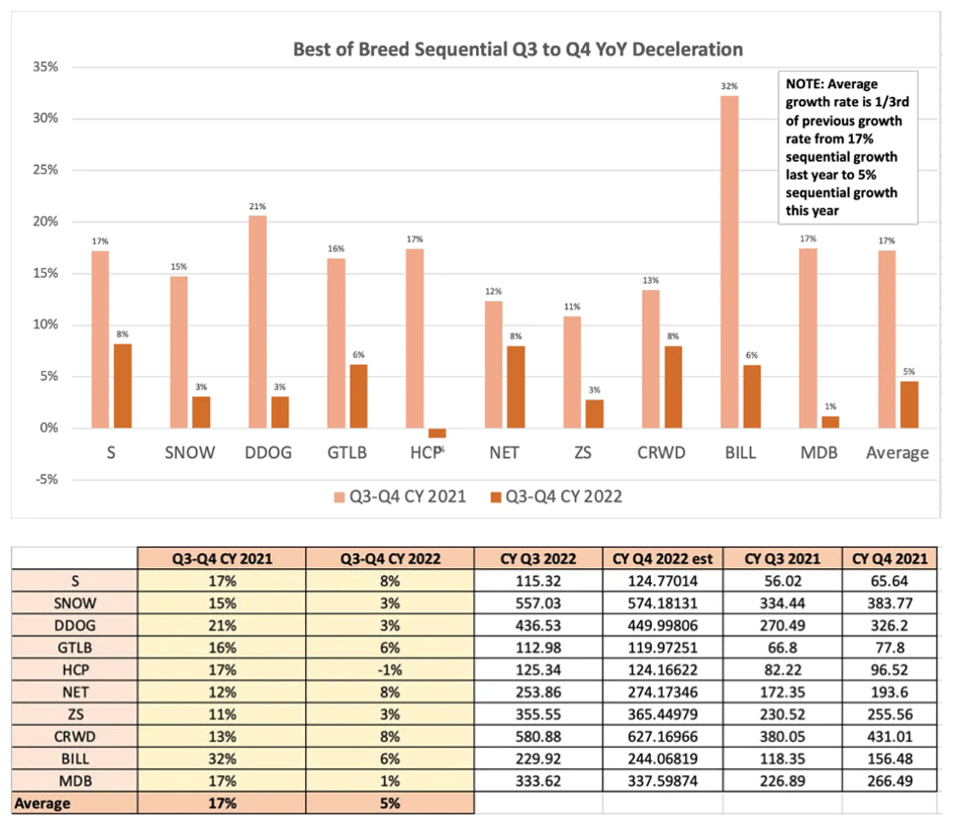
Following last quarter’s earnings, we published an analysis on cloud that showed hyperscalers were slowing (5%) sequentially and best-of-breed was slowing (12%) sequentially, based on Q4 guides.
What was most important for tech investors to realize, is that this is out of character for cloud, as Q4 is typically the strongest quarter. We concluded that this foreshadows a weaker-than-expected Q1 and also a weaker FY2023 than was currently baked into estimates.
Following the most recent earnings reports, our prediction is playing out that the slowdown we had predicted would worsen after the current quarter results.
This is important because the cloud category has treated investors quite well with recurring revenue, resiliency during Covid, and some of the strongest examples of product-market fit available on the public markets. However, not even this can overcome the effects of lower budgets and cloud spend, which is the top driver in terms of year-over-year comparisons.
Below, we discuss the fundamental weakness apparent in the most recent earnings reports. For our Premium Research Members, we are extending the analysis next week to include a few outliers that seem more resilient than others in the category, and those that are definitively the weakest.
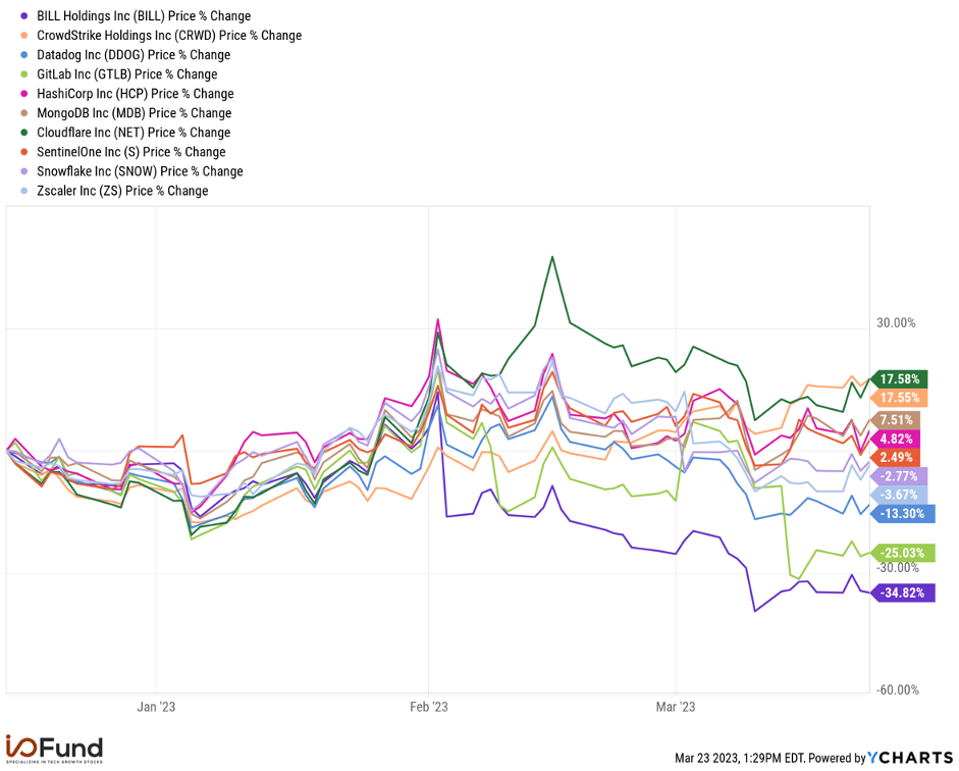
Often times, identifying one or two strong companies in a category and patiently waiting can pay off, as the cloud category will put downward pressure on the stock price, including the outliers. Our goal is to buy the outlier(s) after they’ve been unduly penalized.
Sign up for I/O Fund's free newsletter with gains of up to 221% - Click hereSign up for I/O Fund's free newsletter with gains of up to 221% - Click hereClick here
Big Tech: Bellwethers for Cloud Spend
Big Tech competes with best-of-breed cloud companies in nearly every capacity. For example, although most think of Azure when looking at Microsoft’s earnings reports, the company has a formidable presence in cybersecurity worth over $20 billion in revenue. Google’s BigQuery is one of Snowflake’s largest competitors, as is Amazon’s RedShift. I covered the differences between the three for Forbes here.
We also made the following point about why the Big 3 is an important proxy in our analysis: “Slowing Growth in Cloud Stocks: When Will We Hit a Bottom”
“The Big 3 are the best proxy because their reports represent the layer in the tech stack that tends to be the most resilient in terms of churn. The switching costs are quite high for cloud IaaS services. The Big 3 also afford a more concentrated view by owning 66% of market share across three companies whereas SaaS is spread across thousands of companies.”
The slowdown over the past four quarters is quite visible:
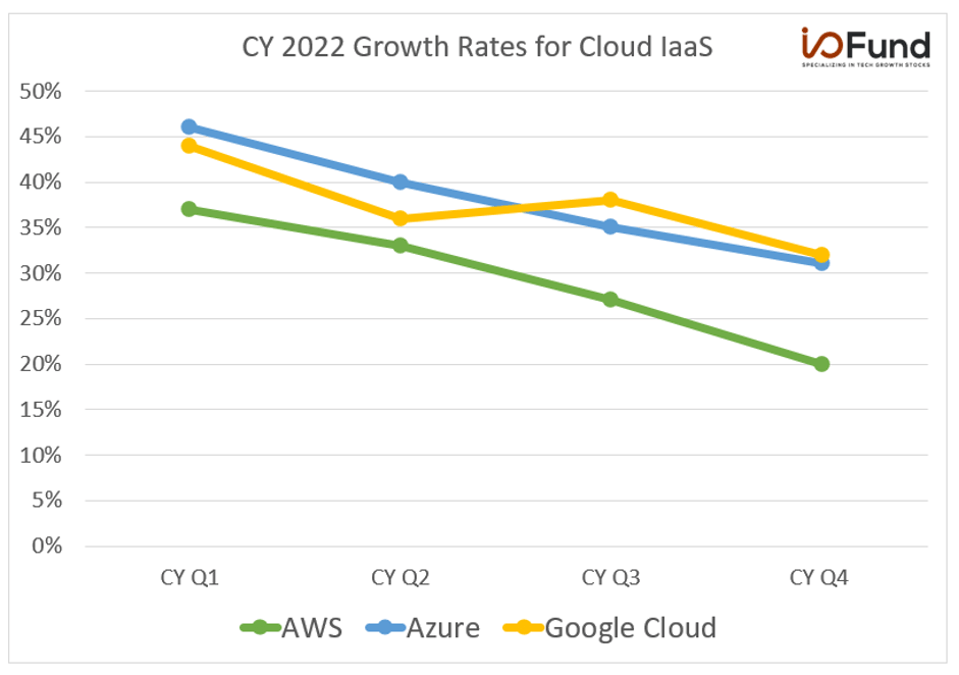
The Cloud slowdown over the past four quarters is quite visible - I/O FUND
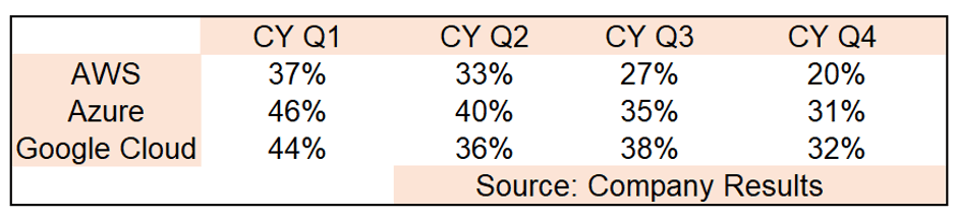
The Cloud slowdown over the past four quarters - COMPANY RESULTS
Key Highlights from the Cloud Hyperscalers:
AWS:
- AWS sales grew by 20% YoY to $21.4 billion in Q4, down from 27% YoY growth reported in Q3 and down from 33% YoY reported in Q2
- Q4 2022 growth rate of 20% was halved as AWS sales grew by 40% YoY in Q4 2021
- AWS revenue also missed the management guidance of 25% growth
- Guidance for Q1 was not provided, however, it was stated the YoY growth rates in January were “in the mid-teens”
Azure:
- Microsoft Azure revenue grew by 31% YoY and was down from 35% in Q3. In constant currency, it grew 38% and beat the management guidance by 1%.
- Microsoft Azure revenue grew by 46% YoY and also in CC basis in Q4 2021.
- The management provided guidance of 30% to 31% growth rate for the March quarter, down from 38% this quarter and down from 49% on a CC basis in the year ago March quarter.
- You may recall the 5-point deceleration announced in the October report caused concern in the market. This is technically a steeper deceleration.
GCP:
- Google Cloud revenue grew by 32% YoY to $7.3 billion and was down from 38% growth in Q3. Revenue missed the analyst consensus estimates by 1.5%.
- The growth rate was also significantly lower than last year’s growth (down about 1/3rd) when Google Cloud revenue grew by 45% YoY in Q4 2021.
What Big 3 Management Teams are Saying
When there’s evidence of a deceleration, analysts will typically ask the management teams to elaborate on the call with the idea of identifying how much more deceleration may be reported in the future and for how long.
Here’s a question regarding AWS’s slowdown:
Mark Mahaney
[…] Brian, just any color on why mid-teens is kind of a holdable growth rate for AWS over the next couple of quarters, given what looks like pretty clearly, continuing deterioration in enterprise demand?
Brian Olsavsky (CFO)
So on the AWS growth rate, I'm not sure I can forecast for you with any level of certainty what is going to happen beyond this quarter. You kind of — this is a bit uncharted territories economically. And as we mentioned, there's some unique things going on with the customer base that I think many in this industry are all seeing the same thing.
[..] And whether there's short term, perhaps short-term belt tightening in the infrastructure expense by a lot of companies, I think the long-term trends are still there. And I think the quickest way to save money is to get to the cloud, quite frankly.”
Amazon’s management also volunteered the following in their opening remarks:
“Starting back in the middle of the third quarter of 2022, we saw our year-over-year growth rates slow as enterprises of all sizes evaluated ways to optimize their cloud spending in response to the tough macroeconomic conditions. As expected, these optimization efforts continued into the fourth quarter.”
They expect the optimization efforts to continue at least for the next couple of quarters and, in the absence of proper guidance for Q1, said that the YoY growth rates in January were in the mid-teens.”
Per management: “As we look ahead, we expect these optimization efforts will continue to be a headwind to AWS growth in at least the next couple of quarters. So far in the first month of the year, AWS year-over-year revenue growth is in the mid-teens.”
Here’s what Microsoft’s CEO, Satya Nadella, said in the first part of his opening comments:
“As I meet with customers and partners, a few things are increasingly clear. Just as we saw customers accelerate their digital spend during the pandemic, we are now seeing them optimize that spend. Also, organizations are exercising caution given the macroeconomic uncertainty.”
Later in the call the CFO mentions, “As noted earlier, growth continued to moderate, particularly in December, and we exited the quarter with Azure constant currency growth in the mid-30s.”
The I/O Fund has launched a new $99/year Premium Newsletter called "Essentials" -- this newsletter delivers premium samples for our readers who want more actionable analysis for their tech portfolios. This month, we released a stock pick that we believe will be a leader in 2023 plus a video with the buy plan.$99/year Premium Newsletter$99/year Premium Newsletter called "Essentials" -- this newsletter delivers premium samples for our readers who want more actionable analysis for their tech portfolios. This month, we released a stock pick that we believe will be a leader in 2023 plus a video with the buy planbuy plan.