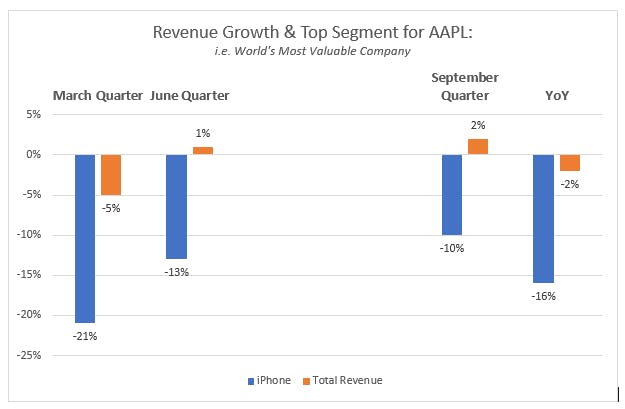

I grew critical of Apple earlier this year when it became clear the company would decline in revenue year-over-year, yet investors and analysts alike continued to pump the stock. With yesterday’s earnings report, we have further confirmation that Apple is not a growth company anymore although it continues to trade at growth valuations.
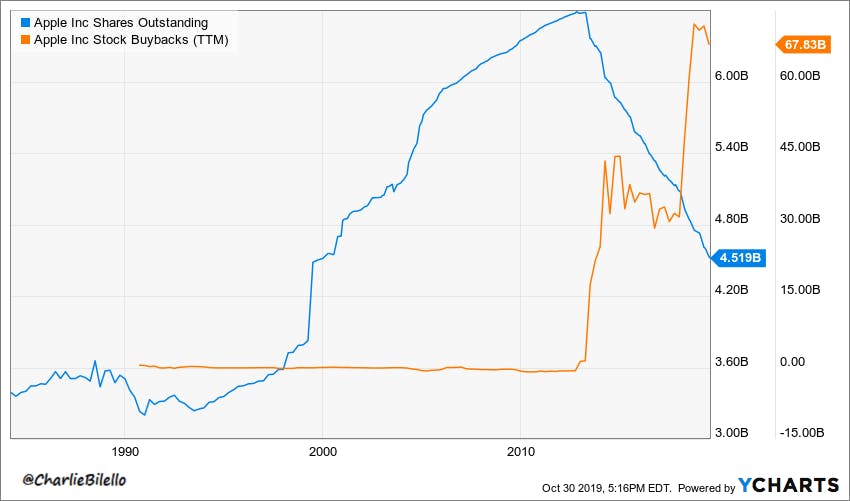
While many celebrated yesterday’s earnings report, there were notable signs of erosion. To start, Apple has lost $5 billion in revenue year-over-year, from $265 billion to $260 billion. This is despite having the “best fourth quarter ever,” according to Tim Cook. The truth is that the EPS was higher due to buybacks.
My analysis in MarketWatch published prior to earnings, pointed out that the iPhone was exposed to macro smartphone saturation. Those numbers showed a deeper decline than overall revenue with a $22 billion decline reported year-over-year.
Although Apple has ceased reporting smartphone unit sales, the numbers reveal there are fewer smartphone units being sold. Moving forward, with the recent release of the iPhone, Apple will contend with a lower average sales price. This is bound to affect smartphone device revenue moving forward, which declined at a rate of 15% year-over-year.
Overview of Mobile Saturation:
The smartphone market contracted to 1.462 billion units in 2017 and to 1.420 billion units last year. While almost 1.5 billion smartphones sales a year globally is substantial, the law of saturation drives down prices. I wrote about the price effects of mobile saturation in March, prior to Apple lowering prices for the first time with the iPhone 11.
China represents about one-third of smartphone penetration compared with the U.S., at one-12th. Pricing wars are evident in Asia, where China’s Huawei has grabbed market share to become the world’s fastest-growing smartphone seller. The company has seen a 66-fold increase from 3 million units sold in 2010.
Samsung may be the true bellwether for mobile, as the company is in first position for total smartphones shipped and is the world’s largest manufacturer of memory chips. In the first quarter, the company reported a 60% drop in operating profits, followed by a 56% decline in the second quarter. Analysts expect another decrease in the third quarter. Smartphone units have been making lower highs and lower lows over the past two years.
Samsung’s disappointing performance hints at the ties between smartphone sales and consumer confidence as China’s confidence index is languishing at a two-year low.
Notably, IDC forecasts the pricing wars will continue with 5G handsets in Asia, as low-cost models are expected to hit the market next year. In the U.S., Latin America and Japan, the average selling price (ASP) of a 5G handset will be around $1,000, while it will be $600 in China.
Don’t Believe the Earnings Beat:
The fiscal Q4 earnings beat is at odds with overall performance. Although profit topped expectations, this is the first time since Tim Cook took over in 2011 that Apple declined in profit in all four quarters of a fiscal year.
The media touts the services revenue as the answer to the iPhone decline. As we saw this year, double digit declines on the segment responsible for $165 billion in revenue (iPhone) is not easily staved off by a revenue segment posting $40 billion per year (services).
If one did not look closer at the numbers, it would easy to think services was a major growth segment. We see the growth was at 18%, which is below the 20% traditional benchmark that defines growth. As of now, this doesn’t appear to be the answer to the gaping iPhone decline. This is proven by the annual decline in overall revenue.
Wearables growth of 55% to $24 billion in revenue is decent. However, again, the iPhone decline was steep enough at $22 billion to wipe out the entire Wearables category.
I had pointed out in a Fox Business News interview prior to earnings that its unlikely lightning strikes twice with the iPhone as it’s not only one of Apple’s best growth drivers historically, but it’s also one of the best growth drivers we’ve seen across the tech industry. This is evident in last year’s smartphone revenue of $165 billion, which I also pointed out will be Apple’s peak year in mobile.
https://www.youtube.com/watch?v=ClLBzohNeE0
Note: although I provide an entry price for Apple on Fox Business News, this is something Knox Ridley specializes in and covers as a contributing analyst to our premium site Tech Insider Research. You can catch his detailed technical analysis published on Seeking Alpha next week.Knox Ridley specializes in and covers as a contributing analyst to our premium site Tech Insider Research. You can catch his detailed technical analysis published on Seeking Alpha next week.