Financial Analysis

Verified Returns & Risk Management: A Retail Investor’s Imperative

Written by

I/O Fund Team

Research Team

Published: March 27, 2024

Last Updated: March 27, 2024

Last year was a stellar year for investors – in 2023, the Nasdaq 100 rose 54% for its best annual return since 1999, while the S&P 500 gained 24%. The Magnificent 7 were the de facto leaders of this market rally, with the group’s returns averaging 111% for 2023 and accounting for more than 60% of the S&P 500’s annual gain.

This was the opposite of 2022, the only year in history in which Treasury bonds and the S&P 500 both lost 10%. It was a year so rough that it marked the greatest destruction of wealth in modern history with an estimated $57.8 trillion lost across all asset classes combined.

And while 2023’s Big Tech-driven rally looks superb in headlines, a deeper glance shows this was not always the case – especially when accounting for 2022’s steep losses. In fact, on a 3-year cumulative basis, the indexes’ performances make a strong case for investing in indexes over ETFs.
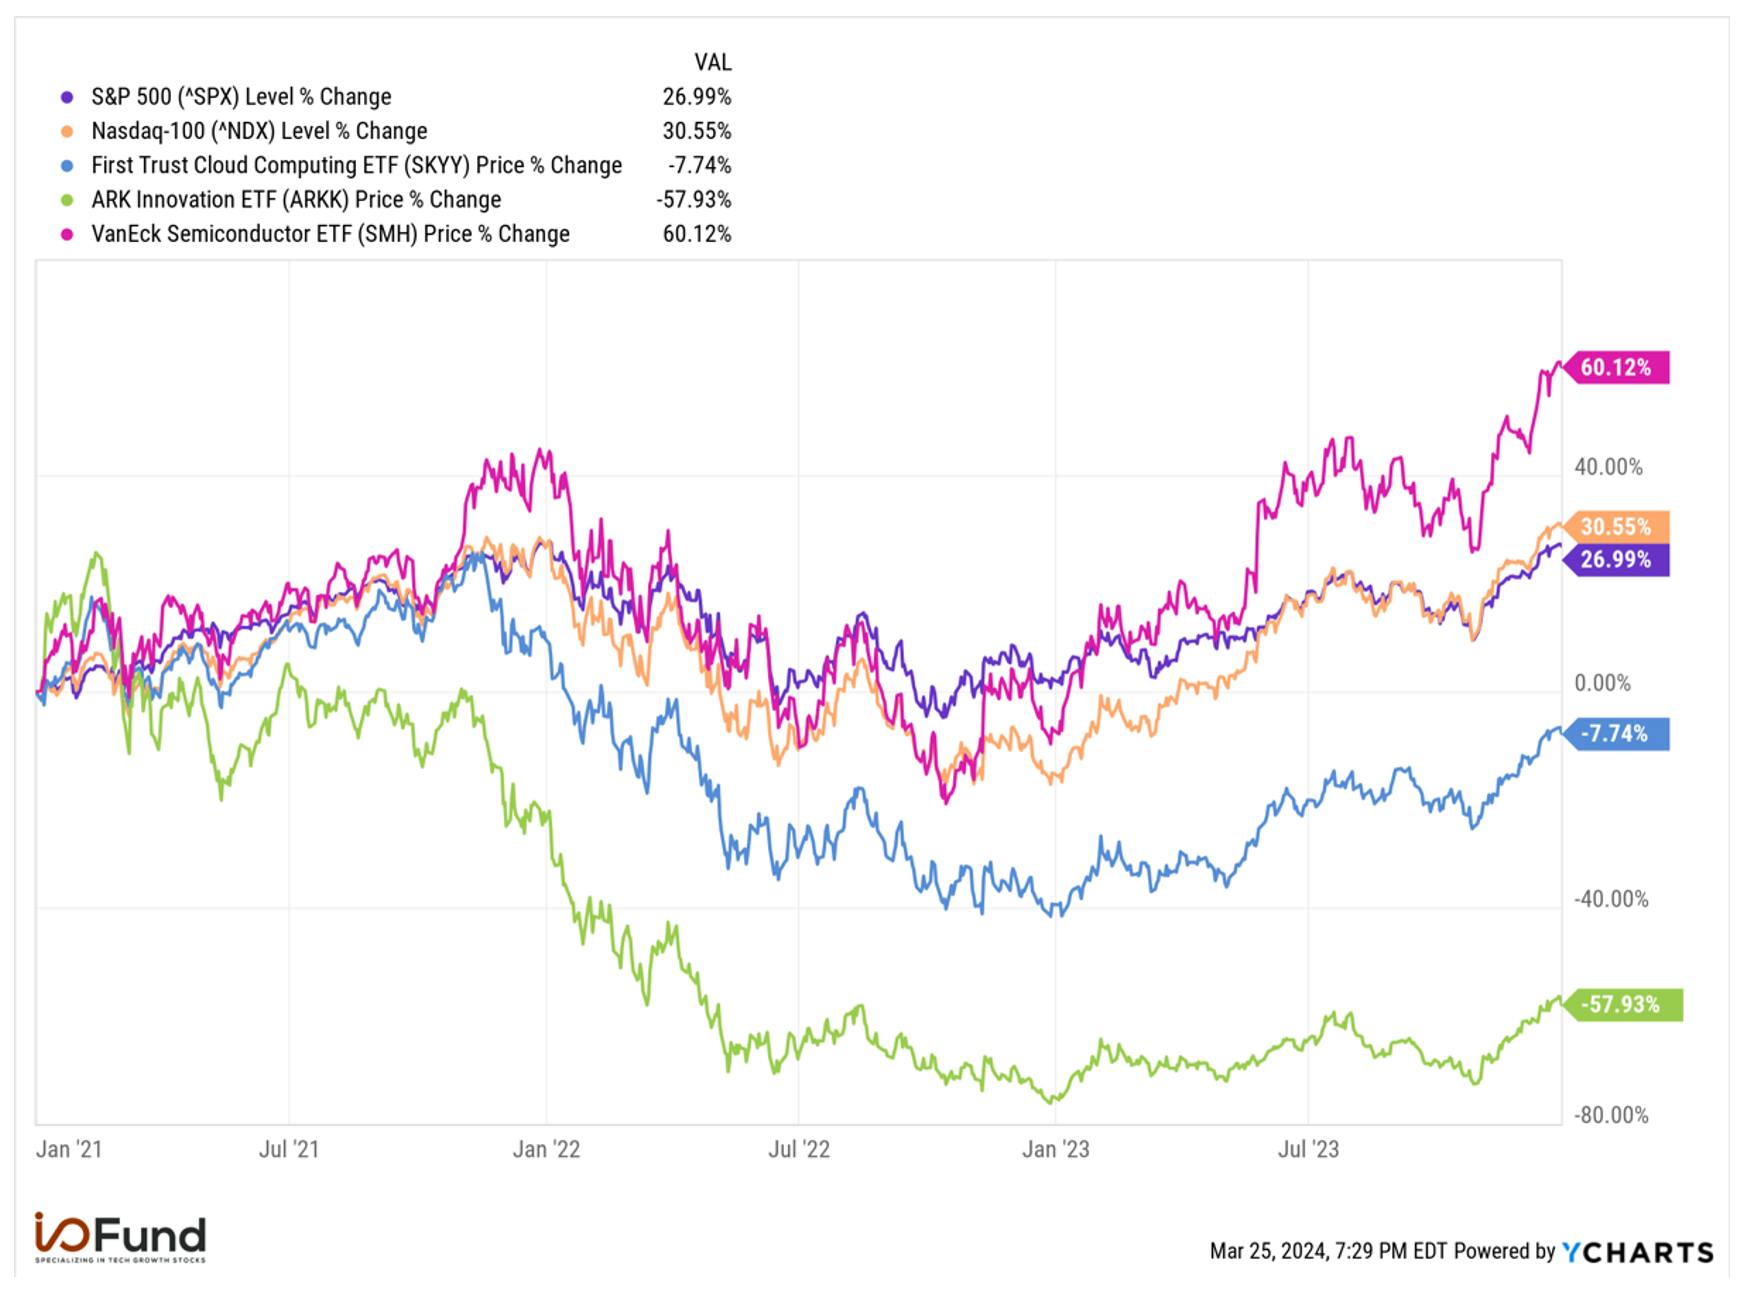
broad market stocks level % change

Simply put, allocating only to a leading sector, such as cloud in 2020 and 2021, would lead to significant underperformance through 2022 and 2023, when multiples were cut dramatically as budgets were slashed. Semiconductors underperformed in mid to late 2022, but outperformed significantly in mid to late 2023. It’s these disparities in between different sectors of tech that prove the value of active investing versus passive investing.  

Our firm believes that having an actively managed portfolio is where you get the best of both world’s – performance that far exceeds the indexes and ETFs by paying close attention to allocation, (quickly) cutting stocks that do not meet specific criteria, and choosing stocks that have strong, fundamental strength.

The I/O Fund is releasing our official 2023 returns plus our updated cumulative returns next week --- so stay tuned to your inbox. Our returns help to prove an actively managed portfolio can exceed all indexes and major ETFs on a cumulative basis (that we are aware of).

However, before we release our returns, we think it’s prudent to discuss the importance of verified returns for retail investors. The I/O Fund goes to great lengths to deliver a rare level of transparency for our Members. This is not about a victory lap; it’s about raising the bar. We do not know of another research site that publishes every single trade in real-time, and then takes this further to have their performance independently verified. We do this because it’s the right thing to do, but there are other reasons putting our best foot forward with verified returns is important for retail investors.

The New Norm of Quant Trading Puts Retail at a Disadvantage

Algorithms account for up to three-quarters of equity trading volume, as hedge funds and investment banks are increasingly turning to algorithms and quant trading systems to outperform benchmarks. Algorithmic trading is one of the primary culprits to the extreme volatility seen in recent years, most notably with the flash crashes and rallies of 2020.

This creates a serious disadvantage for retail investors and those who do not have a team of Python developers to leverage quant systems that trade in the blink of an eye. Ray Dalio, the fund manager for Bridgestone, has openly discussed that the best approach to the modern-day stock market is what he calls “the man and machine.” His firm has 1,500-employees that use computer models to test hypotheses; which is just one of the many advantages hedge funds and institutions have over retailers.

According to Dalio, the ideal is to have an algorithm work alongside a portfolio manager for a customized approach to predicting the markets. Although the I/O Fund does not have a team of Python developers, we partnered with Vincent Duchaine of WealthUmbrella  in 2022 to close the gap between human-driven actions and emotionless machines.

This marked an important turnaround for our firm as we gave up what I would call “retail idealism” which centers around the idea that holding a stock for a long period of time is retail’s only defense. This works during times of economic expansion, but where this can go (horribly) wrong is when a new, more challenging macro changes the outlook for any given company.

For example, in 2022, hundreds of tech stocks finished down 70%, and nearly every tech stock finished down 50%. This includes the indestructible FAANGs, with many falling to trade at historic low valuations. An investor would have to be in denial to focus on the poor performance of an individual company rather than acknowledge something much bigger was going on. 2022 highlighted a crucial yet overlooked point (that we encourage our readers to do): let go of the idea that picking good stocks alone can save a portfolio in the tech industry and to instead fully embrace risk management tools.  

2023 reiterated this point very well – although numerous stocks saw face-ripping rallies, such as Nvidia’s 239% rally and Meta’s 156% gain, only a handful outperformed and ended with positive returns on a 2-year basis from 2022 through 2023. Looking at Meta, despite that 156% rally, it ended just 5.2% higher since the start of 2022. Tesla rallied nearly 102% in 2023, but since the start of 2022, returns were (-29.5%). Alphabet’s 2-year return was (-2.6%), even with its 59% rally in 2023.

Risk Management Tools

In April 2022, the I/O Fund stopped relying on stock picks as the primary, offensive measure because this approach simply wasn’t working with the new macro. After partnering with Wealth Umbrella on an automated hedge, the I/O Fund began to boldly hedge up to 100% of our portfolio, at times, and we still continue this approach today.

We pivoted to playing defense rather than offense. Those who watch team sports will understand this transition well, as the strategy changes from attempting to make money (or make a goal) to a strategy that prevents losses (or prevents a goal).

Unlike many other all-tech portfolios and ETFs, we believe a more active stance is necessary for long-term tech investing. We also believe that the easy years of buy and hold are over, marked by the narrow leadership we saw in 2023 where a small number of stocks drove the rally last year. As a result, we rotate our portfolio frequently, raise cash and actively hedge our portfolio with an automated signal.

Real-time trade alerts are sent to our members the minute we decide to buy, sell, trim or add to a stock. For those who may not be aware, this is extremely challengingextremely challenging to do as it combines the two most advanced forms of portfolio management.

Beth Kindig, founder and lead tech analyst of I/O Fund

Get Our Free Weekly Stock Newsletter

Get weekly stock insights, market analysis, and technology updates straight to your inbox.

  • Weekly stock insights
  • Market analysis
  • Technology updates
  1. One of the most advanced forms of portfolio management is real-time trade alerts. This places immense pressure on a portfolio manager as the stakes are high to record what you do every second in real-time. To voluntarily choose to have the highest level of accountability in retail is nearly unheard of, yet registered fund managers are required to do this and file their stock trades.
  2. Secondly, hedging up to 100% of a portfolio is also a large psychological hurdle, and traditionally a risky one. Markets spend the vast majority of their history in uptrends, for one. Secondly, the amount you can lose on a short is literally infinite, to where one’s downside risk is capped at 0 on the long side. To overcome these hurdles, we have spent considerable resources developing a “man and machine” signal with the help of Wealth Umbrella that is truly state of the art.

It’s only natural for retail services to want to ease the pressure of having to report in real-time. The stakes are much higher when what you do is recorded the minute the action is taken, but overall, having the highest level of accountability possible has made the I/O Fund much sharper investors.

Logging trades in real-time also places immense pressure on the analysts at the I/O Fund, as well, who are not allowed to simply choose a stock but must also determine the allocation for the stock. After recommending a stock, the analysts must help the portfolio manager actively manage the position, which can change at any time.

There is a reason most services do not provide this level of transparency and activity. The more granularity that is offered, the more skill is required. Also, compare this to social media, where some investors will casually claim trades that were not logged in real-time.

Verified Returns

In addition to a lack of risk management tools, I believe a lack of verified returns in the retail space contributes to the losses this investor type experiences. Smart money is careful about who they consider a good investor -- they do not take someone’s word they are a good investor; they make the investors or firms they follow prove it. Every single hedge fund must report their returns, which reduces the chances of posturing.

Retail is not offered these checks and balances, and instead, this investor type follows many influencers and research sites who verbally state their performance without proper verification. Across the board, retail is offered a very low amount of accountability – this includes unverified month-end reviews, a list of stock tickers, unchecked screenshots, or other methods that are easy to manipulate. This widespread acceptance of loosely stating a stock performance is odd, to say the least, considering the finance industry is more inclined than any other industry toward deceptive practices.

How the I/O Fund Sets a High Bar for Accountability

Over the past three years, the I/O Fund has invested over $165,000 into accountability and transparency for our members. When we launched in July of 2019, for the first year or so, we used a forum hosted by Tribe for our trade alerts, but by January of 2021, we had migrated to SMS and email tools that were the least likely to experience an outage for our real-time trade alerts. This costs us $30,000 to $40,000 per year, depending on our trading frequency.

In addition to this, we use an auditor from a large firm in San Francisco to mathematically review and verify the performance of our I/O Fund portfolio trading account and crypto account. The process is quite extensive and it takes up to four months to complete. This costs $4,500 per audit and we’ve completed five audits for a total of $22,500 spent on this process. Accountability is expensive but we feel it’s worth it.

Conclusion

I believe real investors take necessary steps to prove their returns, that they accept the pressure that comes with registering trades in real-time and that they do not expect anyone, under any circumstances, to lower their standards and accept an unverified number regarding portfolio performance. Due diligence on stocks requires scrutiny, and this same level of scrutiny should be applied to the company you keep in the finance industry. 

To put it simply, the I/O Fund was founded to bring the standards that smart money insists on to the retail investment class. We think retail will be empowered to outperform when their standards are higher on who they follow and what research they read, and when they refuse to accept a lower standard on transparency.

The I/O Fund is wrapping up our annual audit for 2023 this week (you can access our previous audits including here, here, here and here). We look forward to adhering to the high standards that retail investors deserve. You can look forward to our 2023 performance being published shortly.

Please note: The I/O Fund conducts research and draws conclusions for the Fund’s positions. We then share that information with our readers. This is not a guarantee of a stock’s performance. Please consult your personal financial advisor before buying any stock in the companies mentioned in this analysis.

Recommended Reading:

About the author

I/O Fund Team

I/O Fund Team

Team

Curation

Expand your knowledge

View all posts
Beyond Hyperscalers: Here’s the Next $1 Trillion AI Infrastructure Opportunity
AI STOCKS

Beyond Hyperscalers: Here’s the Next $1 Trillion AI Infrastructure Opportunity

Since 2022, Big Tech capex has been the clearest barometer of AI demand. But the market’s reaction to Google’s latest earnings shows investors are questioning how long that spending can last. While the market frets over hyperscalers’ cash flows, a second wave of AI infrastructure spending has quietly emerged, driven by enterprises and neocloud customers.

AI STOCKSOCT 30, 2026
Google’s $250 Billion AI Chip Opportunity Takes Aim at Nvidia
AI PLATFORMS

Google’s $250 Billion AI Chip Opportunity Takes Aim at Nvidia

In April, there was a major shift in the AI accelerator market, and for once, it didn’t come from Nvidia. Six months later, merchant TPUs are moving from announcement to commercial execution, with Google recognizing its first revenue from TPU systems in Q2 (from a small base). Last quarter, Cloud revenue growth accelerated to 82% for $24.8 billion, compared to $22.5 billion expected. In addition, new details around the TPU 8t show that Google’s threat to Nvidia is not limited to inference. At the time, we pointed out that Google may be one of Nvidia’s strongest AI challengers, as Big Tech is closest to the problems that accelerators must solve. The problem that Google is prioritizing is lower cost per token, with token economics becoming a predominant concern as AI spending is pushing Big Tech’s free cash flows into the red. Below, we discuss two reasons why Google’s AI story is about to change, not from advancements in AI software, but by going after one of the most profitable hardware businesses the tech industry has ever seen.

AI PLATFORMSOCT 23, 2026
AI Debt Nears $500 Billion in 2026: What It Means for Nvidia, Oracle, CoreWeave and AI Stocks
AI STOCKS

AI Debt Nears $500 Billion in 2026: What It Means for Nvidia, Oracle, CoreWeave and AI Stocks

AI-related debt reached $466 billion through September 2026, more than four times last year’s pace. We break down who is borrowing, the three ways new AI chip deals are being structured, and where interest costs land across Nvidia, Oracle, CoreWeave, Broadcom and Big Tech.

AI STOCKSOCT 23, 2026