
This article was originally published on Forbes on Mar 21, 2024,01:49 pm EDTForbes on Mar 21, 2024,01:49 pm EDT
Arm Holdings is positioned to capitalize on the growing adoption of artificial intelligence (AI) technologies, leveraging its established licensing model and extensive ecosystem to drive future growth. Arm's established licensing model offers a recurring and relatively stable income source, and the stock is seeing favorable price action due to the growing tailwinds from its higher-royalty v9 design supporting next-generation AI chips from Nvidia, Microsoft, Amazon and others.
Yet, despite Arm dominating the smartphone market with 99% share, the company has made very little on licensing compared to its partners. For example, mobile handsets created a $200+ billion segment for Apple, which relies on Arm technology for the iPhone, yet only resulted in (roughly) $3 billion for Arm. In this case, it was far better to own Apple.
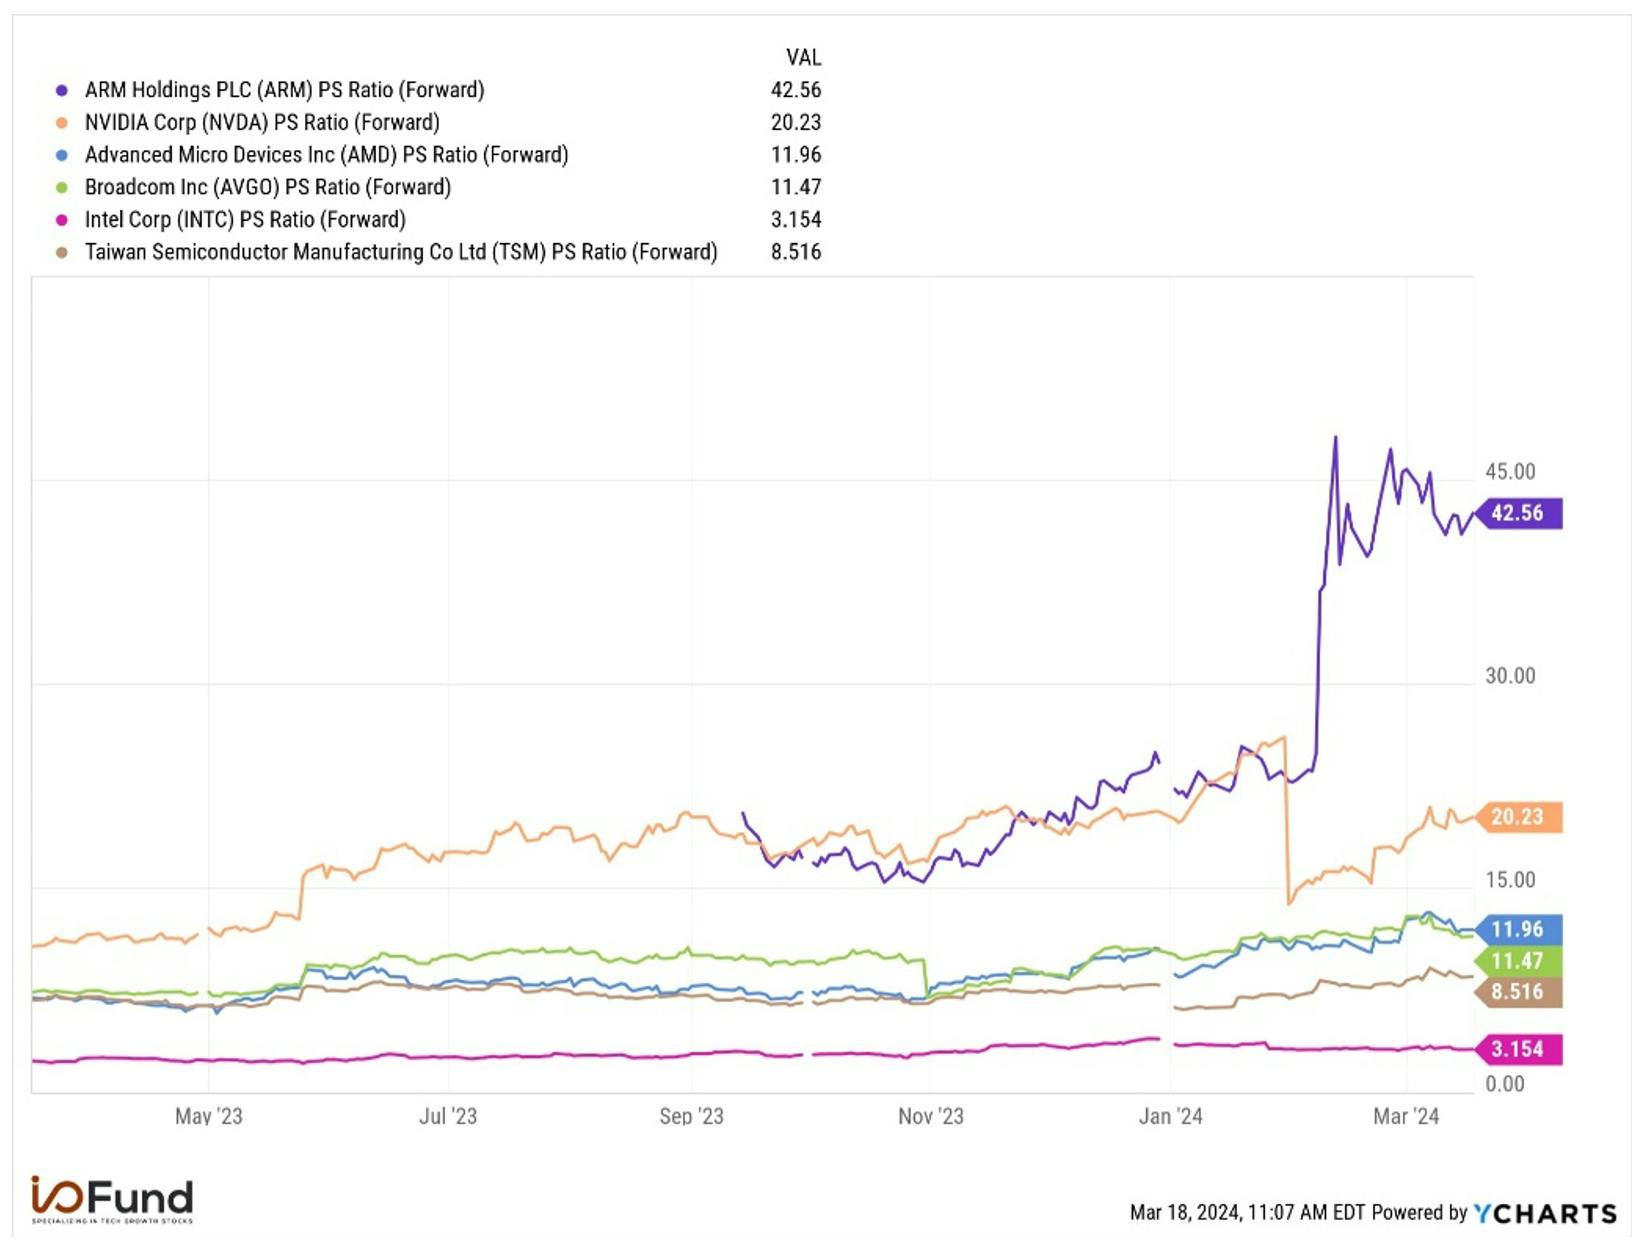
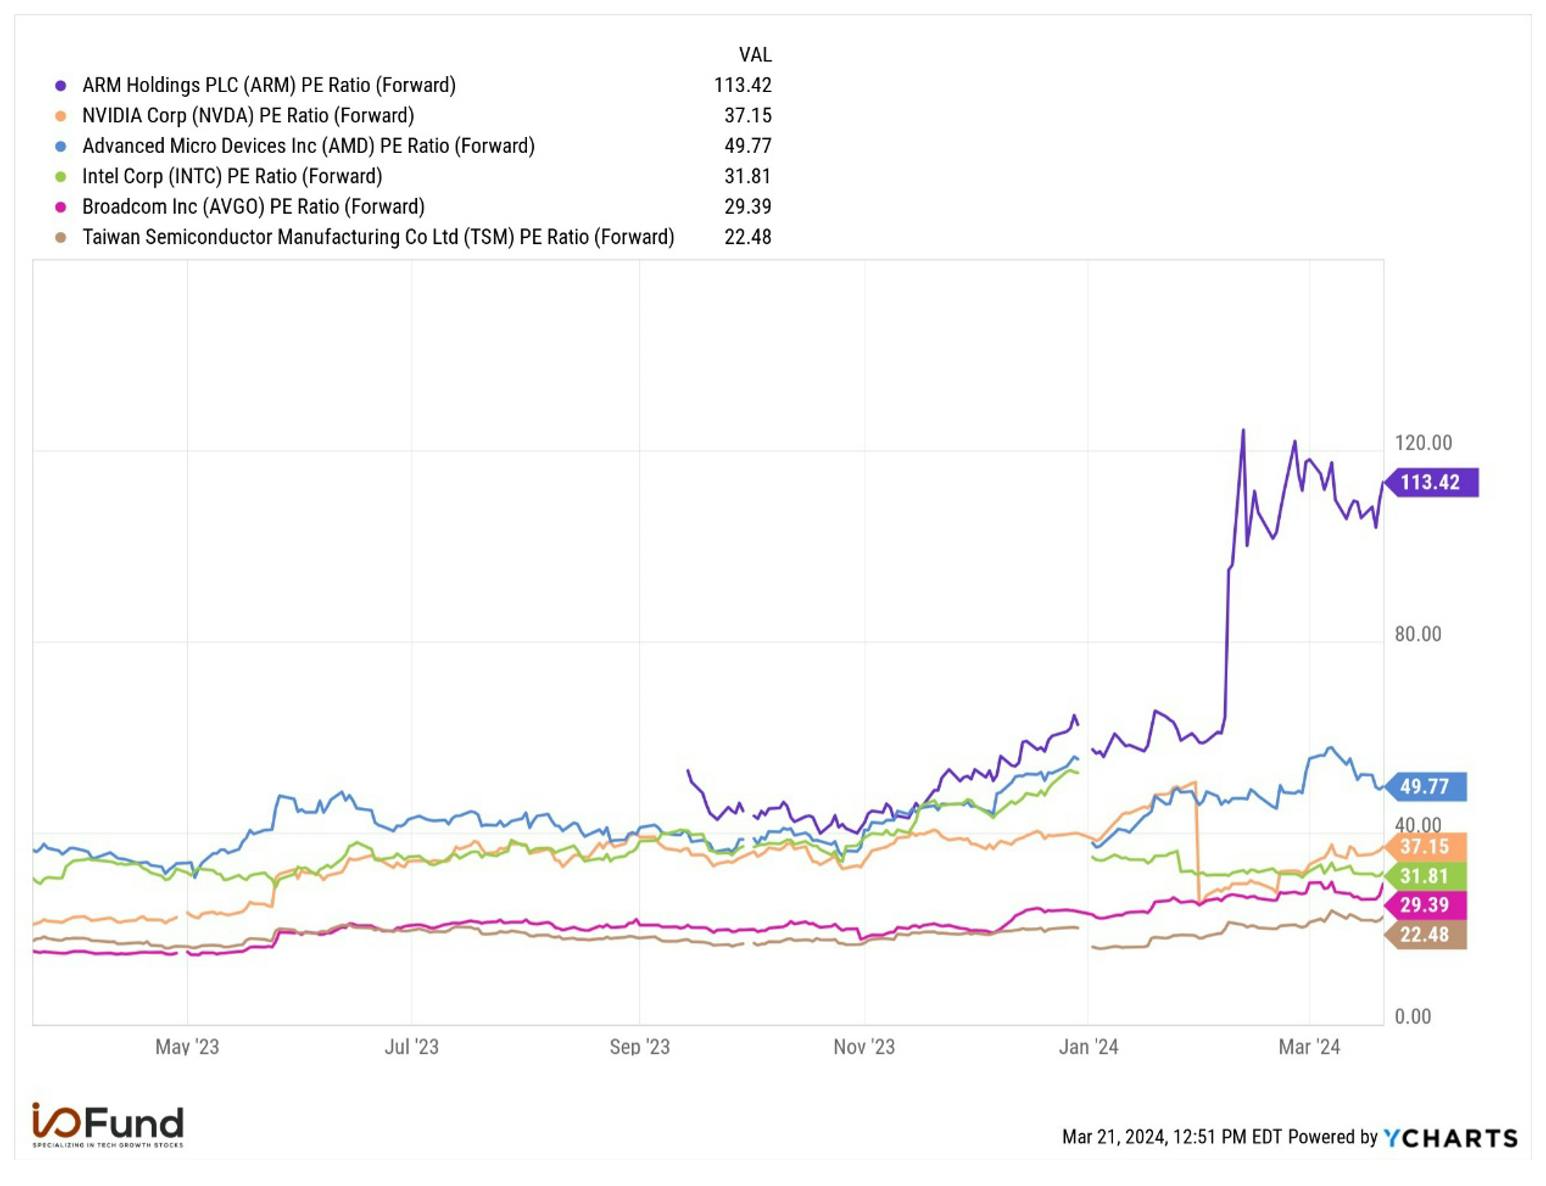
The market is excited about the fact that AI will drive double the licensing fees for Arm. My contention is that, similar to mobile, it’s better to own the AI leaders who license Arm’s technology rather than Arm. Analyst estimates have Arm growing to $6.5 billion by 2028. For our purposes, this isn’t high enough growth to ensure insiders, aka SoftBank, won’t take their exit following the IPO lock-up expiration. Frankly, the valuation on Arm is absurdly expensive, at more than double the most-expensive chip stocks, including Nvidia. This is why we’ve stated in the past that Arm makes a better acquisition target. For public investors’ purposes, there is no riskier proposition than an IPO that is richly valued.
Background on Arm
Arm offers the most popular CPU architecture in the world with 250 billion chips shipped since inception, of which 30.6 billion were shipped in FY2023. It’s most dominant in mobile CPUs with 99% market share, and 40.8% in automotive, for an overall share of 48% in Arm’s related markets. This dominant market share is achieved through its developer ecosystem.
For mobile (and how it came to reach 99% share), Arm’s design known as “heterogenous compute” has helped facilitate lower power requirements as the architecture allows different CPU parts to work together for improved efficiency. This enables workloads to work across both high-performance and low-performance CPU cores to lower energy by balancing performance.
Arm’s different licensing models are the following:
Arm Total Access Agreements: It is a type of licensing model wherein the company provides a package of CPU designs and related technologies for an annual fee. The agreement has a fixed term and Arm reserves the right to modify the package by adding or removing specific products.
Arm Flexible Access Agreements: This model provides a selection of CPU designs and related technologies for an annual fee. However, the latest products are not included. In comparison, the total access agreement is a comprehensive package. Another key difference is that the customers need to pay a single-use license fee for specific products if they are included in the final chip design. Like total access agreements, the company reserves the right to modify the package.
Technology Licensing Agreements: It involves licensing a specific CPU design or technology to the customer for a fixed fee. The license can be used for a fixed term or the number of uses.
Architecture License Agreements: Under this agreement the customers design their own customized CPU designs using the Arm’s Instruction Set Architecture (ISA).
Arm’s v9 Architecture
The latest Arm v9 architecture offers significant improvements in performance and efficiency, particularly for artificial intelligence (AI) applications. This has led to increased adoption by its partners, particularly in the premium smartphone segment and with hyperscalers developing their own custom silicon for data center use.
CEO Rene Haas explained that the “premium smartphone is almost exclusively now v9, and virtually every high-end data centre chip is v9. When you look at Grace Hopper, when you look at Graviton, when you look at Microsoft Cobalt, these are all v9-based designs.” However, CFO Jason Child emphasized that Arm is “overweighted towards smartphones on v9, primarily because it’s an annual refresh cycle.”
Compared to the previous v8 architecture, v9 chips command double the royalty rate. This means Arm receives a higher percentage of the chip's selling price when a manufacturer uses v9 designs.
The rapid growth in v9 adoption and its higher royalty rates have already contributed to a significant increase in Arm's royalty revenue. v9 constituted 10% of royalty revenue in the September quarter and accelerated to 15% in the recent quarter. By doing the math, v9 revenue grew 69% QoQ to $70.5 million. As adoption continues to rise, the v9 architecture is expected to be a major driver of future royalty income growth for Arm.
Sign up for I/O Fund's free newsletter with gains of up to 221% - Click hereClick hereClick here
Addressable Market
The company’s total addressable market was $203 billion in 2022 and is expected to grow at a compound annual growth rate (CAGR) of 6.8% to $247 billion in CY2025. The company has maintained a market share of over 99% in the mobile applications processor market. It expects this market to grow at a CAGR of 6.4%, from $29.9 billion in 2022 to about $36 billion in 2025. The company estimates that the aggregate value of chips that contain Arm technology was $98.9 billion (48.9% market share) for the CY ending December 2022, up from 38.7% in 2014. Notably, the 6.8% CAGR is a low CAGR for an AI trend with AI chips expected to grow at a 38.2% CAGR.
Arm also has strong market share of 40.8% in the automotive chip market. Management expects the automotive chip market to grow from $18.8 billion in 2022 to $29.1 billion in 2025, growing at a CAGR of 15.7%.
The cloud compute chip market is expected to grow at a CAGR of 16.6% from $17.9 billion in CY2022 to $28.4 billion in CY2025. Arm’s market share in the cloud computing chip market has increased from 7.2% in CY2020 to 10.1% in CY2022. Since Arm-based chips are increasingly used in data centers, its market share is expected to increase significantly in the future.
Per the prospectus, “Arm-based chips have been gaining market share as CSPs, such as Amazon AWS and Alibaba, have started to deploy Arm products in their own in-house designed chips used in their data centers, and as other CSPs, such as Microsoft and Oracle, start to deploy chips designed by Arm licensees, such as Ampere. As a result, we expect our market share of cloud compute to grow significantly faster than the overall cloud compute market.”
Financials
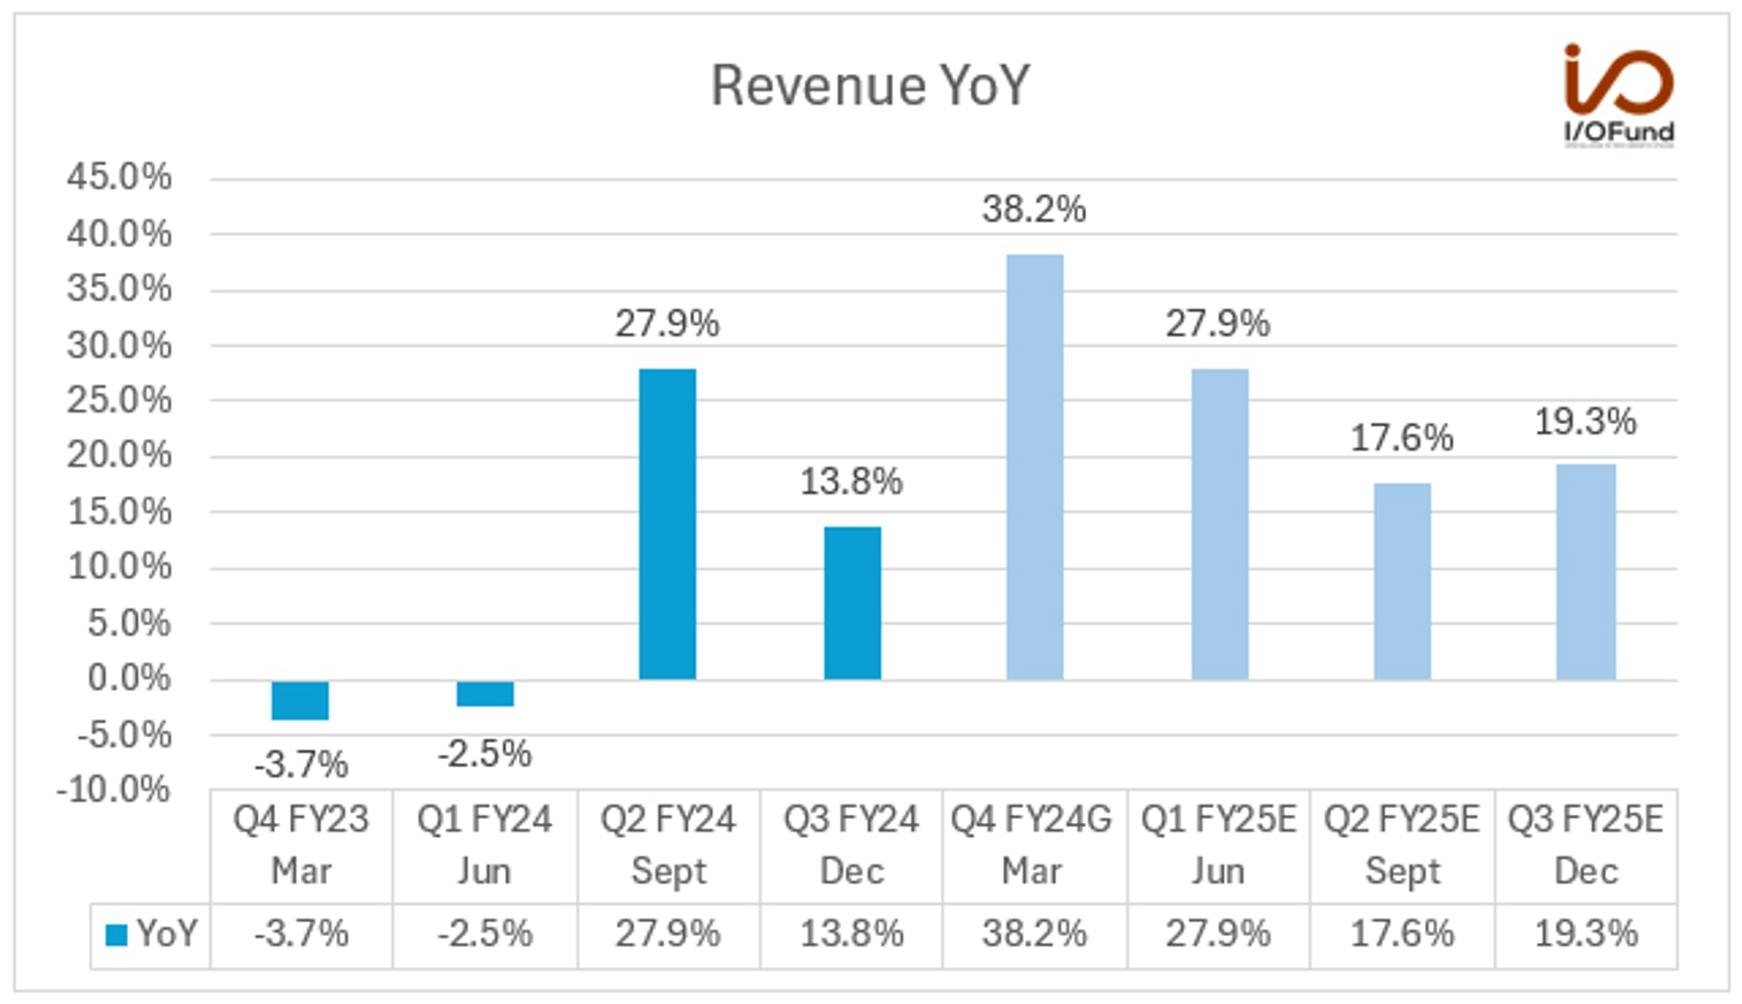
Arm’s recent Q3 FY2024 revenue ending December grew by 13.8% YoY to $824 million, helped by the recovery in the smartphone market and demand for AI technology. This marks the second consecutive quarter of positive revenue growth, following declines of (2.5%) in the June quarter and (3.7%) in the March quarter, due to the cyclical downturn from smartphones.
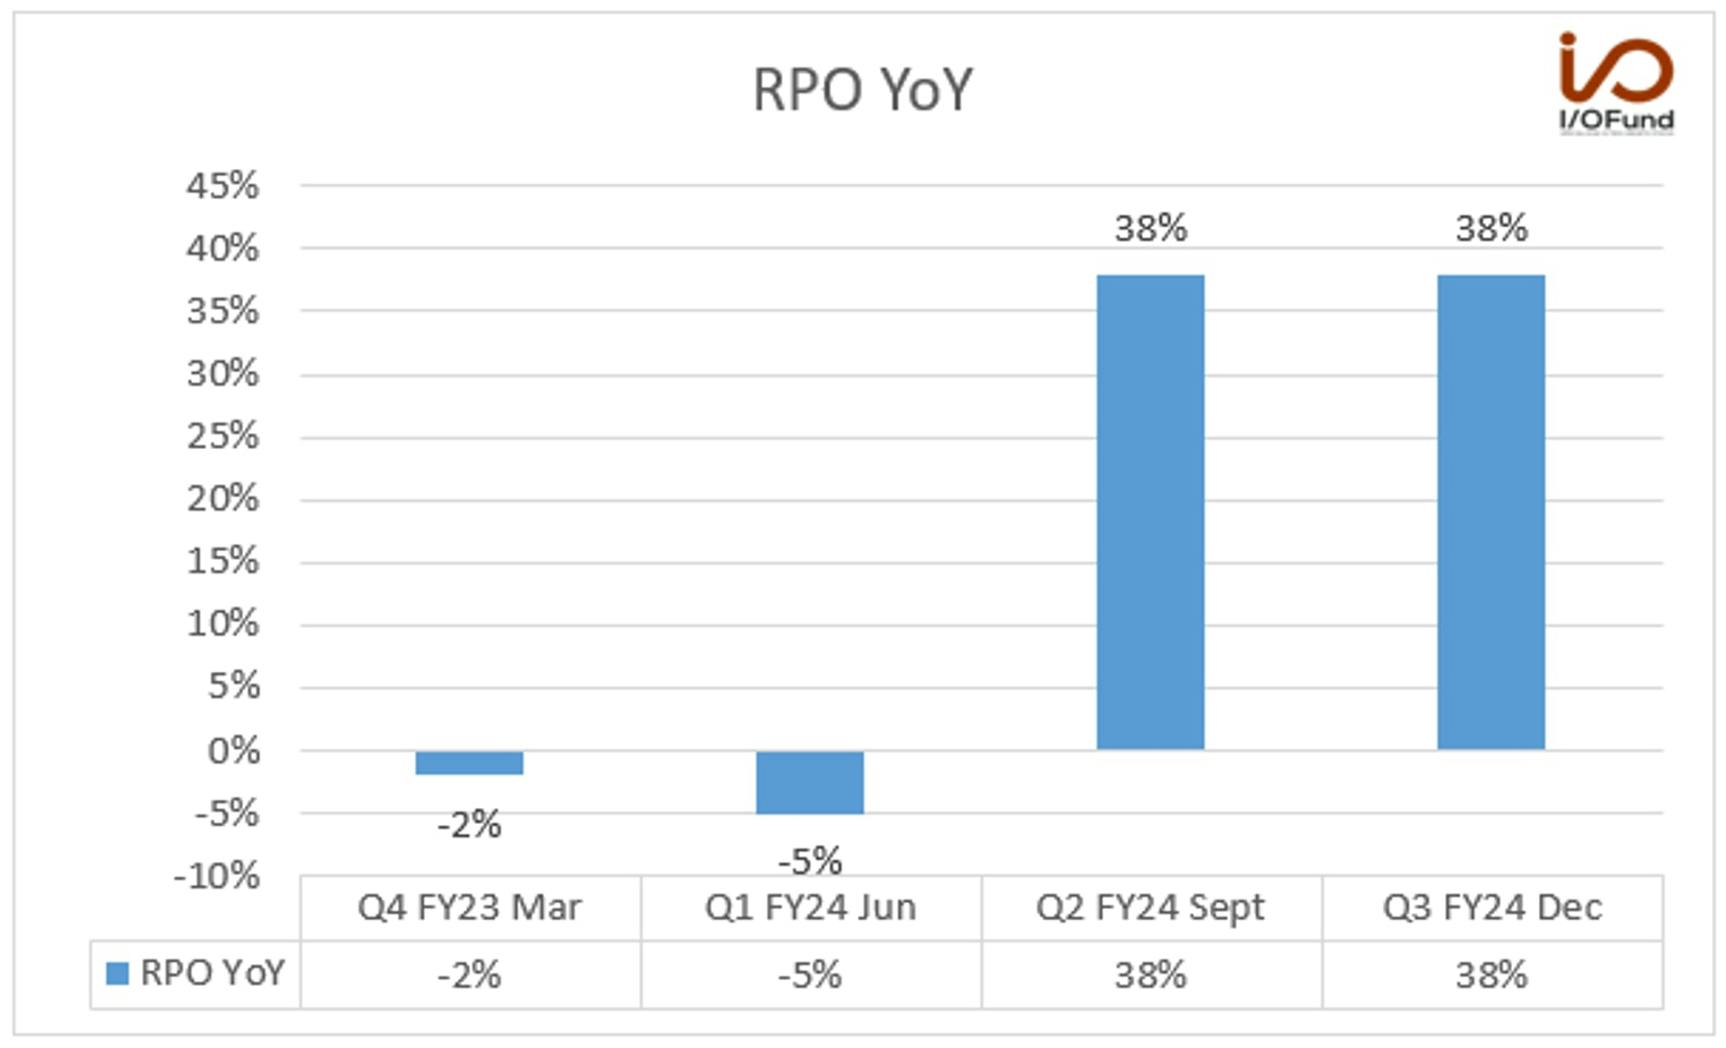
License and other revenue grew 18% YoY to $354 million. The company has seen strong growth in license revenue as they are signing long-term and high value agreements with its customers due to demand for Arm’s advanced CPUs to run AI workloads. The trend was strongest in the Sept quarter as license revenue grew by 106%.
CEO Rene Haas said in the earnings call, “And that has seen growth in not only the smartphone sector but also in infrastructure and other markets, which drives growth. We are also seeing strong momentum and tailwinds from all things AI. From the most complex devices on the planet for training and inference, the NVIDIA Grace Hopper 200 to edge devices such as the Gemini Nano Pixel 6 from Google or the Samsung Galaxy S24, more and more AI is running on more end devices, and that's all running on Arm.”strong momentum and tailwinds from all things AI. From the most complex devices on the planet for training and inference, the NVIDIA Grace Hopper 200 to edge devices such as the Gemini Nano Pixel 6 from Google or the Samsung Galaxy S24, more and more AI is running on more end devices, and that's all running on Arm.”
They expect another record quarter for the licensing revenue. CFO Jason Child said Arm is “expecting another strong quarter for licensing with revenue up sequentially to near record levels. As with recent quarters, we expect to sign multiple new ATA deals in Q4, and demand for our latest technology remains high as customers need access to AI-capable CPUs and related technology such as our Compute Subsystems.”we expect to sign multiple new ATA deals in Q4, and demand for our latest technology remains high as customers need access to AI-capable CPUs and related technology such as our Compute Subsystems.”
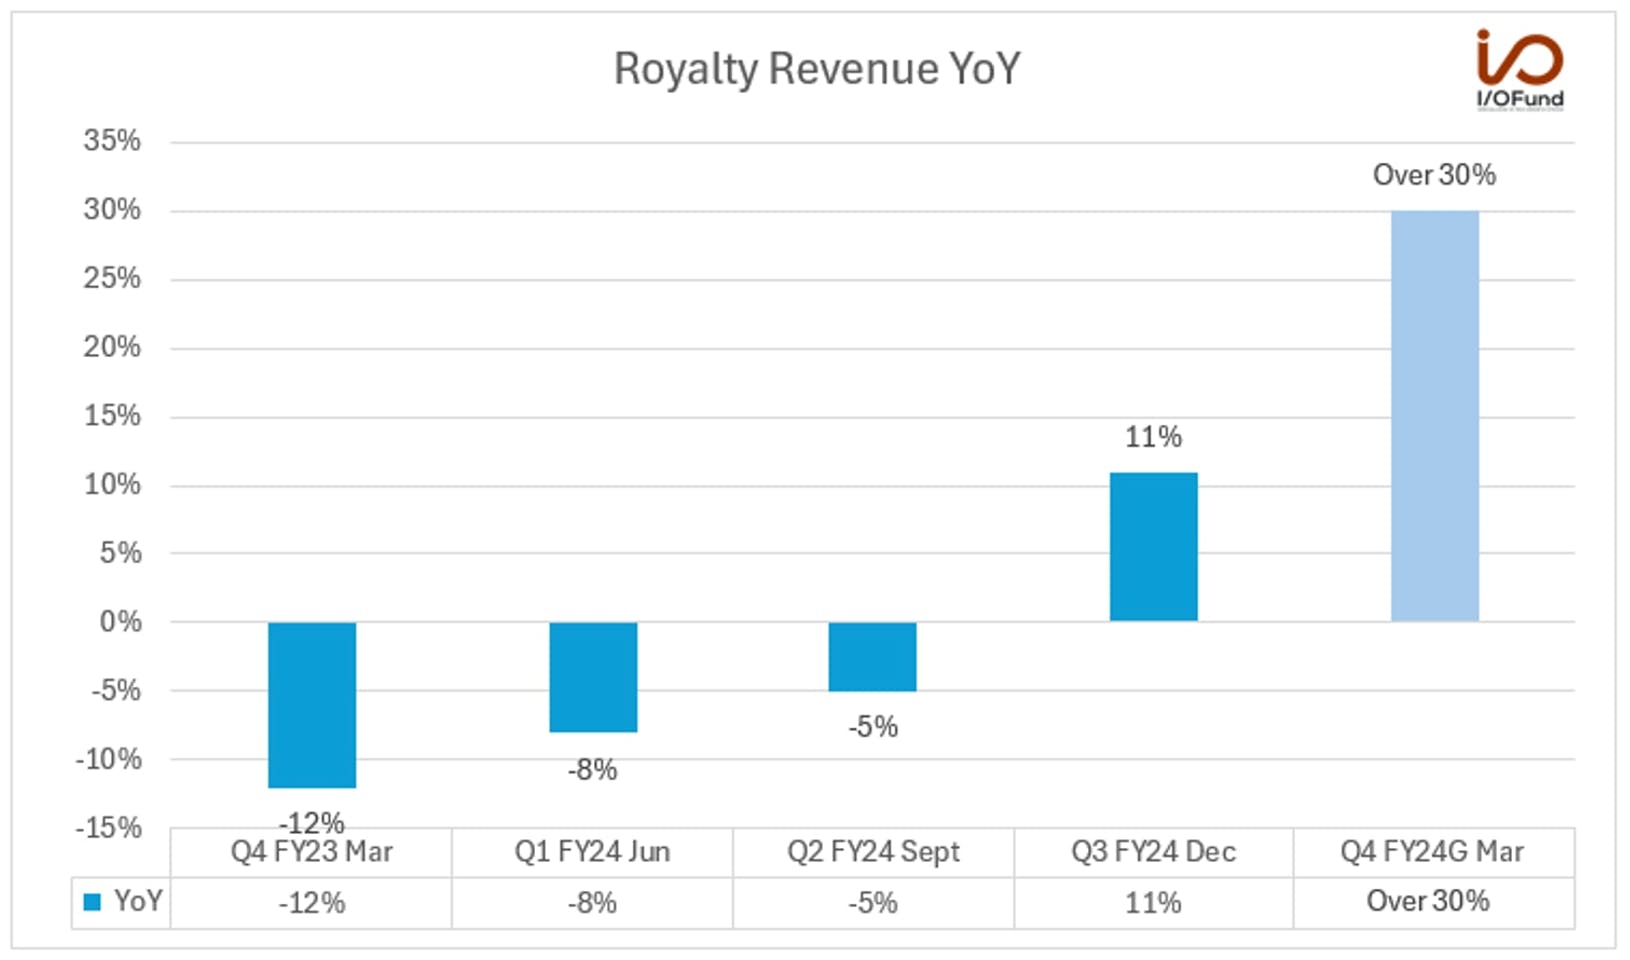
Arm reported record royalty revenue, thanks to its higher value v9 technology and market share gains in cloud server and automotive markets. Royalty revenue rebounded to 11% YoY growth to $470 million from a decline of (5%) and (8%) in the previous two quarters.
Management’s guide for the next quarter is to grow over 30% YoY, due to a weak comp against the “bottom of the industry wide inventory correction that occurred in prior year Q4.” On a sequential basis, royalty revenue was guided to increase by the mid-single digits.
Source: ARM
CFO Jason Child explained that the “sequential growth is mainly coming from increasing penetration of Arm v9, where royalty rates are on average, at least double the rates on equivalent Arm v8 products. Additionally, we are seeing an increasing amount of Arm technology in chips being deployed and as the amount of Arm technology in chips increases, so does the royalty rate.”increasing penetration of Arm v9, where royalty rates are on average, at least double the rates on equivalent Arm v8 products. Additionally, we are seeing an increasing amount of Arm technology in chips being deployed and as the amount of Arm technology in chips increases, so does the royalty rate.”