
This article was originally published on Forbes on Oct 27, 2022,11:14pm EDTForbes on Oct 27, 2022,11:14pm EDT
Netflix lost it’s status as a FAANG when the stock fell from a $300 billion market cap to a $100 billion market cap this year. My firm entered Netflix in August as we fully expect the stock to become a FAANG again due to its revenue potential from ads and improving cash profile.
Given macro, very few tech companies have a catalyst of any kind on the horizon with many companies in a defensive stance. Netflix, on the other hand, has an offensive plan to grow subscribers and revenue even in the face of macro pressures.
In my free newsletter published on Forbes, I had stated in both June and July: “I would argue the day that Netflix’s stock price dropped 35% was consequently one of the most important days in the company’s history in terms of its chances for a boost in revenue and a renewed uptrend. Patience, though, will be required, as Netflix has work to do.”
My target for the roll-out was originally Q1 to Q2 2023, and instead, Netflix is rolling out the ad supported tier next week. My firm had entered the stock in August with a real-time trade alert, so the surprise 6-month roll-out was welcomed. The ad supported tier will monetize at the same rate or even higher than legacy tiers with a $6.99 monthly subscription combined with a $10 ARPU over time (needs time to ramp to reach this ARPU).
A high probability of revenue acceleration from ad tier combined with improved cash profile combines for an attractive stock for 2023. Not only will Q4 and Q1 provide some clues around the new trajectory but there is an additional catalystan additional catalyst in Q1/Q2. We are reserving details about this lesser known catalyst for our research members.
The biggest names in tech are reporting their earnings right now, and our premium members are getting updates almost daily. Learn more about about our premium membership here.The biggest names in tech are reporting their earnings right now, and our premium members are getting updates almost daily. Learn more about about our premium membership here.Learn more about about our premium membership here.
Netflix is Expected to Return to 2021 Subscriber Growth Levels
Netflix had a sizable beat on subscribers and the stock breathed a visible sigh of relief as the company comfortably beat with 2.4M net adds compared to 1M to 1.2M expected. Consensus for next quarter was 4.1M with Netflix guiding for 4.5M. This will be the largest account growth since Q3 2021.
The largest contributor to growth is the APAC region at 1.4M new subs followed by EMEA at 0.6M subscribers and LatAm at 0.3M subscribers. United States and Canada reported 0.1M subscribers whereas in the past this region saw churn.
Revenue was up 5.9% compared to 4.7% expected. On a constant currency basis, revenue grew 13% YoY.
There is a miss on revenue for next quarter due to FX headwinds. The company guided for 1% growth versus 3.5% growth expected. On a constant currency, Q4 is expected to grow 9%. This creates a slight miss on FY2022 revenue at $31.5 billion guided versus $31.6 billion expected.
The AVOD tier is most likely targeting the 100M who are sharing passwords. Therefore, I believe Q1 is when the stronger results will appear from Netflix’s AVOD entry due to the password sharing being phased out early next year.
Here was the update:
“Finally, we’ve landed on a thoughtful approach to monetize account sharing and we’ll begin rolling this out more broadly starting in early 2023. After listening to consumer feedback, we are going to offer the ability for borrowers to transfer their Netflix profile into their own account, and for sharers to manage their devices more easily and to create sub-accounts (“extra member”), if they want to pay for family or friends. In countries with our lower-priced ad-supported plan, we expect the profile transfer option for borrowers to be especially popular.”
Operating margin came in higher than expected at 19% versus management’s previous guidance of 16%. There was a 4% decline from the previous year due to FX. The company is guiding for an operating margin of 4% to 8% next quarter, or 10% on a constant currency (CC) basis. This is due to seasonal spending on marketing and content, and on a CC basis, will be higher than last year’s 8.20%.
The revenue and operating margin beats flowed through to a net income beat of $1.39B compared to $961M expected.
Operating cash flow was at $557 million and free cash flow came in at $472 million. This means management has made good on its promise to see $1 billion FCF this year. It also implies FCF could be ($287) million next quarter as we are at $1.287 billion for the year.
Netflix reiterated regarding the FCF next year: “We continue to expect FCF of +$1 billion for the full year 2022, plus or minus a few hundred million dollars and substantial growth in FCF in 2023 (assuming no further material appreciation of the US dollar).”
There was a minor improvement in Netflix’s cash and debt levels with cash increasing to $300 million to $6.18B with net debt of $7.98B. This is down from net debt of $8.5B in the previous quarter.
The company had a big beat on EPS of $3.19 versus $2.17 expected. This included a $348 million non-cash unrealized gain from FX remeasurement on Euro denominated debt.
Was the Market Wrong About Netflix Saturation?
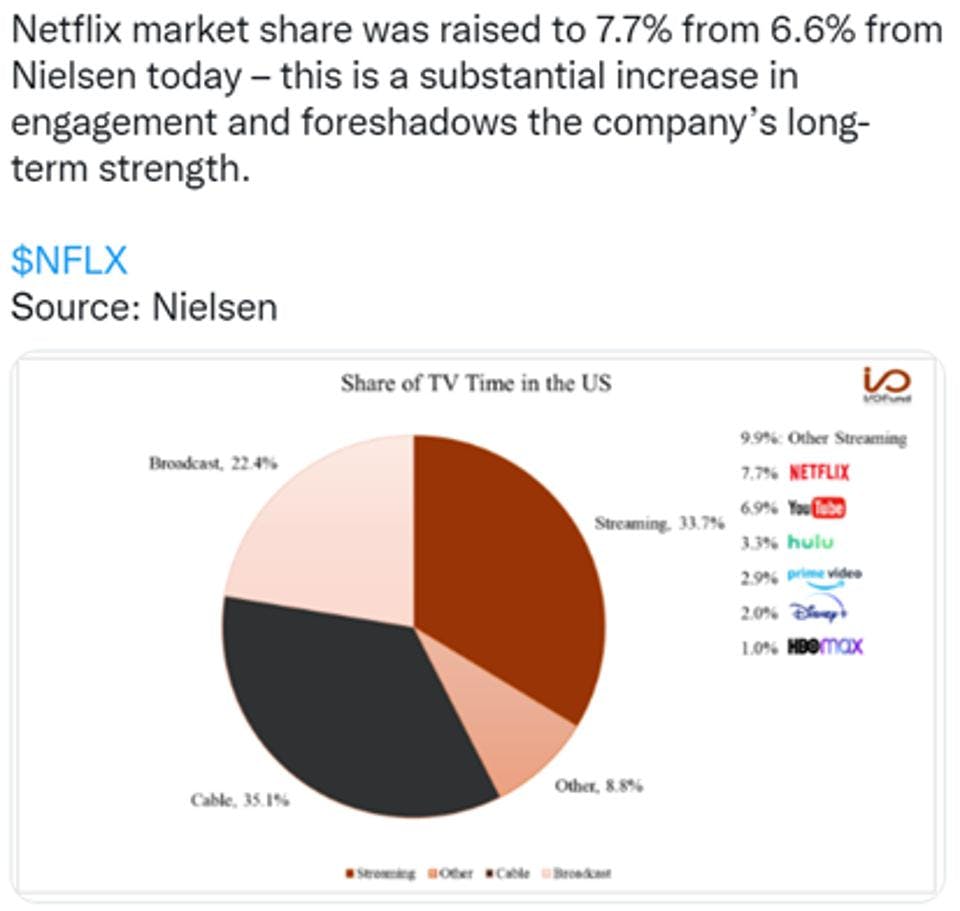
Netflix does not believe their market is saturated, rather that advertising opens up a new, sizable addressable market. The company offered the following information: “In the 190 countries in which we operate, our $30 billion-plus of annual revenue is roughly 5% of the combined estimated ~$300 billion pay TV/streaming industry, ~$180 billion branded advertising market, and $130 billion consumers spend annually on gaming. So, we believe that we have a long runway for growth if we can continue to improve our offering steadily over time.”