
This article was originally published on Forbes on Aug 23, 2023,12:30pm EDTForbes Forbes on Aug 23, 2023,12:30pm EDT
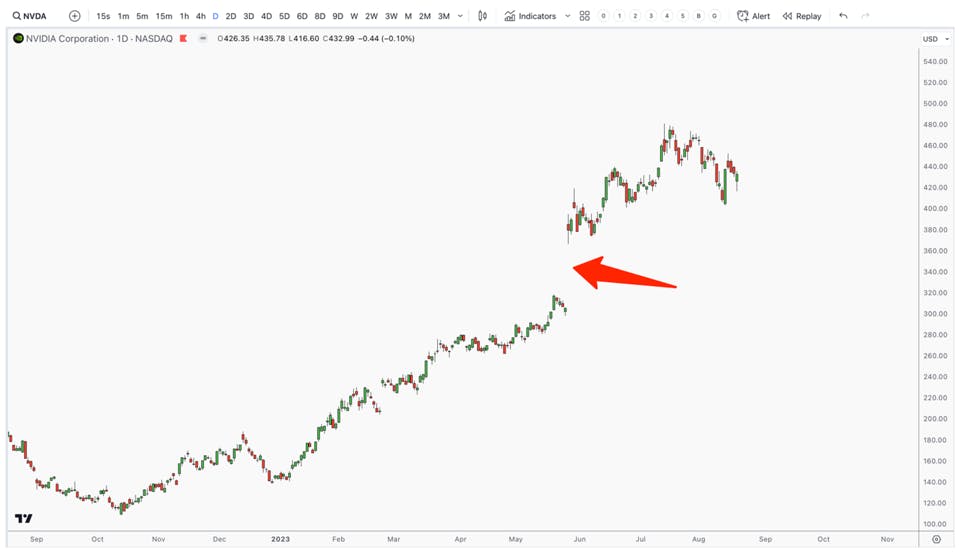
You’re probably well aware that last quarter, Nvidia guided fiscal Q2 at $11 billion, which is 53% higher than analyst expectations of $7.2 billion. The stock was up 25% after hours, adding $200 billion to its market cap in the matter of a day. During the earnings call, the stock went from being up 15% after hours to being up 25% after hours when the CFO confirmed H2 would also be strong with visibility on supply.
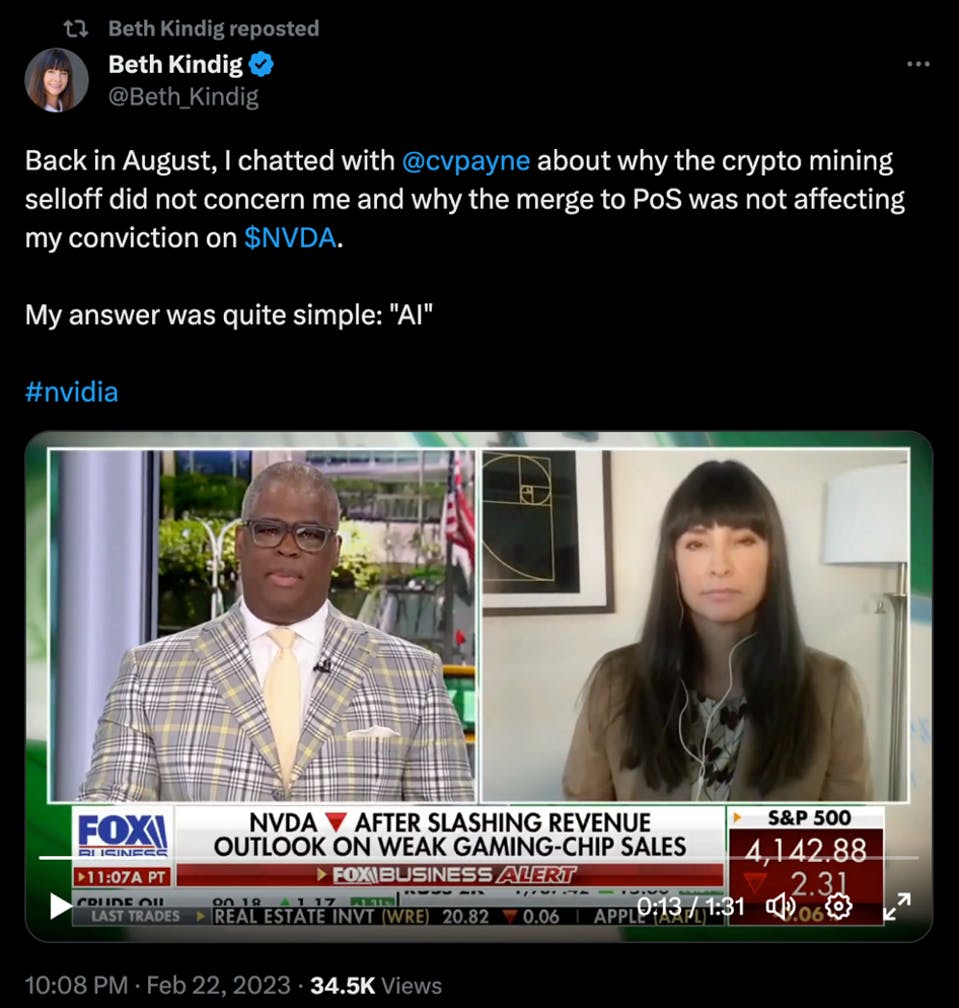
In addition to covering Nvidia’s AI angle many times since 2018, the I/O Fund holds an outsized Nvidia position at 17% allocation. Going into this year, we broke all of our portfolio management rules by holding a position that was over 10%. From there, we’ve talked consistently about a H2 2023 Semi Rebound to our premium members in webinars and analysis. I was also interviewed by Tier 1 media in August of 2022, and January of 2023about this very high conviction. As you know, Nvidia would later beat in May.
Source: BETH KINDIG
Well, it’s the day of Q2 earnings, so let’s cut to the chase … what should Nvidia investors do now?
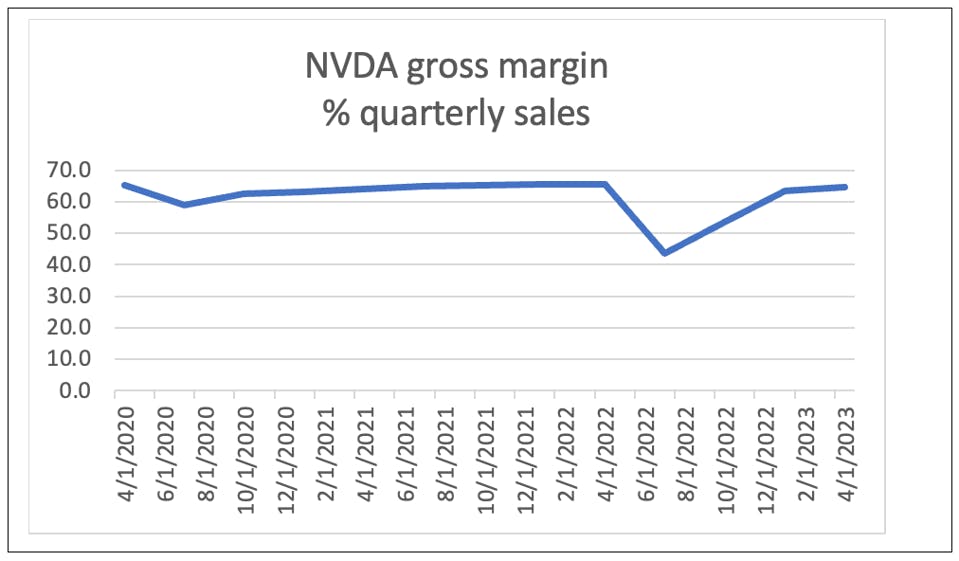
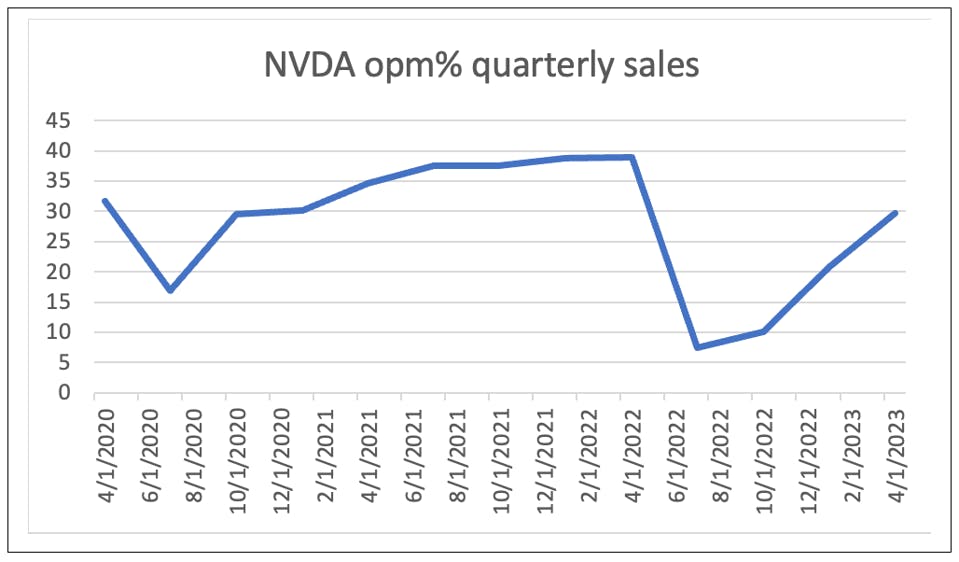
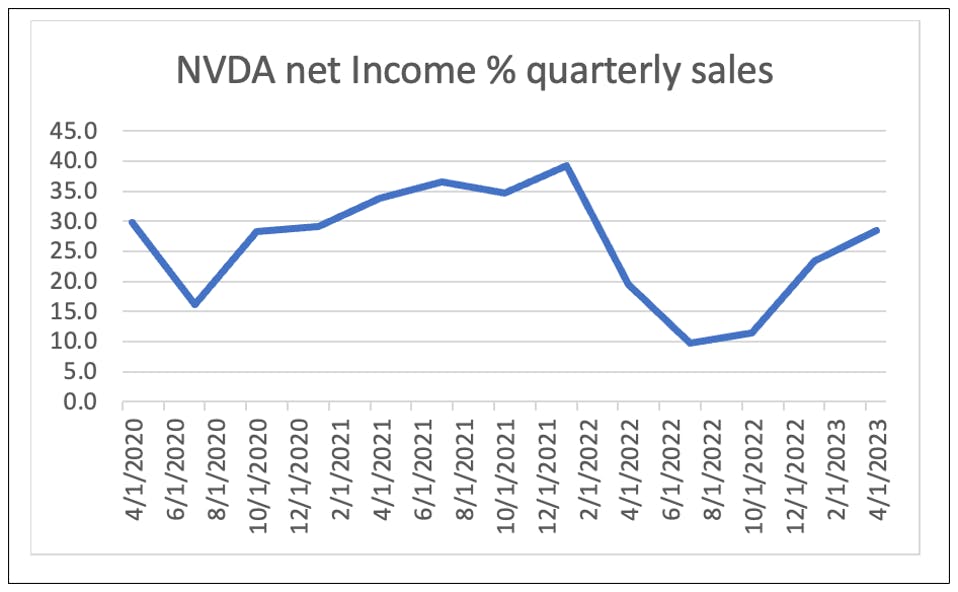
Below, we will review why it’s likely Nvidia beats and sees expanding margins, and secondly, we will review our plans for our outsized position. My firm is unique in that we do not simply offer blanket buy recommendations, rather we disclose our trades in real-time to our premium members. Please also note our disclosure below that we cannot guarantee a stock’s performance, but we can tell you how the firm is managing our money.
As a reminder, Super Micro had a sizable beat with management doubling fiscal year guidance three months later from 20% to 40%, yet the market reacted harshly. Therefore, it is the practice of our firm to have an active portfolio stance by combining fundamentals and technicals for risk management.
Nvidia Stock: Will a Beat Be Enough?
It’s not a stretch to say that anticipation within the investment community is on par with the series finale of Game of Thrones. Everyone in the market will be watching this earnings report come market close.
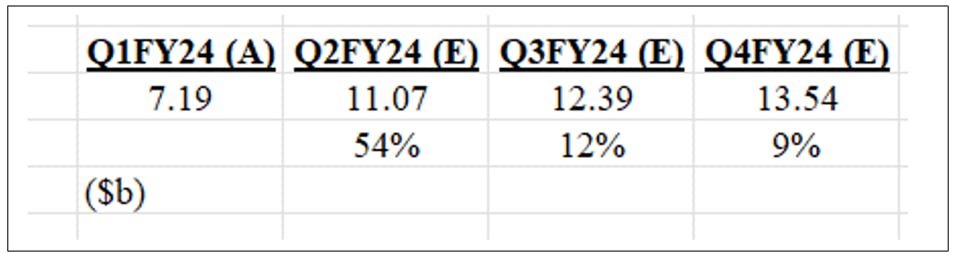
In its Q1 announcement, Nvidia provided a first glimpse into the financial impact AI will have on its businesses with Q2 sales guidance of $11.07b. The sequential increase of +54% vs Q1 surprised the market. We expect Nvidia to only provide guidance into Q3. Although just one quarter, it will be an important data point for the market to assess the appropriate growth rate for the remainder of FY2024 and FY25.
Q2 SALES + Q3 GUIDANCE
Meeting or beating Q2 sales guidance and providing Q3 sales guidance better than consensus will be very important drivers behind Nvidia’s short-term stock performance.
During the earnings call, this was one of the comments that contributed to strong price action after hours:
“Vivek Arya:
Thanks for the question. Could I just wanted to clarify does visibility mean data center sales can continue to grow sequentially in Q3 and Q4 or do they sustain at Q2 levels? […]
Colette Kress:
Yeah, Vivek. Thanks for the question. Let me see if I can add a little bit more color. We believe that the supply that we will have for the second half of the year will be substantially larger than H1. So, we are expecting not only the demand that we just saw in this last quarter, the demand that we have in Q2 for our forecast, but also planning on seeing something in the second half of the year. We just have to be careful here. But we are not here to guide on the second half of that. Yes, we do plan a substantial increase in the second half compared to the first half.
On 6/14/23, Collette Kress, Nvidia CFO held a Q&A at the Jefferies Investor Conference . In particular, there is one question on all investors’ minds.
Question
“You guys gave guidance for the July quarter, which beat everybody’s expectations and 50% sequential growth. And I think there is a concern from investors that this is kind of a one-time spike that will come back down. I know you only guide one quarter at a time. But what do you say to investors who have a concern that it’s a one-time spike? And can you just talk in general terms, what is the visibility typically like with the data center and hyperscale companies?”
Colette Kress
“Yes. What we have seen is certainly an astounding amount of interest worldwide globally from many different types of customer sets […] We have better visibility than what we have seen before and our ability to focus right now on procuring the supply.
As we indicated in our earnings, we have procured the supply to the demand that’s been put in front of us and that visibility that we see. […] So our guidance for Q2 is really building upon years and years of working of the industry on accelerated computing and solutions such as AI. And we continue to see demand and demand visibility for the full year as well that we believe will sustain as we finish in Q2.”
Comparing her response to consensus sales estimates for the remainder of FY24, we come away with a couple of observations.
Source: I/O FUND
- For Q2, consensus is in line with Nvidia’s guidance. There’s a chance that Nvidia will exceed their own forecasts
- If Nvidia has indeed procured the supply needed to meet demand, we believe that consensus Q2/Q3 growth estimates of +12% is too conservative.
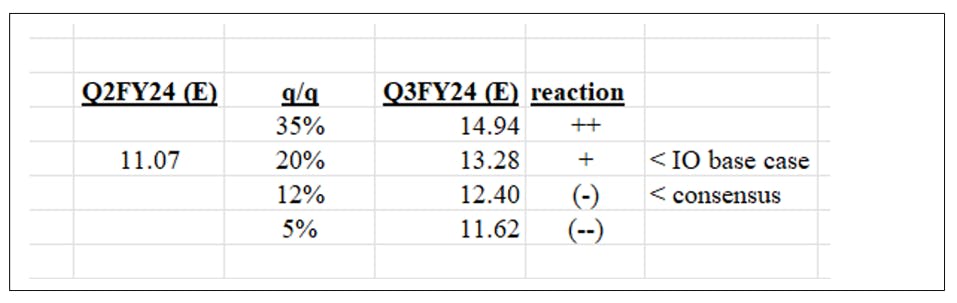
However, the magnitude of the Q3 guidance will be very important given heightened expectations. Assuming Nvidia meets its Q2 guidance, we’ve put together a simple scenario analysis to parameterize the different outcomes we anticipate based on Nvidia’s potential Q3 guidance. +/- indicates anticipated stock positive or negative price performance on the next trading day based on that scenario.
Source: I/O FUND
We’re optimistic that continued strength in AI related demand and stabilization in gaming will allow Nvidia to meet if not exceed their Q2 guidance. According to the Financial Times, “multiple sources close to Nvidia and its manufacturer, Taiwan Semiconductor Manufacturing Company, the chipmaker will ship about 550,000 of its latest H100 chips globally in 2023, primarily to US tech companies. Nvidia declined to comment.”
At $40,000 per H100, that equals $22 billion in H100 sales alone, and when you add the A100 and other data center sales at a current run rate of $14 billion, the data center segment could report a total of $36 billion in 2023. When you equal this out across the upcoming quarters, it looks something like this:
Q1: $3.5B A100s, $750M H100s = already reported, $4.2B
Q2: $3B A100s, $5B H100s = $8B data center, guided
Q3: $2B to $3.5B A100s, $7B H100s = $9B to $10.5B data center
Q4: $2B to $3.5B A100s, $10B H100s = $12B to $13.5B data center
H100s are priced differently depending on where they are sourced. The Information has the H100s at $20,000 yet sourced an analyst that believes we could see over 1M H100s sold in 2023. This arrives at $35 billion in sales. Given these variables, and credible sources, it appears $30 to $40 billion is the range going into Q2 earnings that analysts want to see for full year data center revenue.
We believe the market will react negatively if Nvidia provides Q3 guidance that is in-line with consensus or lower than 12%. On the flip side, Nvidia will likely need to provide guidance of at least greater than 20% for a significant positive reaction. This is because consensus will likely need to make upward revisions to their earnings for the remainder of FY2024 and FY2025. This is critical to support the current valuation.
Our base case assumption is that Nvidia’s Q3 guidance will estimate q/q growth of at least +20%. Remember, H100 was only introduced to the market toward the end of the last calendar year. Q1FY24 was the very first quarter where Nvidia is beginning to see the impact of AI and demand for the H100. Ultimately, we believe Nvidia will close out the year with data center revenue that is 50% higher than Q2.
Sign up for I/O Fund's free newsletter with gains of up to 221% - Click hereClick here