
Palantir’s Q4 report was nothing short of exceptional, propelling shares past the $100 milestone on a huge beat and raise with many strong growth metrics. AIP’s release just six quarters ago has proven to be a redefining moment for the company, as it has helped drive a nearly 23 percentage point revenue acceleration in such a short period of time.
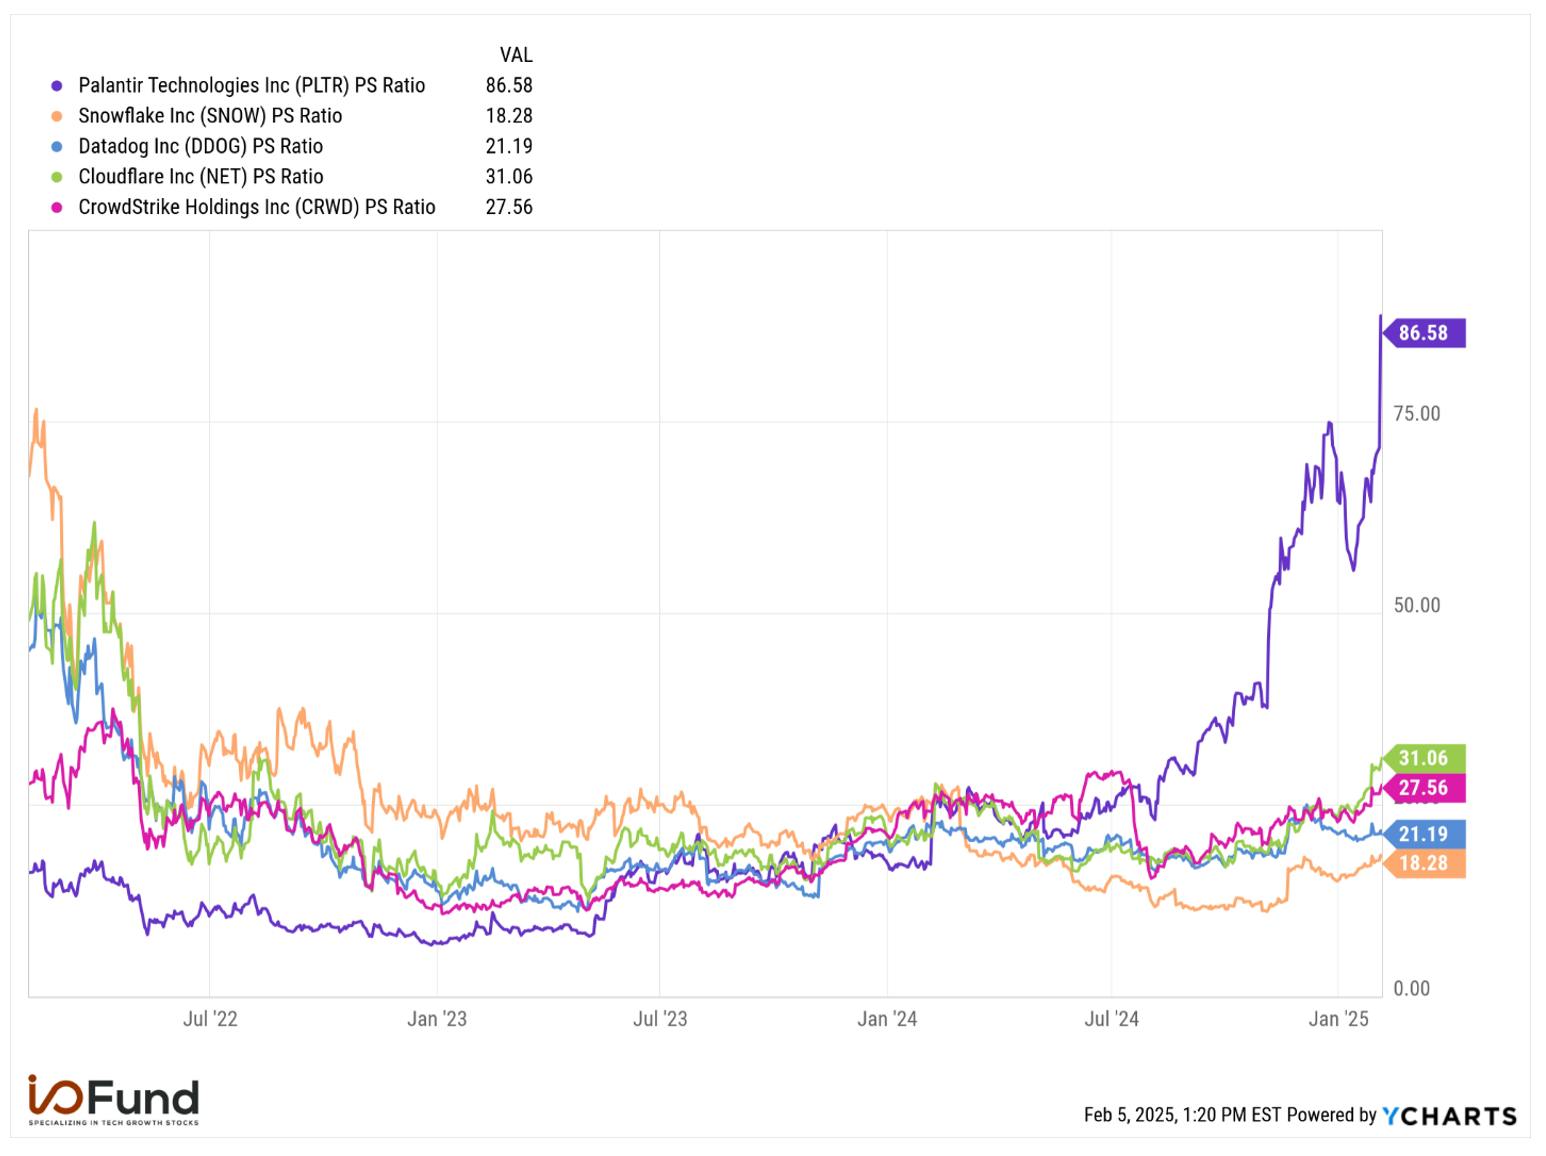
Palantir is in a league of its own – not only is it demonstrating significant growth contributions from AI offerings, but its valuation is now well beyond what’s typically viewed as ‘high’ in the software sector. As we had discussed in our October analysis, This Stock Is Crushing Salesforce, MongoDB And Snowflake In AI Revenue, Palantir is continuing to crush other leading AI favorites such as Snowflake or MongoDB when it comes to AI-driven growth.
Palantir’s Q4 Smashes Expectations
If beating its own guidance by nearly $60 million with revenue growth coming in 10 points ahead of said guidance isn’t enough proof of how strong this quarter was, there are many other metrics that display that strength.
Palantir reported $827.5 million in revenue for Q4, coming in far ahead of management’s $769 million guide and $781 million consensus estimates. This represented growth of 36% YoY, versus 26.4% guided and 28.4% expected. It also marked a 6 point sequential acceleration and a significant inflection in Palantir’s growth trajectory from the 12.7% growth reported in Q2 2023 when AIP was released.
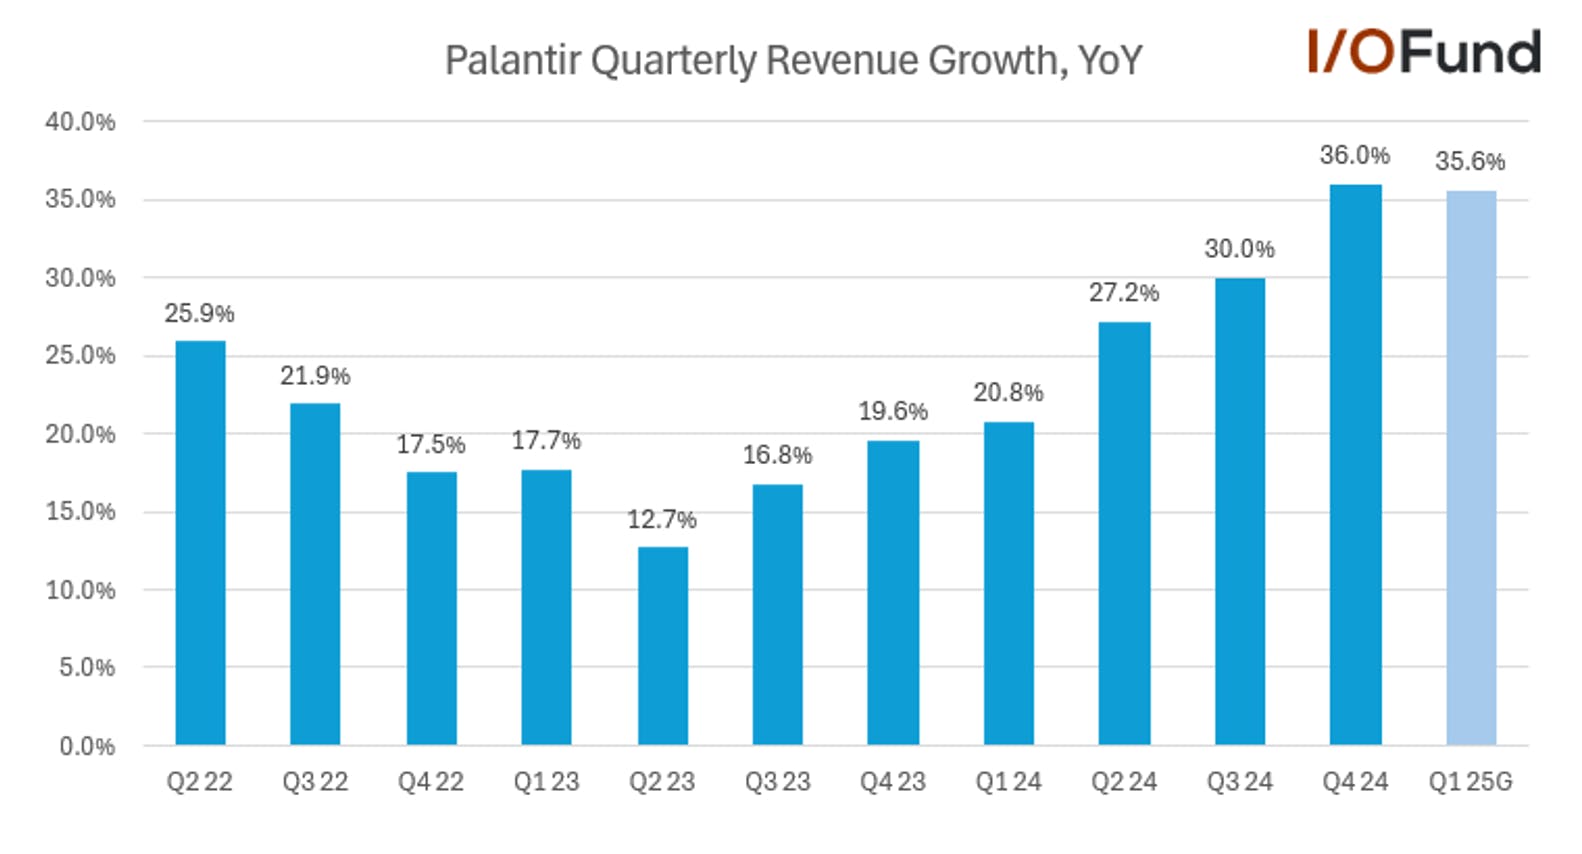
Q1’s guide was also impressive, with Palantir guiding for $858 to $862 million in revenue, or growth of 35.6%. Analysts were only estimating $799.3 million in revenue, or 26.0% growth, for the quarter. What’s important is that this guide sets the coveted 40% growth in sights: all it would take is a $30 million beat versus guidance for Palantir to report 40% growth for Q1. This was all but written off heading into Q4’s report, with both Q4 and Q1 expected to see ~26% growth – and Palantir smashed that out of the ballpark.
Fiscal 2025’s guide was also quite strong, with Palantir guiding for nearly 31% YoY growth to $3.749 billion at midpoint, a 2 point acceleration from the 28.8% growth reported for fiscal 2024. Analyst estimates were calling for just 25.6% growth to $3.53 billion in revenue in 2025, as management cited “unrelenting demand” for driving its “impressive outperformance.”
US Commercial Growth Wows in Q4
It’s not news that AIP continues to drive strong results for Palantir’s US commercial segment – management said each quarter in 2024 that the segment is “seeing unprecedented demand with AIP driving both new customer conversions and existing customer expansions.” If anything, I would argue that Q4 was the most deserving of high praise of any quarter this year.
Here are some of the top metrics from the quarter for US commercial:
- Record TCV closed of $803 million, up 134% YoY and 170% QoQ, beating the previous record by almost $400 million
- Record net new customers of 61, beating the previous high of 41; total customer count up 73% YoY and 19% QoQ to 382
- Remaining deal value (RDV) of $1.79 billion, up 99% YoY and 47% QoQ, and accounting for roughly 33% of total RDV
Palantir’s sales cycle has raised some concerns, with management acknowledging hiccups in its execution, saying at the start of 2024 that they are still “at the way early days of figuring out how to actually get customers to buy [AIP]” and “not flawlessly executing on our sales motion.” That friction had appeared through Q3 with a deceleration in net new customers for US commercial, though Q4 all but reversed that with a surge in new customers and blazing triple-digit growth in TCV.
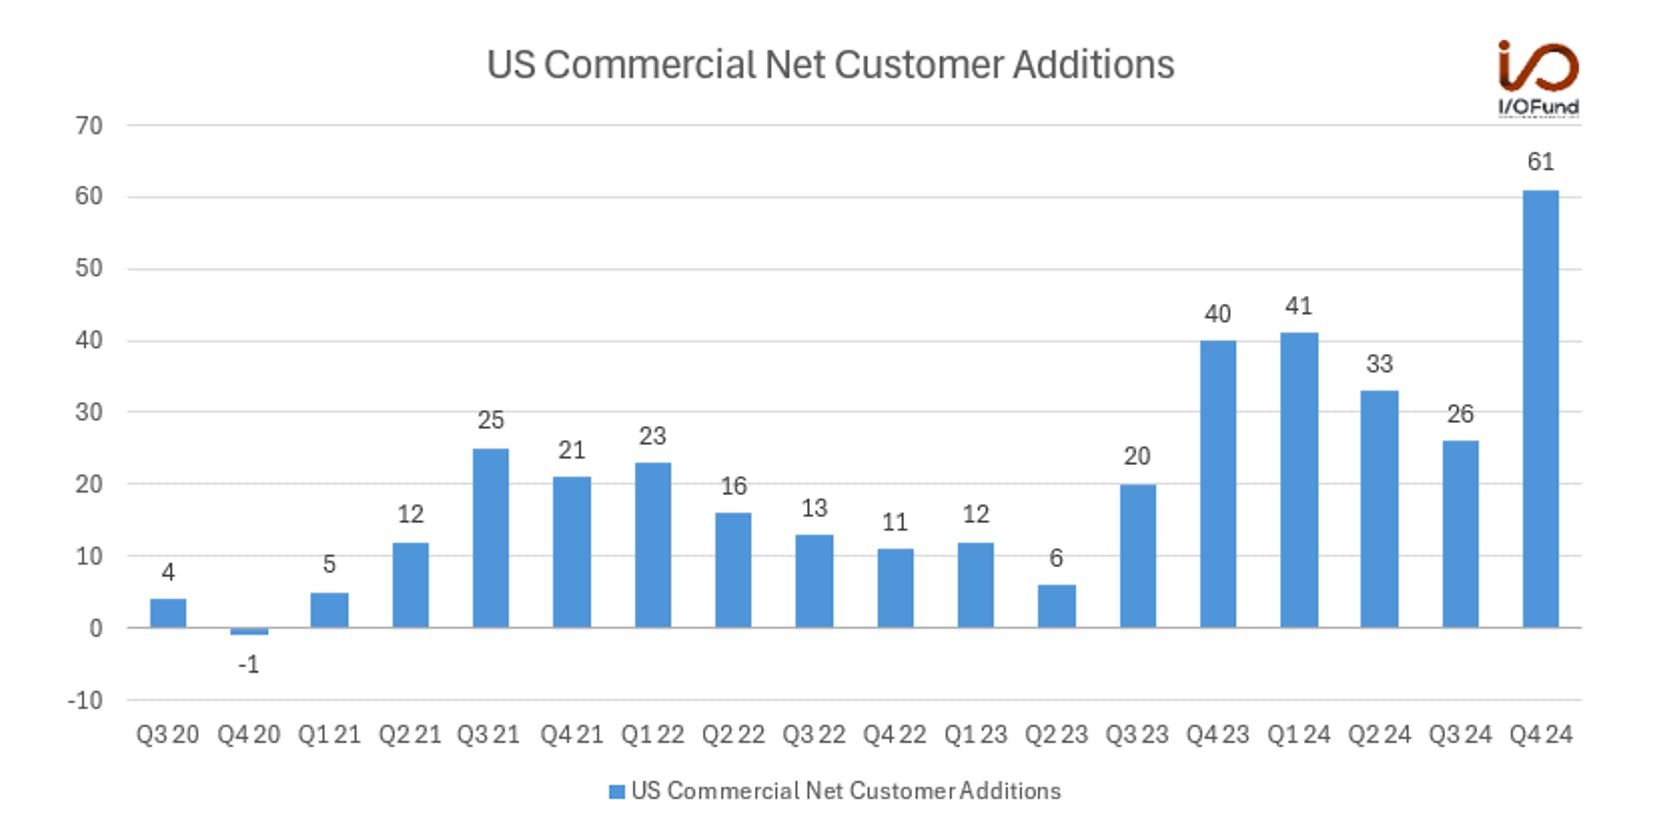
Management shared some TCV highlights, noting that a pharmaceutical company recently signed a $67 million TCV engagement shortly after a pilot, while a telecom firm signed a $40 million TCV expansion. Highlighting another customer success story, management said that “Panasonic Energy North America is seeing the effects of its AIP expansion as they’ve created a maintenance assistant to help 350 technicians in making 5.5 million batteries per day, resulting in reduced machine downtime, greater throughput, and rapid onboarding of new technicians.”
At the top-line, US commercial revenue rose 64% YoY and 20% QoQ to $214 million in Q4, on top of an already high 70% YoY comp from last year. For 2024, US commercial revenue rose 54% YoY to $702 million, exceeding Palantir’s guide for 50% growth.
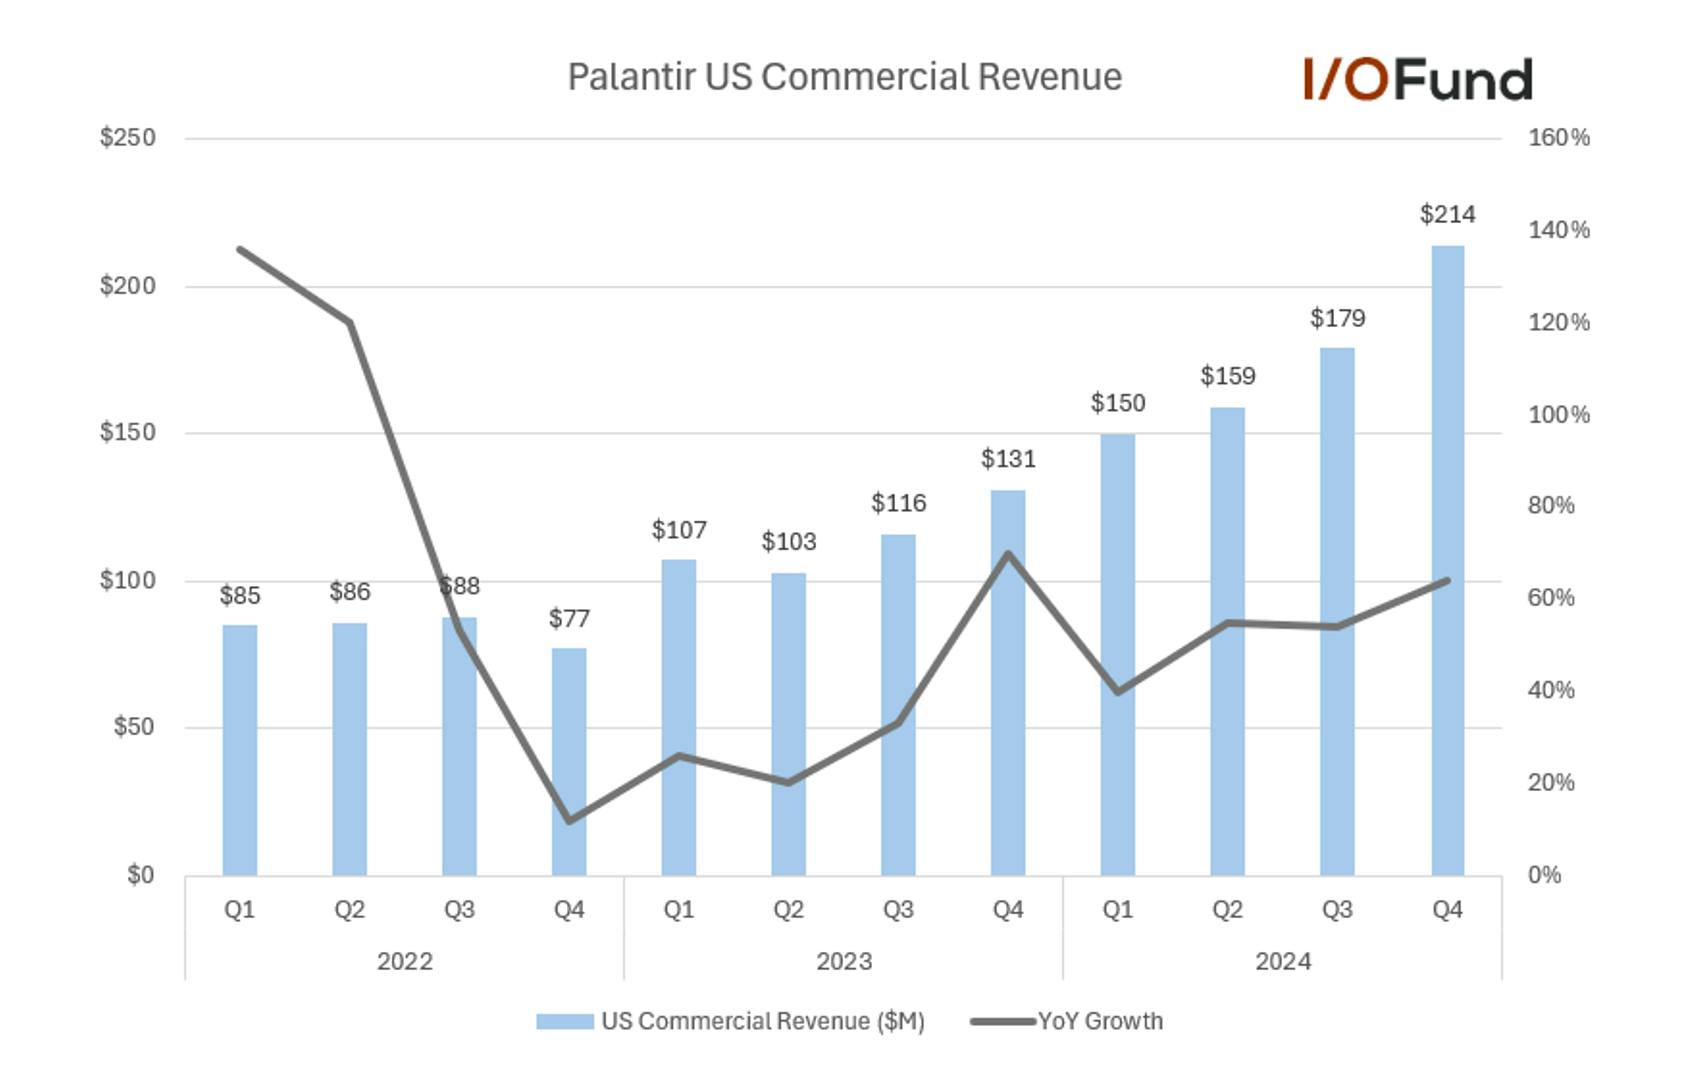
If 54% YoY growth for the segment wasn’t already strong enough, Palantir set the bar even higher for 2025 and guided for another 54% growth to at least $1.079 billion for the segment. Compare this to 2024 – Palantir initially guided for at least 40% growth for US commercial revenue, ending the year 14 points higher. For 2025, the pressure is on to deliver to these high expectations, starting where it left off in Q4.
International commercial has been a weaker spot, with revenue rising 3% YoY in both Q4 and Q3. Management shared that while they are working to “capitalize on targeted growth opportunities in Asia, the Middle East, and beyond,” Europe is lagging, contributing 13% of revenue with just 4% growth over the past year.
The I/O Fund recently made 5 different purchases in AI stocks at the end of January, while adding to multiple core positions. Advanced members received real-time trade alerts for each trade. Take advantage of our limited-time promotion for $50 off monthly Advanced plans – learn more here.
Government Leads the Way for Palantir’s Growth
While Palantir’s success in the commercial sector is quite clear by now, the government sector remains Palantir’s bread and butter. Interestingly, government outpaced commercial growth for the second quarter in a row, at 40% YoY versus 31% YoY.
In Q4, government revenue accelerated 7 points to 40% YoY to $455 million, accounting for 55% of total revenue. Within that, US government revenue increased 45% YoY to $343 million, up from 40% growth in Q3, and international government revenue rose 28% YoY and 26% QoQ to $112 million, benefiting from Palantir’s work with the NHS.
Palantir noted that customers like Anduril in the first Warp Speed cohort were already benefiting from the software in manufacturing – Anduril CIO Tom Bosco said that with the software, “we’ve seen up to 200x efficiency gain in our ability to anticipate and respond to supply shortages.”
Management also spoke confidently on FedStart, saying the offering “hit a major milestone with the approval of our FedRAMP High Environment for FedStart customers,” which is a “radical acceleration, both in reduction of time and costs of market access for software companies in the federal space.” Management added that CJADC2 (Combined Joint All Domain Command and Control) investments are continuing to deliver results while MAVEN is seeing significant adoption.
For the full year, government revenue rose 28% YoY, doubling 2023’s 14% growth rate. This was driven by 30% growth in US government revenue for the year, fueled by “continued execution in existing programs and new awards reflecting the growing demand for AI in our government software offerings.”
Palantir’s Margins, Cash Flows are Crazy
If accelerating revenue growth by more than 16 points in one year is considered impressive, Palantir’s margins and cash flows have been even better.
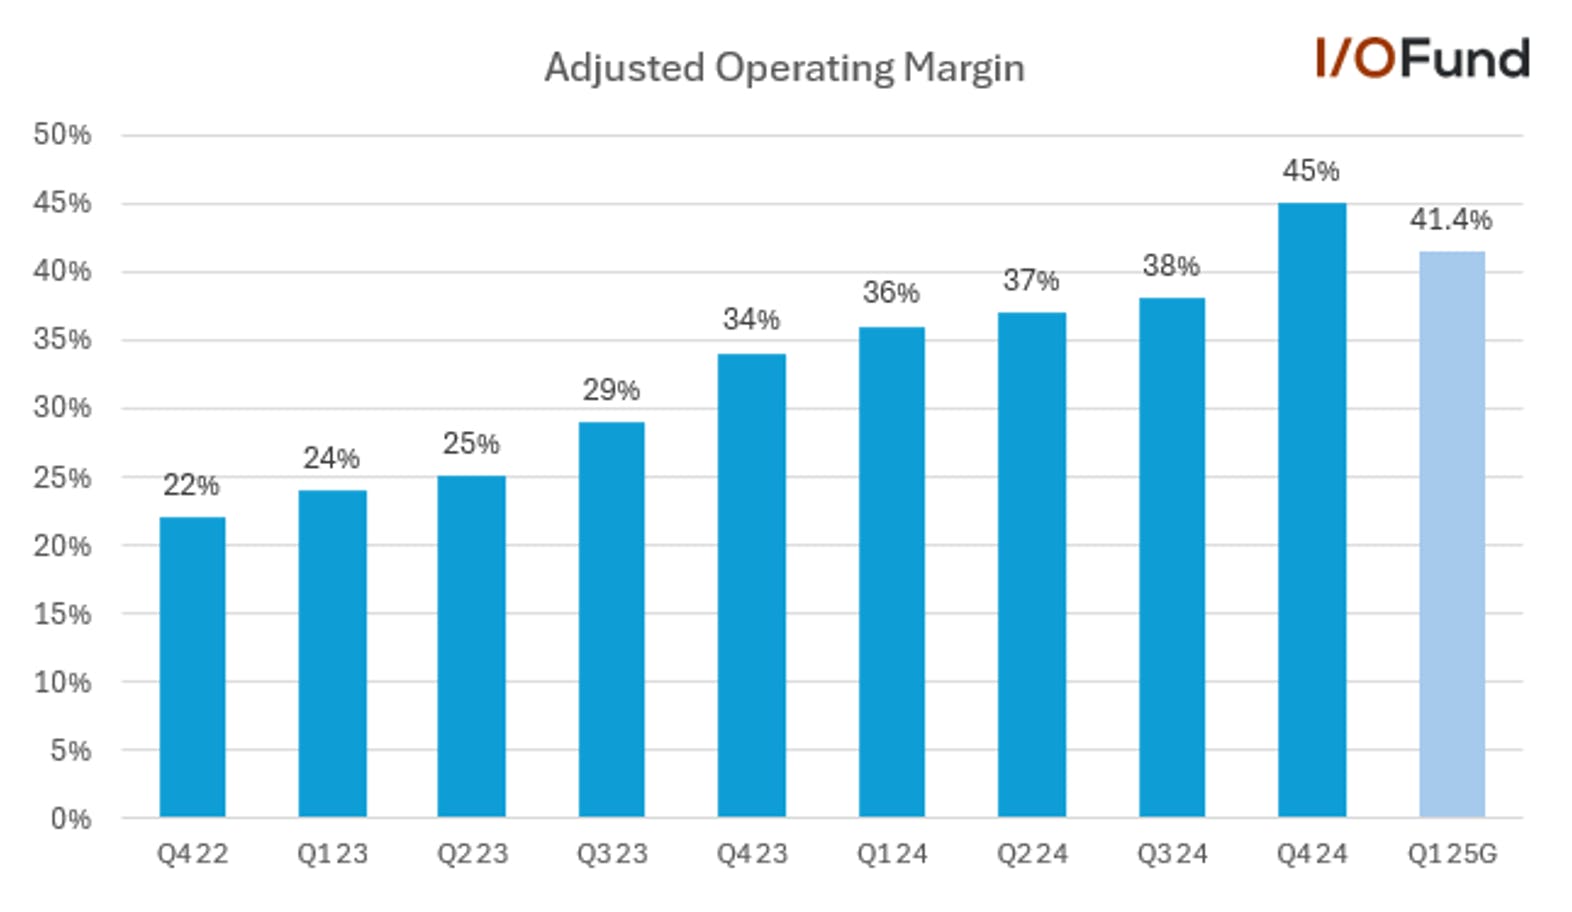
Adjusted operating margin has consistently expanded over the past two years, reaching 45% in Q4, up from the mid- to high-30% range over the past four quarters. For 2024, adjusted net margin was 39%, up from 28% in 2023.