This article was originally published on Forbes on Nov 7, 2024,09:08pm ESTForbesForbes on Nov 7, 2024,09:08pm EST
Two weeks ago, I highlighted that Palantir is “one of the rare few that sees AI drive both real returns for its business and real value for its customers,” while it continues to crush its software peers in AI-related growth. AI offerings have driven a clear acceleration in customers and overall revenue, while many SaaS peers, such as MongoDB and Salesforce, struggle to say the same.
This week, Palantir proved again in Q3 that it’s undeniably one of the stronger AI software stocks in the market outside of the cloud hyperscalers. The company reported visible AI-driven growth and persisting business momentum for AIP, strong revenue acceleration to 30% YoY, combined with strong profitability – a rare combination for growth stocks.
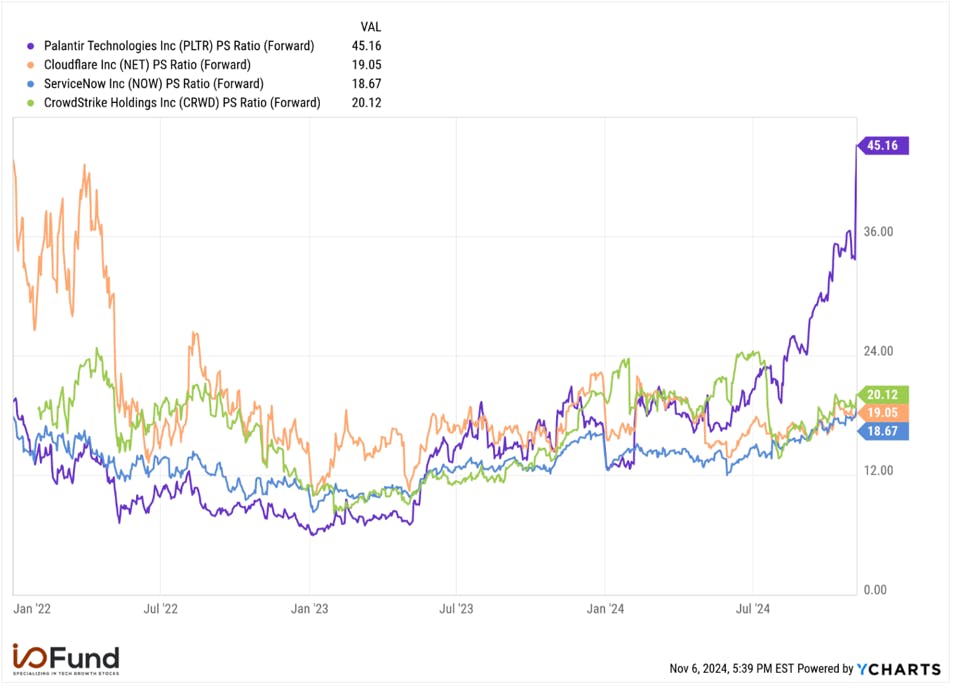
Despite proving again that it’s one of the only software names with real revenue in the market, Q3’s report pushed the valuation even higher. Due to an outlandish valuation, price momentum may soon be approaching a peak.
Sign up for I/O Fund's free newsletter with gains of up to 2600% because of Nvidia's epic run - Click hereClick hereClick here
Blistering AI Momentum Continues
Palantir’s third quarter was characterized once again by strong underlying AI momentum. Palantir beat Q3 revenue expectations by more than $21 million, reporting revenue of $725.5 million in the quarter. The FY24 revenue guide was boosted to just above $2.80 billion, up from $2.75 billion last quarter.
Revenue growth continued to accelerate, with Palantir reporting revenue growth of 30.0% in Q3, ahead of its guidance for 25.2% growth and up from 27.2% in Q2.
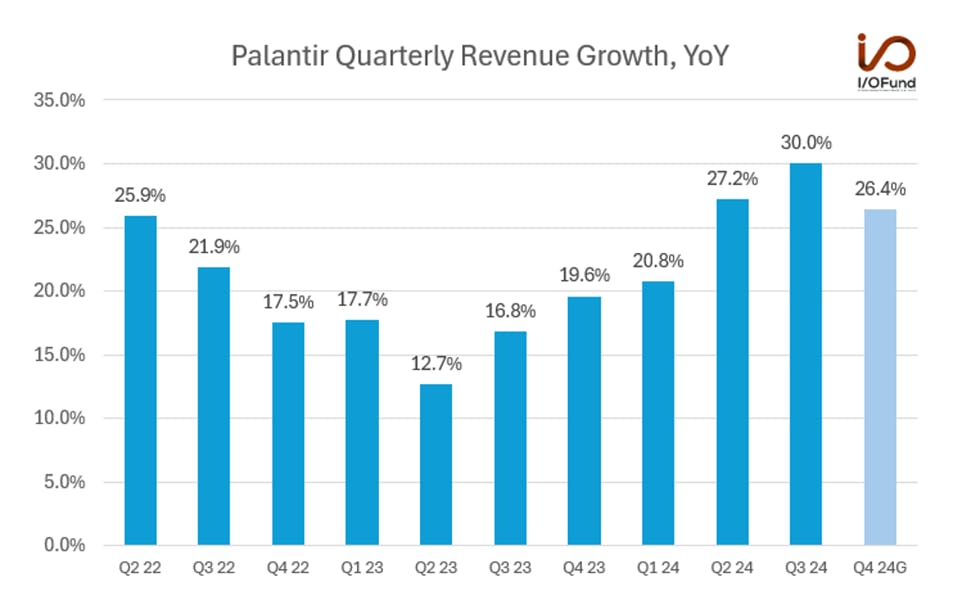
Palantir’s Q3 highlights: Strong AI momentum with $725.5 million revenue, exceeding expectations by $21 million. FY24 revenue guidance increased to over $2.80 billion. Q3 revenue growth at 30.0%, surpassing guidance and Q2’s 27.2% growth rate. - I/O Fund
Q3’s results have marked quite the turnaround in just over a year for Palantir, with revenue growth accelerating more than 17 percentage points from Q2 2023 (AIP’s release) to Q3 2024. This was also the highest revenue growth rate recorded since Q1 2022.
AIP has been the primary driving force of this revenue reacceleration, with strong adoption in the US commercial segment. AIP’s scalability, interoperability and versatility allow it to quickly be integrated by enterprises. Commercial customers can lever Palantir’s AI and machine learning tools to harness the power of the latest large language models (LLMs) within Foundry and Gotham for near-instant analytics & insights, and productivity & efficiency gains.
For a closer look at AIP and how it separates Palantir from the rest of the SaaS universe, read This Stock Is Crushing Salesforce, MongoDB And Snowflake In AI Revenue.This Stock Is Crushing Salesforce, MongoDB And Snowflake In AI Revenue.
AIP Aids US Commercial Growth
What’s interesting to note in Q3 is that government revenue growth outpaced commercial growth, at 33% YoY versus 27% YoY, a contrast to recent quarters where commercial had been the primary driver. Government’s outperformance was driven by 15% QoQ growth in US government revenue, its fastest growth rate in 15 quarters, while commercial was impacted by a 7% QoQ decline in international commercial revenue due to European headwinds and “a step down in revenue from a government sponsored enterprise in the Middle East.”
However, US commercial growth remained strong in the quarter, with a growth rate nearly in line with Q2’s. Management said that AIP drove “new customer conversions and existing customer expansions in the US,” as AI models continue to be deployed into production. Here’s what the growth in US commercial revenue looks like:
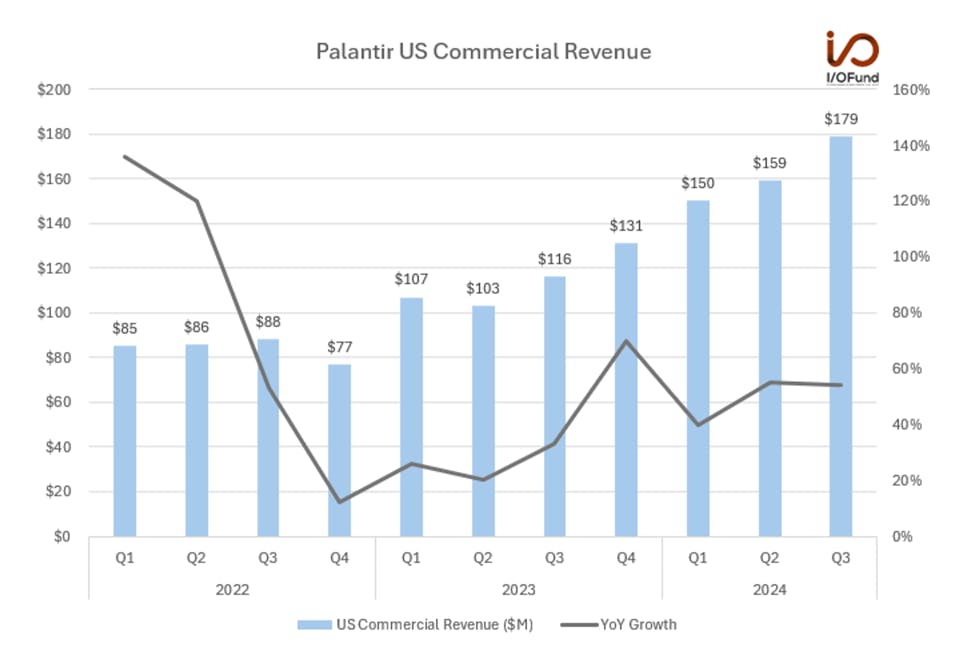
Palantir’s US commercial revenue rose 54% YoY and 13% QoQ to $179 million, slightly decelerating from 55% YoY growth in Q2. FY24 US commercial revenue is expected to exceed $687 million, indicating at least $199 million in Q4 revenue, with ~52% YoY growth. - I/O Fund
US commercial revenue increased 54% YoY and 13% QoQ to $179 million, slightly decelerating from 55% YoY growth in Q2. Palantir guided for US commercial revenue to exceed $687 million, or 50% YoY growth, for FY24, implying Q4 revenue of at least $199 million, or ~52% YoY growth, representing a 2 point deceleration should it meet that target.
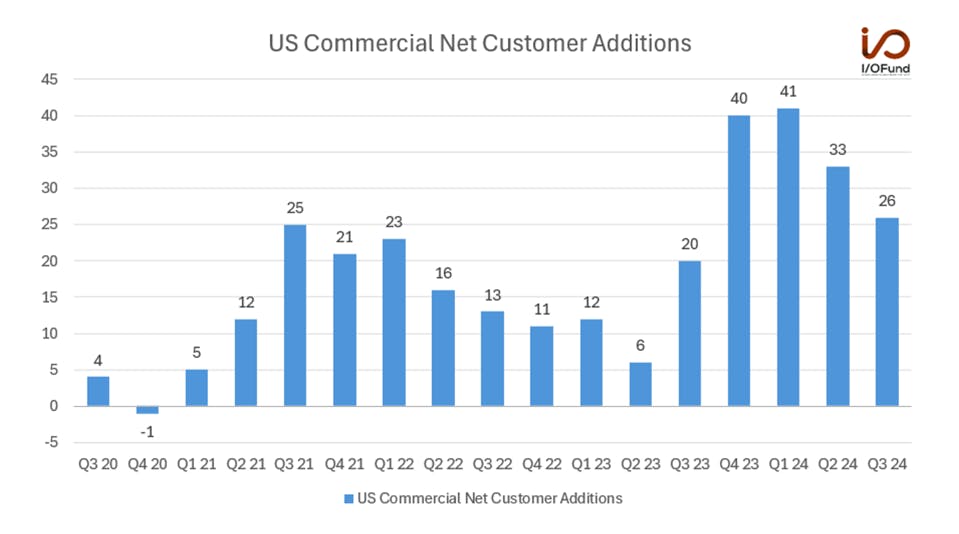
US commercial customer growth remained strong, with customers rising 77% YoY to 321 in Q3. This decelerated from 83% YoY in Q2. Here’s what the US commercial customer growth looks like:
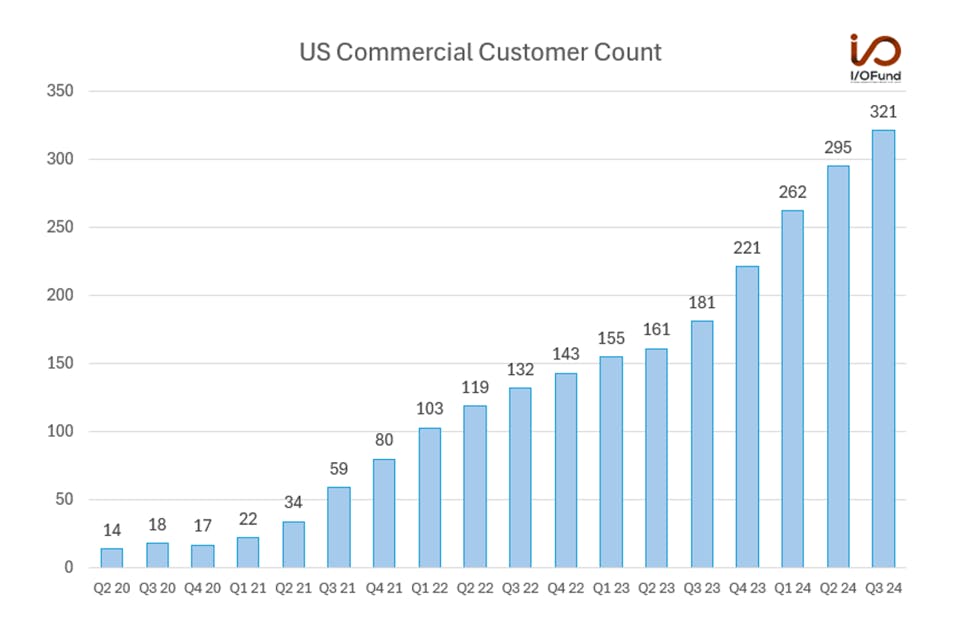
US commercial customer growth remained strong, rising 77% YoY to 321 in Q3, slightly down from 83% YoY growth in Q2. Here’s what the US commercial customer growth looks like. - I/O Fund
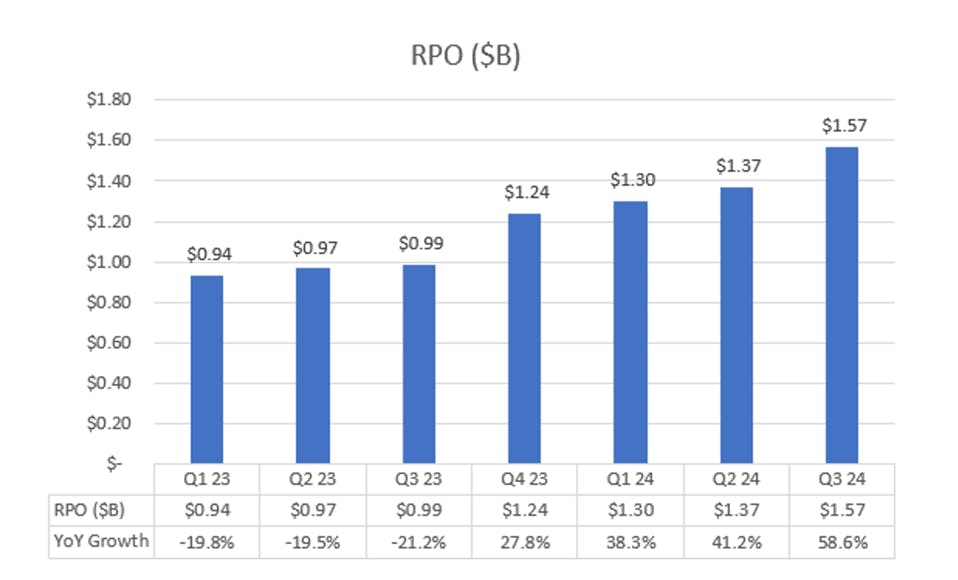
US commercial customer count has essentially doubled since AIP’s release, but Q3 was the second quarter to show slightly slower customer growth, indicating that Palantir may be relying on existing customers to drive revenue, whereas customer acquisition should be monitored moving forward. Most importantly, NRR has risen to a two-year high, while RPO is surging, suggesting customer spend could remain elevated for the next few quarters.
Every Thursday at 4:30 pm Eastern, the I/O Fund team holds a webinar for premium members to discuss how to navigate the broad market, as well as various stock entries and exits. We offer trade alerts plus an automated hedging signal. The I/O Fund team is one of the only audited portfolios available to individual investors. Learn more here.Learn more hereLearn more here.
Net Retention, RPO Strong, but Watch US Net New Adds
In Q3, net dollar retention expanded to 118%, up from 114% in Q2, 111% in Q1, and 107% a year ago. Management said that this “increase was driven both by expansions at existing customers and new customers acquired in Q3 of last year, as we see the effect of the AI revolution in both industry and government.” Net dollar retention has reached the highest level in two years, but still has room to expand, given that rates were >120% in 2021 and 2022.
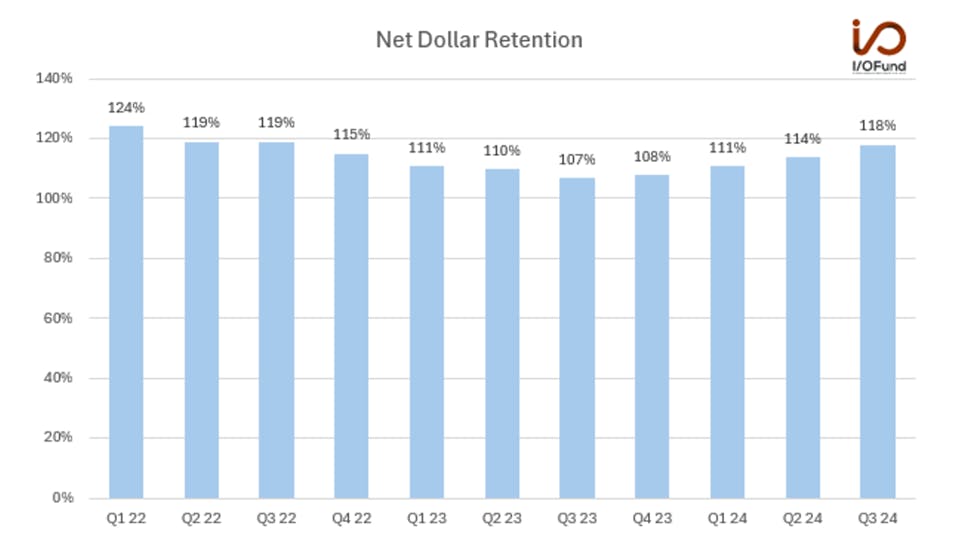
In Q3, Palantir’s net dollar retention rate increased to 118%, up from 114% in Q2 and 107% a year ago. This growth was driven by expansions at existing customers and new acquisitions, reflecting the impact of the AI revolution in both industry and government. Net dollar retention reached its highest level in two years, with further growth potential, previously exceeding 120% in 2021 and 2022. - I/O Fund
Palantir has an advantage over other software peers due to its differentiated AI offerings, while adding significant new customers this year and expanding deal sizes with new customers (with FY24’s additions not appearing until FY25) — this provides a path forward for NRR to continue expanding. Initial AIP customers are beginning to appear in NRR, and a few more quarters will provide a clearer picture of how far NRR could expand and at what level it will plateau.
RPO is also sharply rising, implying that customer spend is likely to remain strong over the next few quarters. RPO growth has accelerated over the past four quarters, from 27.8% in Q4, breaking a string of declines in the rest of 2023, to 58.6% YoY by Q3. This is the highest RPO and growth rate since the I/O Fund began tracking Palantir in late 2023, and another data point underlying its AI-driven momentum.