
This article was originally published on Forbes on Apr 28, 2023,07:15am EDTForbes Forbes on Apr 28, 2023,07:15am EDT
In April of 2022, Netflix surprised the markets by reporting its first subscriber loss in nearly 10 years. The stock tumbled 35% the following day, as investors panicked. Famed hedge fund manager, Bill Ackman, immediately sold his entire stake in Netflix for a $400 million loss, only after holding it for just over three months.
Last April was a tough month for Netflix stock, yet fast forward — and in one brief year, Netflix is up 41% from where Ackman sold the stock and is up 84% since the low on May 12.
In our free newsletter published on Forbes, we argued that “the day that Netflix’s stock price dropped 35% was consequently one of the most important days in the company’s history in terms of its chances for a boost in revenue and a renewed uptrend. Patience, though, will be required, as Netflix has work to do.”
On the very day that Netflix lost one-third of its value last year, management announced its intention to cutoff password sharing and rollout a new ad tier. We deemed the stock a buy and executed in August and again in early September.
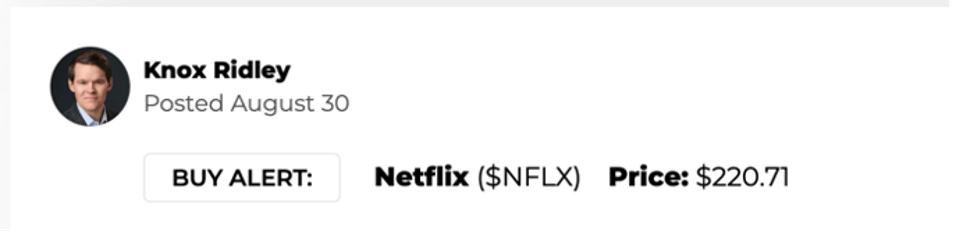
Source: I/O FUND
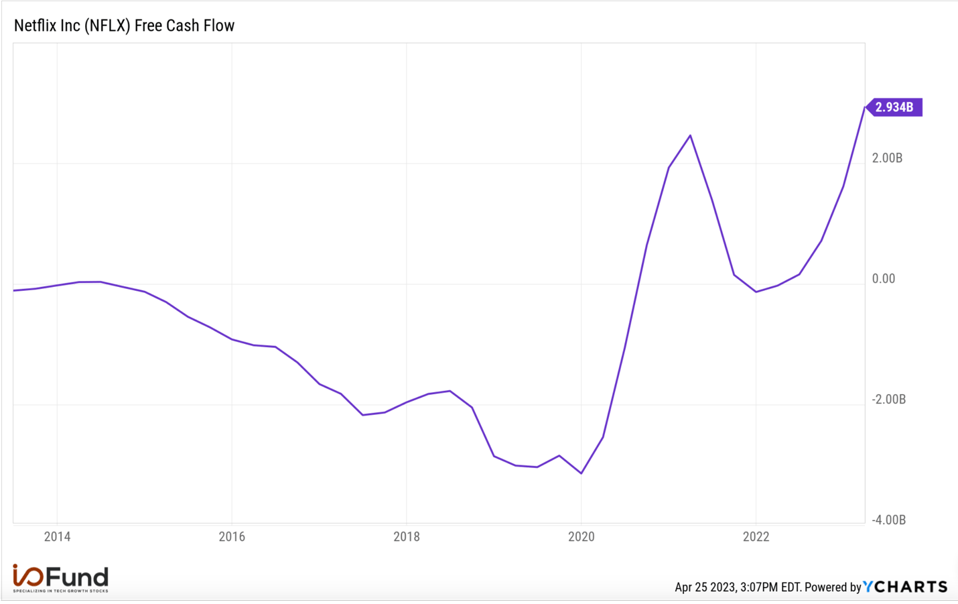
What will make or break Netflix’s price action will be next quarter’s earnings report as there will be one full quarter of the results from cutting off password sharing. The bottom line is surprisingly stable for this company and what the market will want to see is top line impact from the two pivots announced a year ago.
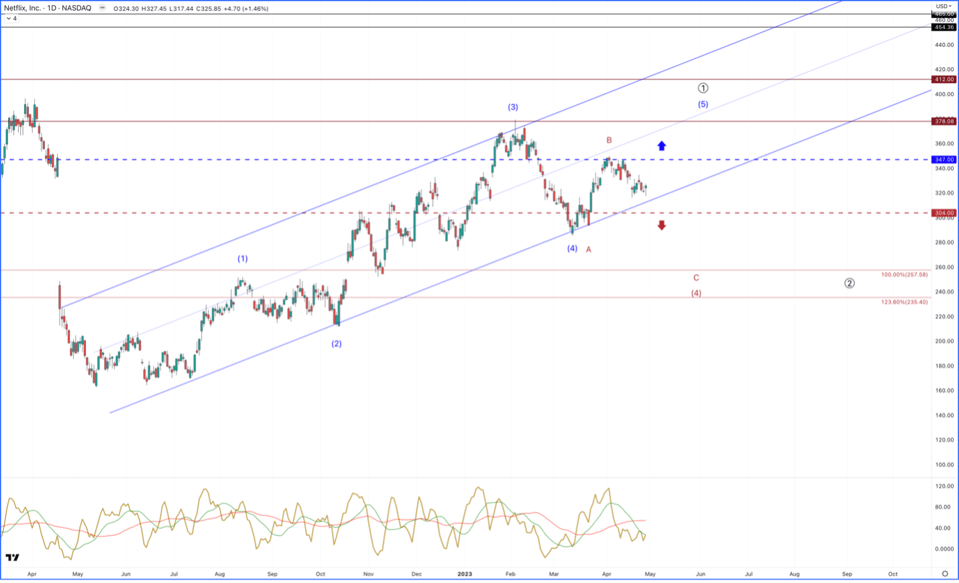
Currently, our technical analysis points toward May 12th being the bottom for the stock. In other words, we do not believe the stock will dip below $200 before the macro environment clears up. This is rare, as our analysis points toward a few FAANGs retracing their lows in the coming quarters.
Although our firm is long-term bullish on the stock, we don’t believe now is the time to build a long-term position. Instead, we plan to further trim our position and build at lower levels. More details are below.
Sign up for I/O Fund's free newsletter with gains of up to 221% - Click hereClick hereClick here
The Pivot of a Quarter-Century
At the same time that Netflix lost its growth status, the company made the biggest announcement in its history – which was to cutoff password sharing for 100 million users and to roll-out an ad tier that will monetize higher than the Basic and Standard subscription plans.
One could argue that moving from DVDs to over-the-top (OTT) was the biggest announcement in the company’s history, yet at the time Netflix had nothing to lose. Today, the company is the top streaming service in the world and has held this top position despite media titan Disney’s attempt to reclaim the media throne. In other words, Netflix’s two pivots are high stakes. The good news is, investors won’t have to wait too much longer to find out if the pivots are successful.
Password Sharing:
In the most recent quarter, global paid adds of 1.75M came in slightly shy of analyst estimates of 1.8M.
For password sharing, the Latin America region was a test region and the Q1 results provided some clues as to how a broader rollout will perform. According to management there was a cancel reaction which later eased. The region reported a loss of net adds of (0.4M) compared to net adds of 1.76M in Latin American last quarter, yet the revenue was up 7% YoY (+13% on constant currency basis).
The company stated that other regions, such as Canada, were “directionally consistent with what we saw in Latin America.”
There was a similar pattern in the United States Canada (UCAN) region where there was low net adds yet higher revenue growth. The region reported 0.1 net additions with revenue up 8% YoY.
In the year ago quarter, these regions were flat or reported a decline. Notably, churn can be higher coming out of Q4 for Netflix since that quarter has high net adds.
Another observation is that LatAm and UCAN both had expanding ARM, or average revenue per membership, whereas the other two regions saw a lower ARM. This could be encouraging in terms of a broader rollout on password sharing driving more top line growth in the second half of the year.
- UCAN up +9% from $14.91 to $16.18
- LatAm up +3% from $8.37 to $8.60
- EMEA down (6%) at $10.89 this quarter compared to $11.56 in the year ago quarter
- APAC down (13%) at $8.03 this quarter compared to $9.21 a year ago
Notably, average paid membership increased in APAC, and was up 17%. This is clearly a large region but there’s been some attention on India specifically where Netflix has lowered prices. This would make sense to where net adds increased but ARM decreased.
The I/O Fund has launched a new $99/year Premium Newsletter called "Essentials" -- this newsletter delivers premium samples for our readers who want more actionable analysis for their tech portfolios. This month, we released a stock pick that we believe will be a leader in 2023 plus a video with the buy plan.$99/year Premium Newsletter $99/year Premium Newsletter called "Essentials" -- this newsletter delivers premium samples for our readers who want more actionable analysis for their tech portfolios. This month, we released a stock pick that we believe will be a leader in 2023 plus a video with the buy planbuy plan.
Advertising Tier
Upfront season is coming for Netflix, which means Netflix will likely have to state the company’s expected scale for the ad tier come Q3/Q4. Right now, the company is not guiding for this but analysts believe it will be in the 13M range.
Per Forbes and Bloomberg: “After a slow start Netflix ad tier has been gaining traction with U.S. subscribers. After analyzing their internal data, BloombergBloomberg reported in its first two months, Netflix had one million active users. Before its launch, Netflix had projected 1.1 million by year end 2022 increasing to 13.3 million by the third quarter 2023. Industry analysts project Netflix could eventually wind up with 30 million U.S. subscribers on its ad supported tier. The U.S. is one of the 12 markets where Netflix is now selling ads. At its most recent earnings report Netflix had 74 million total U.S. subscribers with 231 million worldwide.”