This article was originally published on Forbes on Apr 30, 2020,01:41am EDTForbes on Apr 30, 2020,01:41am EDT
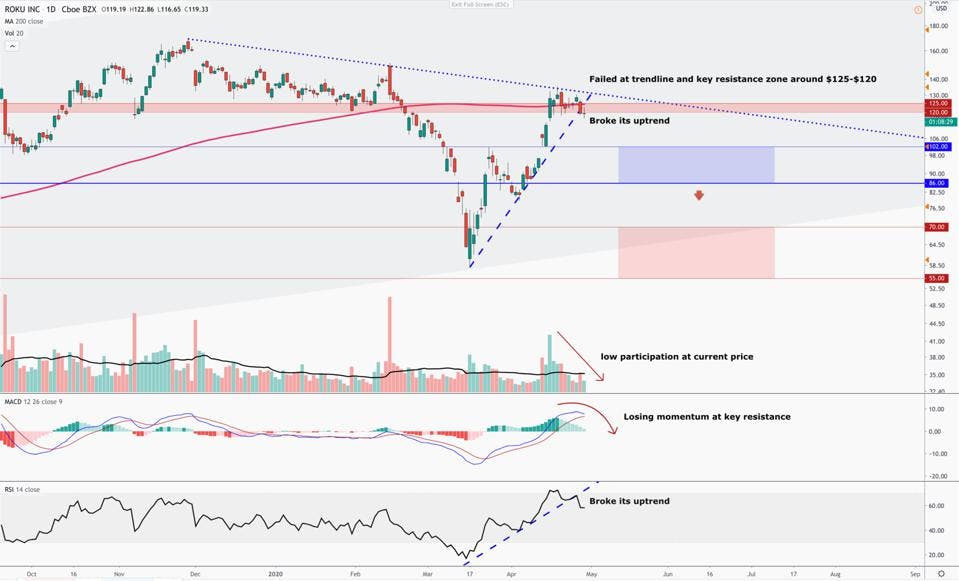
Roku has gained up to 600% in less than 3 years since its IPO despite having many objectors along the way. In light of these sizable gains, Roku has seen five significant drawdowns ranging between 41% to 67%. Therefore, when considering if Roku will go boom or bust this year, I believe it will do both.
When I first began bullish coverage on Roku at $30, the company had a misunderstood business model. At the time I pointed out that Roku was an ad platform first and a hardware player second. At the time, the market was backwards-looking as Roku’s device sales made up 59% of total revenue in the six months leading up to its public offering.
Through 2019, its device sales made up only 34% of its revenue, while the remaining majority came from its platform. What investors initially failed to realize was that the hardware player was a means to its high-yielding ad platform. Roku has an added advantage from the data it has on consumers due to owning the hardware and the many content apps that need access to an OTT device.
With this history, my guess is investors will get Roku’s story wrong again this year as Roku must chose between its top line and bottom line. Covid-19 offers an important opportunity for Roku as OTT usage is skyrocketing and the company must expand globally for long-term growth. (I’ve covered extensively why the domestic market is no longer pertinent in my Netflix coverage).
Often times, growth and earnings are at odds with one another as revenue requires sales and marketing (or other investments), which ultimately eat at the bottom line. Or, in Netflix’s case, revenue growth and free cash flow are at odds. Conceptually, most investors know there is a cost to hyper growth, but in practice, it’s hard to see one of your portfolio companies miss those magical analyst estimates.
Despite monetizing through ads rather than subscriptions, Roku’s best role model for becoming a global media company is Netflix. What Netflix has done beautifully is ignore the pressures that comes with being a public company in favor of being a hyper growth company. This included taking on debt and other risks to gain ground. While I’m not suggesting Roku should take on the debt levels that Netflix has, it wouldn’t hurt for Roku to do whatever it takes to solidify itself as the leading global AVOD channel and ad platform this year.
International Expansion
Roku predicts that by 2024 roughly half of all U.S. TV households will have cut the cord or never had traditional pay TV.
Earlier this year, Roku began its expansion into emerging markets by entering Brazil. Strategically, Roku has partnered with the electronics company AOC to launch AOC Roku TV. The AOC TV/Roku platform will feature popular local content from Globoplay. With over 5,000 channels and over 1,000 free channels, Roku should do well in emerging markets. (I’ve also covered this in detail in a previous analysis.)
Furthermore, Roku has announced fifteen TV brands that come integrated with the Roku platform models. These models are available not only in the U.S., but also in the UK, Canada, and Mexico as of 2020. This kind of strategic partnership with TV models will help the company scale globally, which is a critical next step for Roku.
Pandemic Outlook
Roku recently stated that its commission revenue is expected to jump as viewing hours have increased due to COVID-19. However, it will still feel the shock of ad demand drying up.