
This article was originally published on Forbes on Jul 11, 2024,09:48pm EDTForbes Forbes on Jul 11, 2024,09:48pm EDT
After months of being the lowest performing Mag 7 stocks, Tesla saw rapid gains — up 42% in a one month rally, with 37% of those gains in eight sessions — after it reported Q2 deliveries ahead of expectations and a surge in energy storage deployments.
Optimism had also been building for its much-anticipated robotaxi reveal on August 8, but that now has reportedly been pushed back until October. Despite the surge in share price and renewed deliveries growth in Q2 relative to Q1, Tesla still is facing an EV demand problem with production and deliveries set to decline in 2024. Investors are hoping Tesla is at a meaningful bottom, yet that will require significant growth in the back half of the year.
Production & Deliveries Decline
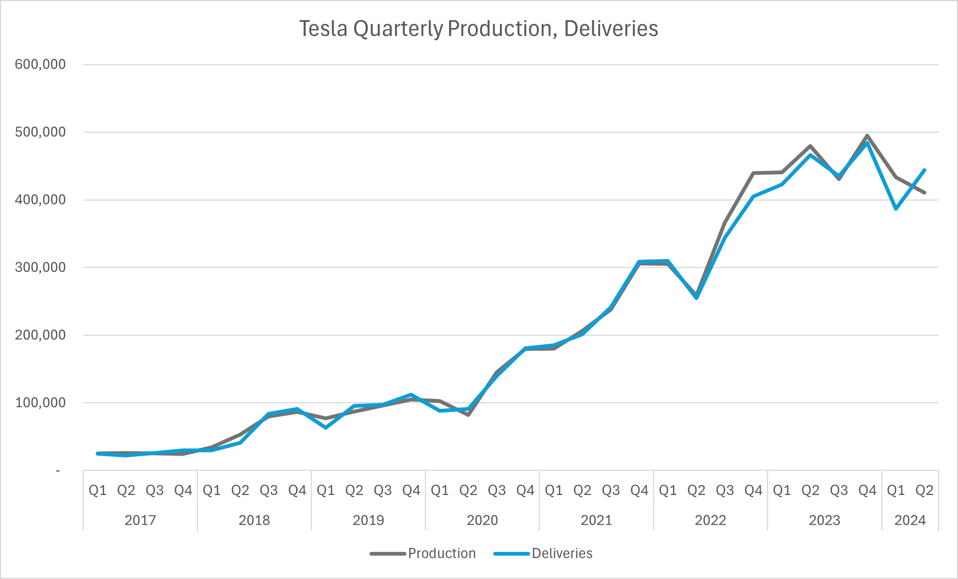
Tesla delivered 443,956 EVs in Q2, about 1% more than consensus for 439,302 deliveries. Despite rebounding to a 57,000 QoQ increase from Q1, Q2 notched a second straight YoY decline, at (4.8%), though this was an improvement from Q1’s (8.5%) YoY drop.
Production fell to the lowest level in seven quarters, falling to 410,831 vehicles – this represented a (5.2%) QoQ and (14.4%) YoY decline in production. This follows production issues the EV maker faced in Q1, primarily impacts to ramping up the refreshed Model 3 in Fremont, and more recent issues with lowered Model Y production in China and five days of production pauses in Germany in June.
Source: I/O Fund
While the QoQ increase in deliveries was a positive sign to see after Q1’s sharp sequential decline, production and deliveries are both peaking in the short term on a TTM basis. Both have pulled back below the 1.8 million mark in Q2 – production totaled 1.769 million vehicles, with deliveries at 1.75 million vehicles. This comes after Tesla warned in Q1 that 2024’s “vehicle volume growth rate may be notably lower than the growth rate achieved in 2023.” At the moment, we’re tracking for a (3%) to (4%) decline.
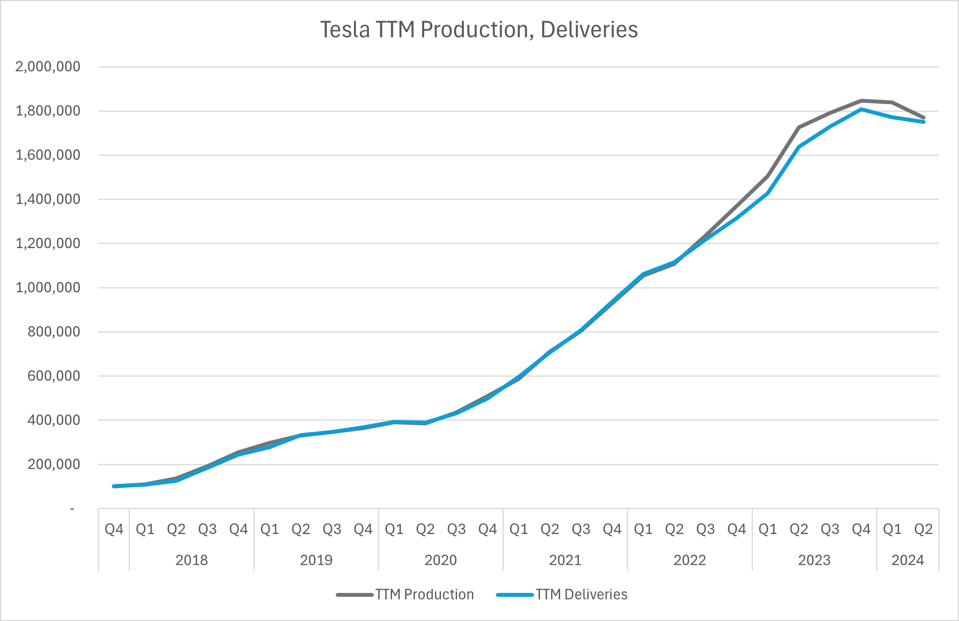
Production and deliveries both declined below 1.8 million on a TTM basis.
Source: I/O Fund
Q2’s deliveries point to inventory reduction/channel clearing efforts. Q1 had excess inventory of more than 46,000 vehicles, and thus Tesla had lowered production for this excess to be absorbed in Q2.
In Q1, Tesla noted that it began lowering vehicle and subscription prices, and offering leasing and financing deals to help boost demand, and its TTM trend seems to confirm that weaker demand from Q1 is persisting through to Q2. The industry backdrop in the US remains challenged, as EV demand “has grown more slowly than expected due to high borrowing costs, economic uncertainty and consumer preference for gasoline-electric hybrids.”
To ease these fears, Tesla would need to report strong sequential growth in Q3 and Q4, for both production and deliveries. Assuming 5% QoQ growth in production in Q3 and 7% QoQ growth in Q4, for volumes of ~431,370 and 461,570 respectively, and 2% residual inventory in each quarter, Tesla would end the year at 1.737 million vehicles produced and 1.705 million delivered. This would mark a nearly (6%) YoY decline.
Every Thursday at 4:30 pm Eastern, the I/O Fund team holds a webinar for premium members to discuss how to navigate the broad market, as well as various stock entries and exits. We offer trade alerts plus an automated hedging signal. The I/O Fund team is one of the only audited portfolios available to individual investors. Learn more here.Learn more here.
China Deliveries, Market Share Slip
Tesla continues to face major headwinds in China, with China-made deliveries declining on a YoY basis for a third consecutive month in June. We noted to our free readers in November and December 2023 that primary rival BYD’s strong growth presented a tangible and challenging headwind for Tesla in that nation.
Now, we’re seeing more evidence that Tesla’s growth challenges are unique for China. Tesla’s China-made deliveries totaled 71,007 vehicles in June, a 2.2% MoM decline and a 24.2% YoY decline. Stripping out exported vehicles, local deliveries were 59,261, down nearly (20%) YoY but up 7.3% from 55,215 deliveries in May.
BYD outsold Tesla more than 2-to-1 in June, delivering 145,179 BEVs in the month, up 13.2% YoY. Smaller EV rivals Nio and Zeekr also saw strong deliveries, posting record high tallies for June. Industry-wide growth was strong, with NEV sales projected to rise 8% MoM and 28% YoY to 970,000 vehicles. Tesla’s market share dropped below 7% in June, down from more than 11% a year ago as industry growth remains strong and as BYD continues to outsell Tesla significantly in China.
Tesla has an easy comp for July, where China-made deliveries were 64,285 vehicles, including exports. It’s imperative that Tesla break this string of declines in one of its core automotive markets as it heads into Q3. China-made sales were 205,747 vehicles in Q2, or more than 46% of total deliveries.
Energy Storage a Bright Spot, But EPS Impact Likely to be Minimal
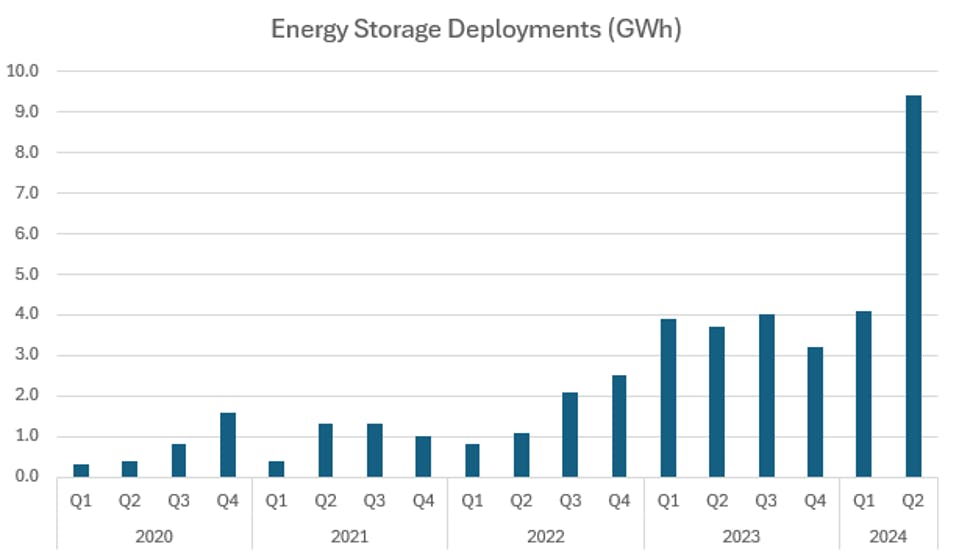
Energy storage was a bright spot in Q2, with Tesla reporting a record 9.4 GWh in deployments, up more than 129% QoQ and 154% YoY. Q2’s deployments exceeded historical levels at 4 GWh per quarter, at a maximum.
Source: I/O Fund
This strong growth in deployments should help the segment contribute more to both revenue and gross profit, as its contribution to gross profit has increased significantly through 2023 and 2024. Energy storage contributed less than 8% of revenue in Q1, but could contribute 14% or more of total revenue assuming revenue more than doubles sequentially.