This article was originally published on Forbes on Feb 23, 2024,04:41 pm ESTForbes Forbes on Feb 23, 2024,04:41 pm EST
In August of 2021, my firm made a very bold prediction that Nvidia will surpass Apple in valuation. At the time, Nvidia was at a market cap of $550 billion compared to Apple’s $2.5 trillion market cap. In the Forbes editorial “Here’s Why Nvidia Will Surpass Apple in 5 Years” I wrote the following:
“Notably, the stock is up 335% since my thesis was first published [my first AI thesis in 2018]AI thesis in 2018]
– a notable amount for a mega cap stock and nearly 2-3X more returns than any FAAMG in the same period.This is important because I expect this trend to continue until Nvidia has surpassed all FAAMG valuations.” published August 2021This is important because I expect this trend to continue until Nvidia has surpassed all FAAMG valuations.” published August 2021
Today, Nvidia surpassed a $2 trillion market cap compared to Apple’s $2.8 trillion. The company has surpassed Amazon, Google, Tesla, Meta and Netflix. The only one left standing is Apple and we have 2.5 years left to make good on my prediction.
Notice I did not say at the time that Nvidia would double its market cap to $1 trillion or surpass one of the FAANGs. Instead, I predicted that Nvidia would surpass the world’s most valuable company to take the throne, and would do it very quicklyvery quickly.
Here’s what Nvidia’s increase in market cap looks like:
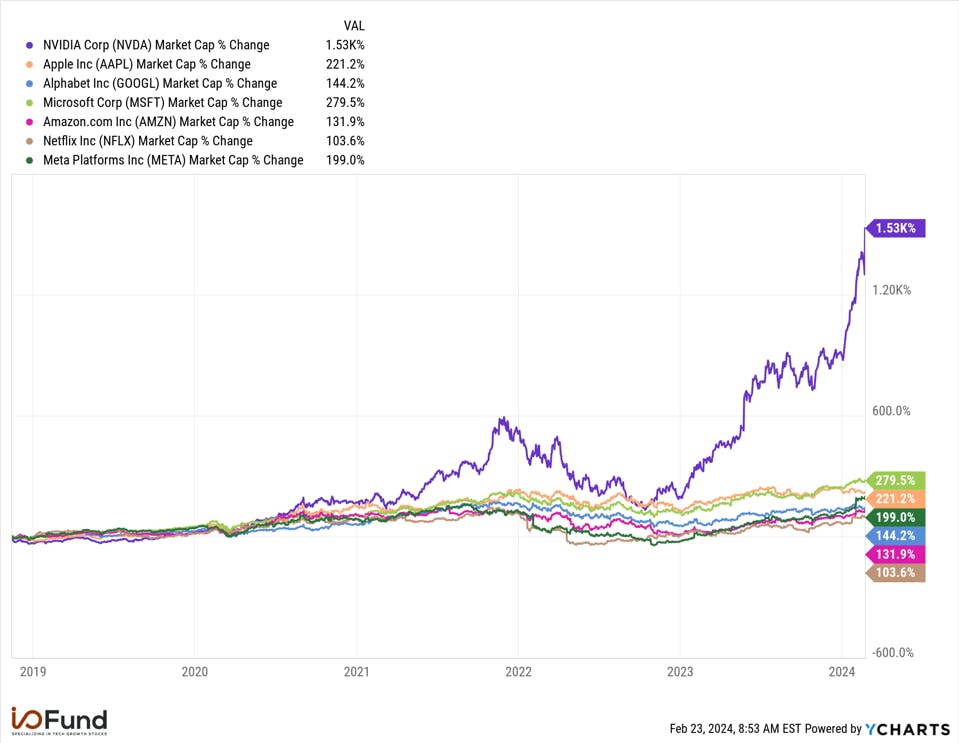
Since November 2018, Nvidia's market cap has increased more than 1,500%, compared to the FAANG's gaining 100% to 280%. Source: YCHARTS
Sign up for I/O Fund's free newsletter with gains of up to 221% - Click hereClick hereClick here
How Nvidia Surpassed Many FAANGs — and why Apple is Next
Nvidia’s rapid rise to become one of the top five most valuable companies in the world stems from its leadership position at the forefront of AI —- which began with the A100. It was the A100 which combined training and inference that kicked off Nvidia’s strength in the data center –the H100 would come a couple of years later. The A100 left early breadcrumbs that Nvidia would see a glorious ascent to overtake Apple. Prior to the A100, there were additional clues, specifically Nvidia’s CUDA software platform, which my firm also made quite clear in 2018 would carve a deep moat for a near-monopoly.
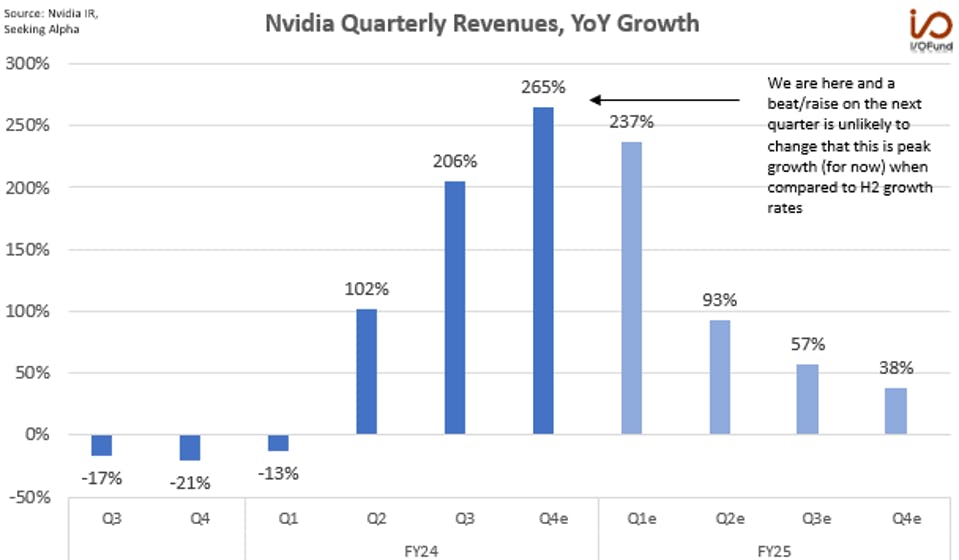
Rapid top-line growth is the primary eye-catching statistic, as no other companies in tech have reported such blistering revenue growth at a rate above 200% for multiple quarters at an annualized revenue rate near $90 billion. These are growth rates we see in small caps or mid-caps that have a mere $1 billion or less in revenue. Rarely, if ever, do we see this growth rate above $5 billion in revenue let alone $90 billion.
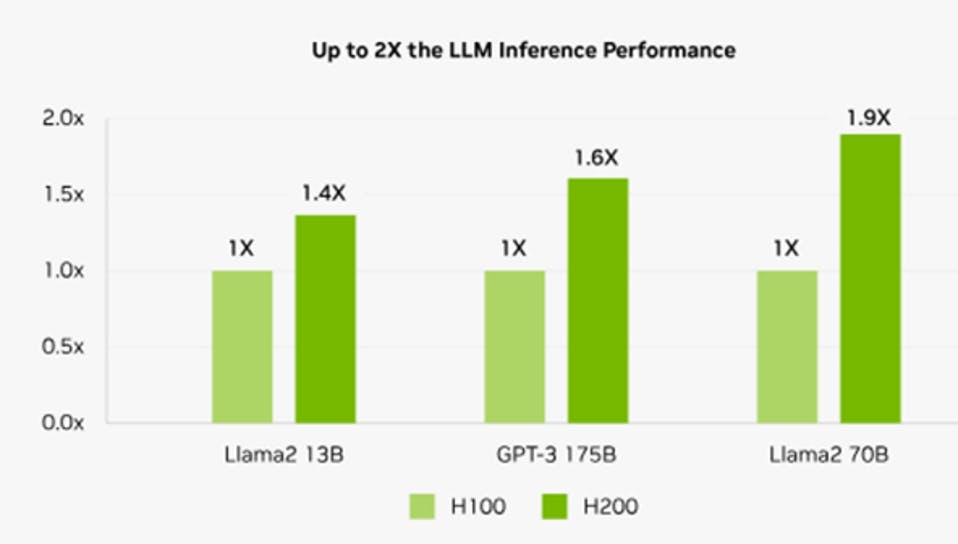
The consistency and magnitude of the top-line beats is impressive, however, it’s the growth further down the income statement where Nvidia’s report truly shines. Nvidia’s stronghold grip on the data center market at the moment combined with pricing power and elevated demand for its H100 GPU has allowed substantial growth in operating income and has generated robust earnings.
Let’s take a closer look as to why Nvidia has been able to surpass every FAANG except Apple, and why it’s inevitable that Nvidia becomes the World’s Most Valuable company in the next 2.5 years. We are using the date of August 2021 through the Q4 January report to evaluate the fundamental growth since that is when we first predicted Nvidia would surpass Apple’s valuation by August of 2026.
Here are some staggering data points since that prediction:
Nvidia’s Data Center:
- Data center revenue has grown more than 676%, from $2.37 billion in fiscal Q2 2022 to $18.40 billion in fiscal Q4 2024.
- In just 10 quarters, Nvidia has taken the data center from a less than $10 billion annualized run rate to almost a $75 billion annualized run rate – no other company can boast growth at this scale. For context, Amazon’s AWS increased from a $12 billion annualized rate to $35 billion over 12 quarters from 2016 to 2019, but took six years to surpass $80 billion in 2022. Nvidia did the equivalent in 2.5 years.Nvidia did the equivalent in 2.5 years.
- Data center revenues in Q4 accelerated again, growing 409% YoY compared to 279% YoY in Q3 and 171% YoY in Q1. Nvidia attributed Q4’s growth to “higher shipments of the NVIDIA Hopper GPU computing platform” alongside strong demand for InfiniBand which was up 5-fold.
To put in perspective just how rapid this ascent in data center revenues has been, this year’s $47.5 billion in revenue is 18% more than total revenues in the segment for the past five years combinedfor the past five years combined. Nvidia generated a total of $40.2 billion in data center revenue between CY17 through CY22.
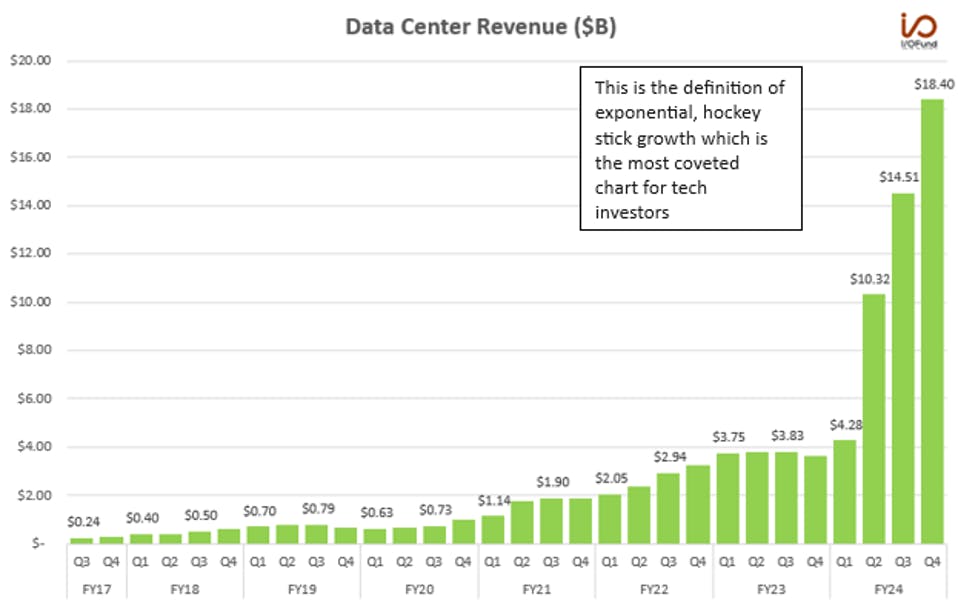
Nvidia's data center revenue increased 409% YoY to $18.40 billion in Q4, compared to $2.37 billion in August 2021. Source: NVIDIA
Compare this to Apple’s prized iPhone segment since our prediction:
- iPhone revenue increased 79% from $38.8 billion in fiscal Q4 2021 to $69.7 billion in fiscal Q1 2024; however, iPhone sales have increased just 12.7% to $43.8 billion in Q4 2023.
- iPhone revenue increased just 4.5% from fiscal 2021 through fiscal 2023, from almost $192 billion to $200 billion, as growth has stagnated.
Every Thursday at 4:30 pm Eastern, the I/O Fund team holds a webinar for premium members to discuss how to navigate the broad market, as well as various stock entries and exits. We offer trade alerts plus an automated hedging signal. The I/O Fund team is one of the only audited portfolios available to individual investors. Learn more here.Learn more hereLearn more here.
Overall Revenue Growth for Nvidia of 240% Compared to Apple’s 43%:
Since August 2021, Nvidia’s revenue has grown at a much quicker rate than Apple, at a 240% total increase compared to 43% for Apple. That’s 96% growth on average for Nvidia per year and 17% growth for Apple averaged out per year – a 5.5X difference.
The iPhone’s installed base is reaching 1.5 billion and the market is showing signs of saturation. Growth stems primarily from existing devices being upgraded rather than building out the ecosystem. For data centers, we’re in the very early stages of growth, with Nvidia’s CEO Jensen Huang predicting that $1 trillion will be spent across the next four years to upgrade data centers for AI, with a majority of this spend stemming from hyperscalers and cloud providers procuring GPUs.
This massive capital spending on data centers is what will help Nvidia hammer the nail in the coffin to overtake Apple, as it will continue to drive significant growth in Nvidia’s data center revenues and thus overall revenue.
Q1’s revenue guide of $24 billion implies YoY growth of 235%, and suggests data center revenue may surpass $20 billion next quarter, for another blazing hot quarter with DC growth of 367% YoY.
Looking forward through the rest of FY25, estimates on the Street for data center revenue range from $22.8 billion to $36.4 billion by fiscal Q4 2025, with total revenue ranging between $25.7 billion to $40.3 billion.
Should Nvidia reach $29 billion in overall revenue by next January with $25 billion in data center, its data center revenue will have grown more than 950% since August 2021 with total revenue up nearly 350%. Compare this to Apple, where revenues are expected to decline (4.1%) YoY next quarter and increase just over 1% for fiscal 2024.
Nvidia has Strong Margins, But Apple Has the Cash
Nvidia’s margins are much stronger than Apple’s, but Apple leads in cash and cash generation.
Since August 2021, Nvidia’s gross margin has expanded significantly, from 66.7% to 76.7% in fiscal Q4, first topping 70% in fiscal Q2 and expanding since then as a high degree of pricing power for its ultra popular H100 GPUs is aiding margin growth.
Apple has similarly seen gross margin expansion, stemming primarily from growth in high-margin Services revenue as opposed to hardware sales — Apple’s gross margin increased from 42.2% to 45.8% over the same period.
Nvidia’s operating margin has improved tremendously in fiscal 2024, as it managed to increase operating expenses by only 2% YoY while driving a 126% increase in revenue. Operating margin has increased from 47.2% to 66.7% since our prediction. Over the past two quarters, operating margin has increased 910 bp.
On the other hand, Apple’s operating margin has improved 520 bp over the same period, from 28.5% to 33.7% — Nvidia’s operating margin is now nearly double Apple’s.
Because of this major increase in operating leverage, Nvidia has seen substantial growth in EPS. Nvidia reported $5.16 in EPS in fiscal Q4, nearly 400% growth from $1.04 reported in August 2021. Apple’s earnings growth over the same period has been just 14%, from $5.62 to $6.42 on a TTM basis.
However, Apple has the cash and cash flows, though Nvidia is quickly improving in both metrics. Apple’s cash on hand totals $172.6 billion, with over $72 billion in current cash, equivalents and marketable securities.
Nvidia has just $26 billion in cash and equivalents, an increase from $18.3 billion in Q3 and $13.3 billion in the year ago quarter as Nvidia is pocketing more cash.
Apple leads the Mag 7 and tech in general as it generates the highest levels of operating cash flow and free cash flow. TTM operating cash flow was more than $116 billion, while FCF was more than $106 billion, or a FCF margin of 27.5%.