
This article was originally published on Forbes on Aug 10, 2023,07:15 am EDTForbes Forbes on Aug 10, 2023,07:15 am EDT
Given the macro headwinds, not many investors expected the magnitude of the Nasdaq-100’s rally through the first six months of 2023. Going into this year, we were positioned for bottom-line focused investment themes that we felt would be able to deliver earnings growth due to secular demand for its products, and in some cases, be able to reduce costs to maintain profitability.
Big Tech versus Tech Sector earnings
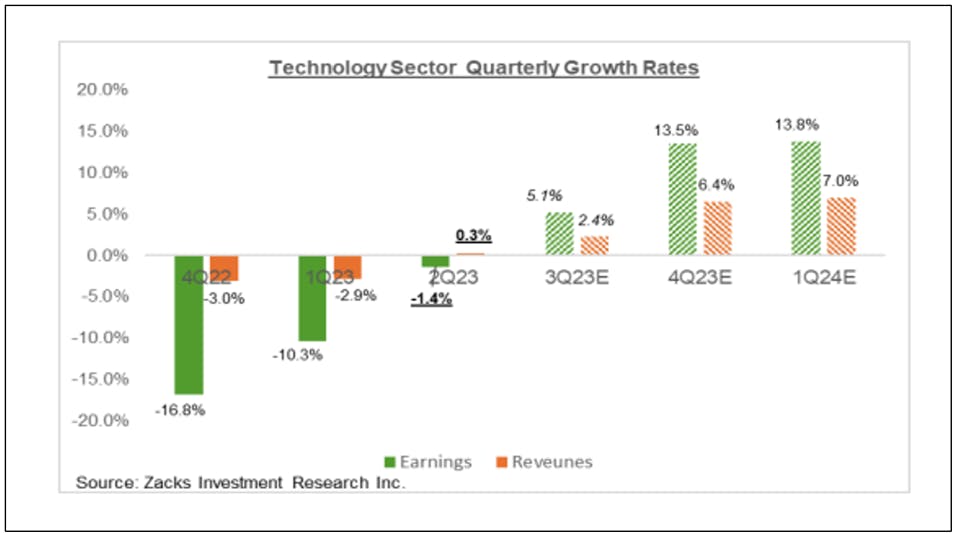
Below is an analysis of consensus earnings estimates from Zack’s on Q2 Technology Sector earnings trends through July 26 plus expectations for the next three calendar quarters.
For the past three quarters, sales and earnings have declined on a year-over-year basis. However, there appears to be stabilization as year-over-year comps get easier and the market is estimating a modest resumption of growth in Q3 and an acceleration in Q4 to Q124.
Meanwhile, Zack’s looked at the earnings picture for the “Big 7 Tech Players” - Microsoft, Alphabet, Meta, Nvidia, Apple, Tesla and Amazon. The earnings profile for the Big 7 is estimated to be more robust compared to the overall technology sector.
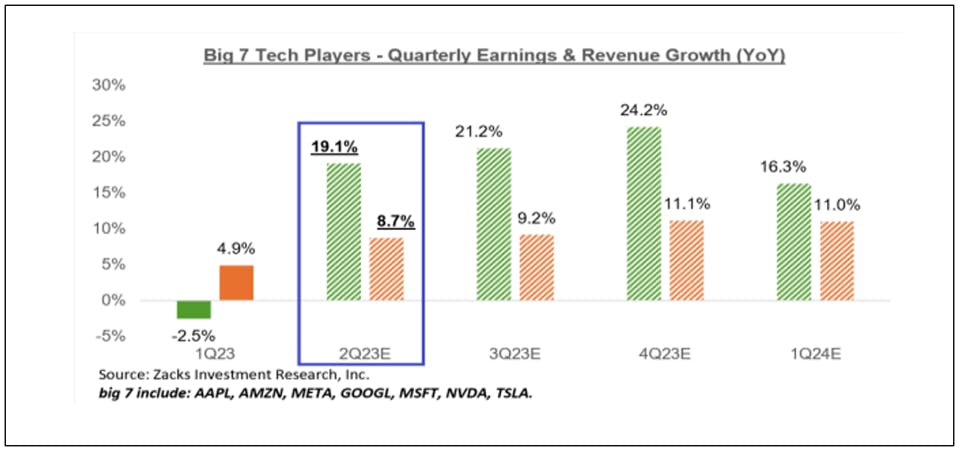
In addition to a better earnings profile, Big Tech prices and valuations have benefited from other factors that investors are seeking
- Focus on their AI capability and having the financial resources to make the required investments so that they make a positive contribution to future earnings.
- Company size (i.e. large cap) and the ability to manage margins in the face of macro headwinds by meaningfully reducing costs but not at the expense of critical high ROI investments.
- Credit quality - following Fitch Ratings’ downgrade of U.S. government debt to AA+. Big Tech Credit worthiness is on par if not greater than US debt. For example, Alphabet has the same AA+ rating.
Amongst the Big 7, we believe Alphabet stands out for several reasons:
Sign up for I/O Fund's free newsletter with gains of up to 221% - Click hereClick hereClick here
Year of Execution - Alphabet
Beginning in mid-2022, IO Fund began to transition allocation toward larger cap tech stocks because we felt they are in a better position to navigate a macro downturn. Big Tech has levers at its disposal to manage its margins by rightsizing its cost base. Importantly, at the same time they have the financial strength to make the investments required to capitalize on the AI opportunity and take market share from its weaker competitors. The medium-term bull case is that once revenue begins to meaningfully reaccelerate helped by its AI offerings, the combination of optimizing its cost structure and efficiencies garnered from technology investments leads to expanding margins. This is similar to Meta and its “Year of Efficiency”.
At the moment we prefer Alphabet (GOOGL) over Meta (META). We see a similar story playing out for Alphabet and its “Year of Execution”. We believe it’s in an earlier stage than Meta in its self-help process and its core business areas are just now showing signs of stabilization. Alphabet’s margins are beginning to rebound and have now returned to the percentage they were at in Q1 2022. Meanwhile 1) Resilience in Search, 2) stabilization in YouTube Ads, 3) Market share and profitability gains in Cloud and 4) Growth in Other Google (i.e. YouTube subscription) make us optimistic that revenue will accelerate and there is upside to margins for the remainder of the year.


