
This article was originally published on Forbes on Dec 14, 2023,10:42pm ESTForbes Forbes on Dec 14, 2023,10:42pm EST
Cloud stocks have been a mixed bag for investors heading into the end of the year, as a handful of names — Confluent, Sprinklr, HashiCorp, Bill, Paycom — plunged following their earnings reports with growth set to slow, while others — Datadog, Elastic, Salesforce – soared on renewed optimism about AI prospects.
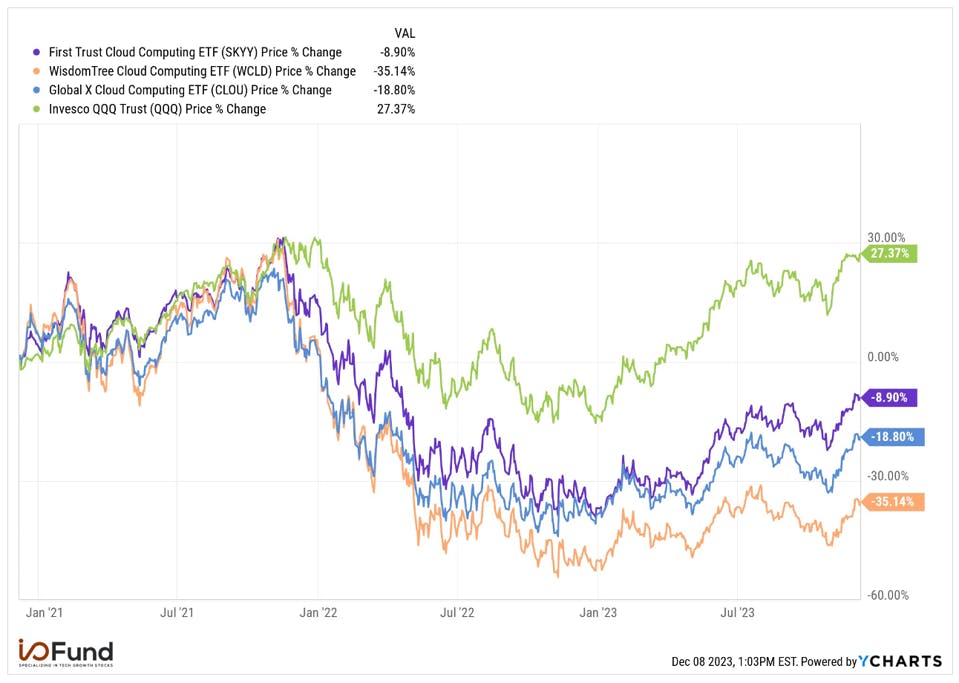
Overall, cloud has lagged broader tech’s rally this year, and on a 3-year basis, returns are still negative, compared to a 27.4% gain for the QQQ. Many cloud darlings in 2020 and 2021 remain far below those highs – take Fastly, for example, where quarterly growth has slowed from the 40% range to the teens, with shares nearly (-80%) lower.
Source: I/O FUND
2023 was a stock picker’s market, and 2024 likely will be as well, with revenue growth rates for a majority of the sector set to slow. Only a few cloud stocks are expected to see revenue growth rates accelerate in 2024. We detail for you the four stocks set to accelerate below.
Sign up for I/O Fund's free newsletter with gains of up to 221% - Click hereClick hereClick here
Palantir
Palantir is one of the Street’s AI favorites this year with a 179% YTD return. The company is exhibiting multiple signs of acceleration heading into 2024 with an improved fundamental backdrop driven by increasing AI demand. Palantir’s Artificial Intelligence Platform (AIP) is driving a significant acceleration in its US commercial business, while underlying metrics and the bottom line are rapidly improving: Palantir posted its first GAAP profitable quarter in February and has since reported four consecutive GAAP profitable quarters.
Customer and US commercial customer growth remains solid, growing 34% and 37% YoY respectively in Q3. CRO Ryan Thomas noted that the US commercial business accelerated in Q3, and excluding strategic commercial contracts, it grew 52% year-over-year and 19% sequentially. Total contract value in the segment increased 55% year-over-year on a dollar-weighted duration basis, with an “acceleration of larger deals and shorter times to conversion and expansion.” He attributed this growth partially to the AI Platform, as the “rapid expansion of AIP at both our existing and new customers, and the impact it is having on their operations is nothing short of remarkable.”
The AI Platform’s growth since its launch in June has also been remarkably strong, with Palantir nearly tripling the number of users in the past quarter, with over 300 organizations using the product in 5 months. Palantir’s profitability is allowing it to continue to “more aggressively invest” in the AI Platform without sacrificing margins, a key differentiator from a majority of cloud AI plays, who are investing in growth at the expense of margins.
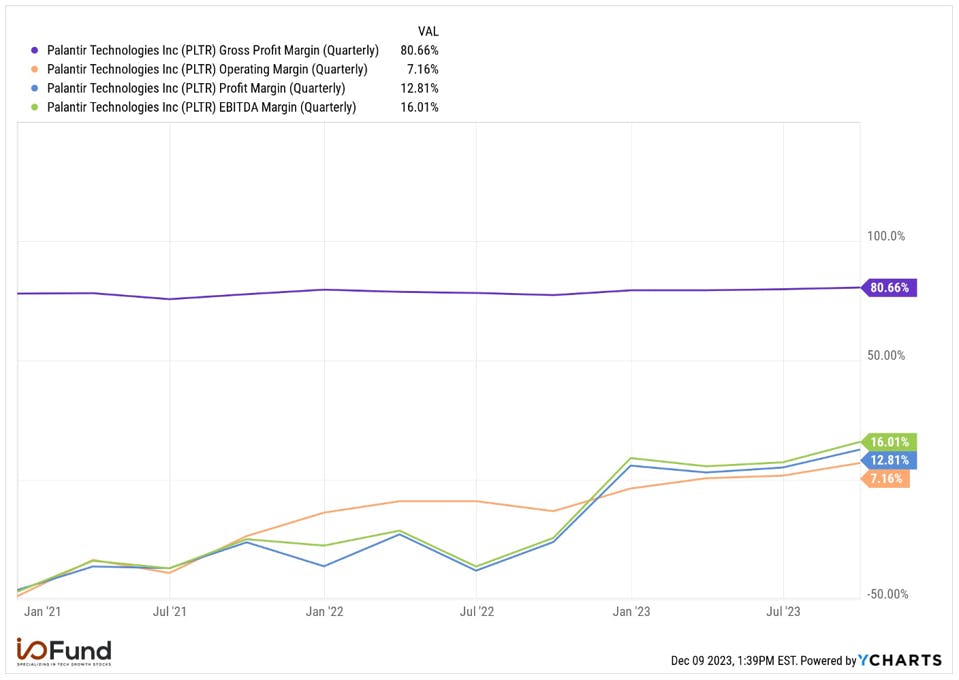
Fundamentally, Palantir is becoming stronger. GAAP gross margin expanded above 80% for the first time in Q3, GAAP operating margin has expanded to 7.2%, and GAAP net margin has risen to 12.8%. Palantir’s EBITDA margin also reached 16% in Q3, its first quarter with a double-digit positive margin, while adjusted free cash flow margin reached 25%. Margins have expanded sequentially in both Q2 and Q3, so the next hurdle will be showing further expansion in Q4 to set up for an increasingly positive trajectory in 2024.
Source: I/O FUND
Revenue growth is poised to accelerate in Q4 and through 2024, boosted by AI demand, a reacceleration in Palantir’s US government segment, and continued strength in the US commercial segment stemming from the Artificial Intelligence Platform. Palantir is currently projected to report 18.5% YoY growth in revenues in Q4, the highest in five quarters, pulling 2023’s full-year revenue growth rate up to a projected 16.5%. 2024 is expected to see an acceleration, with current projections pointing to a 320 bp acceleration in Palantir’s revenue growth rate to 19.7% YoY.
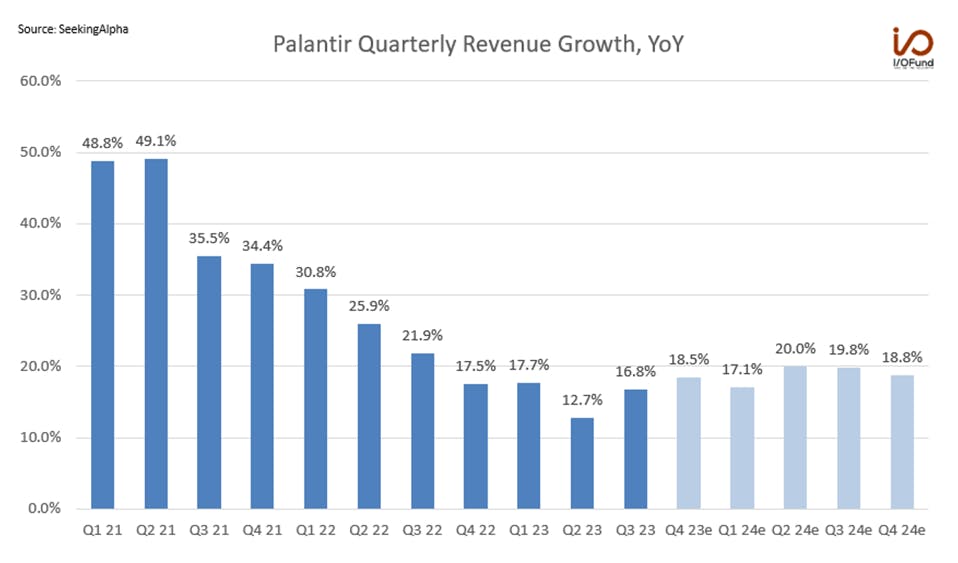
Source: SeekingAlpha
Palantir’s underlying metrics support the revenue reacceleration story, but the stock is by no means cheap at 14.2x 2024 EV/revenue and approximately 52x 2024 operating cash flow. Palantir also noted in Q3 that its net dollar retention rate was 107%, with adverse impacts from its European commercial business. This presents a risk that a land-and-expand strategy places more emphasis on signing more customer deals each quarter, and a slowdown in customer additions raises the risk that the expected revenue acceleration won’t pan out as projected.
Every Thursday at 4:30 pm Eastern, the I/O Fund team holds a webinar for premium members to discuss how to navigate the broad market, as well as various stock entries and exits. We offer trade alerts plus an automated hedging signal. The I/O Fund team is one of the only audited portfolios available to individual investors. Learn more here.Learn more hereLearn more here.
Shift4 Payments
Payments processing firm Shift4 Payments is not a traditional cloud stock, but it has seen significant momentum within its cloud product, SkyTab, alongside positive momentum in a land-and-expand model for its software offerings. Shift4’s recent M&A activity with Appetize and Finaro are expected to significantly contribute to revenue and EBITDA, playing a role in its 1140 bp projected revenue growth acceleration from 31.3% this year to 42.7% in 2024.
Shift4 says it is currently “in the midst of a very successful consolidation” of SkyTab POS, with some of the success owing to a significant total cost of ownership (TCO) advantage relative to competitors. Shift4 installed 8,254 SkyTab systems in Q3, or more than 35% of its cumulative install volume since its launch. Bringing existing customers over to SkyTab boosts ARPU as it is resulting in higher subscription fees per merchant.
Finaro and Appetize’s acquisitions are expected to be accretive to revenue and EBITDA growth starting this quarter and expanding in 2024. Combined, the two are expected to contribute nearly $25M in gross revenue less network fees and $6M in EBITDA in Q4. With Finaro in particular, Shift4 is expecting “a very strong Q4 ahead” as “numerous enterprise accounts have begun processing.”
Financially, Shift4 is the strongest of the four, hitting records across a majority of its metrics, from end-to-end payment volumes, revenue, gross profit, and margins. Gross profit rose 34% YoY to $171M and reached a record 26.7% margin, leading to more operating leverage down the line as operating margin expanded to a record 7.9%, up 490 bp YoY. Net margin improved for a second straight quarter to 4.8%, though it remained 310 bp lower relative to a peak at 7.9% in Q3 last year. Adjusted free cash flow grew 69% YoY to $75.5M.
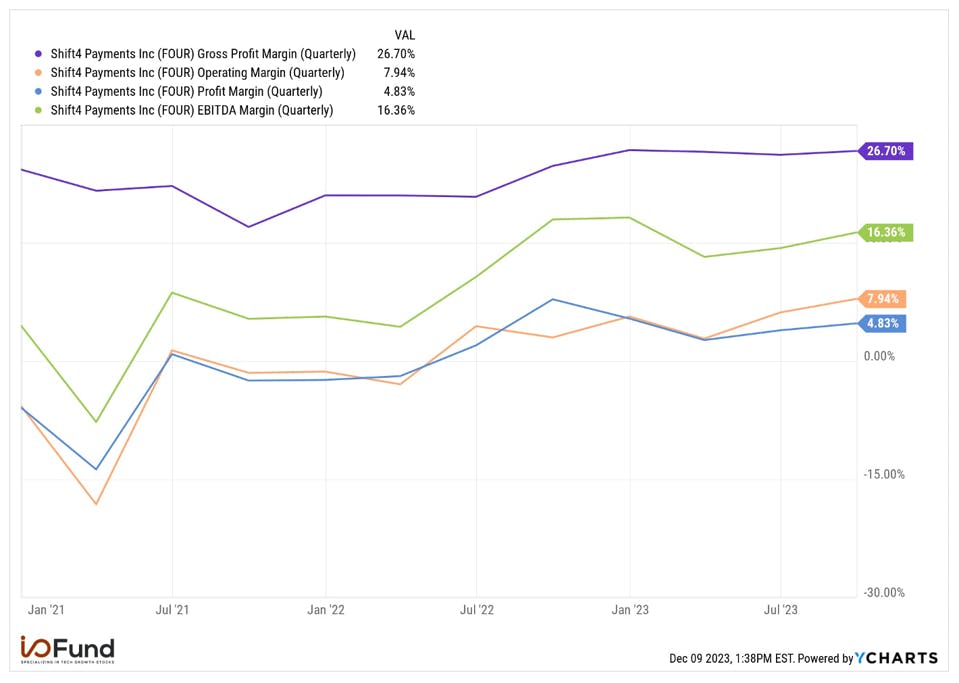
Source: I/O FUND
In 2024, revenue growth is forecast to be >40% YoY in each quarter, from ARPU expansion from SkyTab, net new merchant additions, and contributions from M&A synergies. This represents a rapid acceleration after a four-quarter deceleration, with quarterly revenue growth rates back to levels seen in 2022. However, the main risk to this case is that a pretty swift deceleration is projected in 2025, with revenue growth dropping back to the 28% range. A more uncertain macro backdrop may create some headwinds in 2024 and lead to early signs of a deceleration sooner than expected in late 2024 or 2025.